This article was updated on 21 September 2026 to reflect Albania's comprehensive digital tax framework under Law No. 87/2019 on the Invoice and Turnover Monitoring System (Fiskalizimi). It incorporates the operational architecture of the Central Information System (CIS), technical specifications for UBL 2.1 and UN/CEFACT XML schemas, cryptographic security standards from the National Agency for Information Society (AKSHI), real-time clearance procedures, and statutory compliance rules enforced by the General Directorate of Taxes (DPT).
Introduction & digital tax strategy
Albania operates one of Southeast Europe's most comprehensive Continuous Transaction Control (CTC) regimes. Enacted under the national fiscalisation reform known as Fiskalizimi, the mandate establishes mandatory real-time electronic invoicing and transaction monitoring across the entire domestic economy. Rather than restricting digital controls to public procurement or corporate suppliers, the Albanian framework encompasses Business-to-Government (B2G), Business-to-Business (B2B), and Business-to-Consumer (B2C) operations within a single technical clearinghouse.
The strategic motive behind the reform is structural economic modernisation. By mandating direct system integration between enterprise point-of-sale terminals, enterprise resource planning (ERP) software, and the central tax authority, the government seeks to eradicate the informal economy, prevent value-added tax (VAT) carousel fraud, and create full fiscal transparency.
Administered by the General Directorate of Taxes (Drejtoria e Përgjithshme e Tatimeve - DPT), the framework relies on a centralised clearance architecture. Every commercial transaction, whether settled in cash or through cashless bank transfers, must be registered with and authorised by the central government portal in real time. Transactions lacking state-validated digital verification codes carry no legal standing and cannot support VAT deductibility or business expense recognition.
Historical evolution & EU context
The modernisation of Albania's fiscal landscape represents a deliberate departure from legacy hardware cash registers toward cloud-based continuous controls:
Legacy hardware fiscalisation (pre-2019): For over a decade, Albania relied on traditional stand-alone fiscal memory cash registers. These physical devices stored daily transaction totals and required periodic manual inspection by tax officers, offering limited defence against invoice alteration or unreported business-to-business commerce.
Enactment of Law No. 87/2019: On 18 December 2019, the Albanian Parliament passed Law No. 87/2019 "On the Invoice and the Turnover Monitoring System" (Për faturën dhe sistemin e monitorimit të qarkullimit). Published in the Official Gazette on 20 January 2020, this legislation dismantled the legacy hardware regime in favour of software-driven, real-time fiscal validation.
Phased multi-stage implementation (2020 - 2021): The government phased the nationwide rollout across four distinct waves. The process commenced in September 2020 with large enterprise cash transactions, expanded in January 2021 to cashless B2G transactions, incorporated domestic B2B operations in July 2021, and culminated in September 2021 with full coverage across all consumer cash and non-cash sales.
European Union harmonisation: As an official candidate country for accession to the European Union, Albania drafted Law No. 87/2019 to approximate European standards. The statutory rules align with Directive 2014/55/EU regarding electronic invoicing in public procurement and mirror core provisions of Council Directive 2006/112/EC (the EU VAT Directive). This structural alignment positions the national invoicing framework to adapt cleanly to future cross-border mandates under the EU VAT in the Digital Age (ViDA) initiative.
Complete compliance timeline
The transition to mandatory electronic invoicing and real-time transaction reporting progressed through structured phases, detailed in the table below:
Date | Milestone | Scope and taxpayer impact |
18 December 2019 | Parliamentary approval of Law No. 87/2019 | Enacts the statutory foundation for nationwide Fiskalizimi and real-time invoice clearance. |
20 January 2020 | Publication in Official Gazette No. 3 | Formally promulgates the legislative act and secondary regulatory mandates. |
1 September 2020 | Phase 1: High-turnover cash transactions | Enforces real-time fiscalisation for cash sales by corporate income tax and VAT taxpayers with turnover exceeding ALL 8 million. |
1 January 2021 | Phase 2: Cash transactions & cashless B2G | Expands cash fiscalisation to all small and simplified tax businesses; mandates structured electronic invoicing for all public procurement supplies (B2G). |
1 July 2021 | Phase 3: Mandatory domestic B2B invoicing | Mandates structured electronic invoicing and real-time clearance for all domestic cashless transactions between commercial entities. |
1 September 2021 | Phase 4: Nationwide B2C retail coverage | Final phase extends mandatory fiscalisation to all remaining commercial and retail sales, establishing 100% economic coverage. |
1 January 2022 | Enforcement and statutory sanctions live | Transitional grace periods conclude; tax authorities commence full audit enforcement and financial penalties under Law No. 87/2019. |
Legal framework
Albania's digital tax mandate is anchored in binding statutory acts and executive decisions that prescribe technical formats, data transmission protocols, and electronic signature standards:
Law No. 87/2019 "On the Invoice and the Turnover Monitoring System" (Ligji Nr. 87/2019 "Për faturën dhe sistemin e monitorimit të qarkullimit"): The cornerstone statute that governs invoice content, issuance rules, electronic validation workflows, and system compliance responsibilities for all economic operators.
Law No. 92/2014 "On Value Added Tax in the Republic of Albania", as amended: Defines VAT liability, deduction entitlements, supply classifications, and invoicing rules aligned with EU directives.
Law No. 9920 of 19 May 2008 "On Tax Procedures in the Republic of Albania", as amended: Establishes general tax administration rules, audit procedures, inspection protocols, and statutory penalty frameworks.
Council of Ministers Decisions (VKM) and Ministry of Finance Instructions: Secondary executive regulations governing technical certifications, software functional criteria, security specifications, and operational maintenance standards for digital invoicing platforms.
Authorities
Execution, operational infrastructure, and compliance enforcement are divided across key public institutions:
General Directorate of Taxes (DPT)
The General Directorate of Taxes (Drejtoria e Përgjithshme e Tatimeve - DPT) operates under the Ministry of Finance and Economy. As the primary competent tax authority, the DPT:
Administers and operates the national Central Information System (Sistemi Qendror i Informacionit - CIS).
Evaluates, approves, and licenses commercial billing software solutions.
Conducts real-time transactional monitoring, audit reviews, and field inspections.
Enforces statutory penalties for non-compliance and unverified invoicing.
National Agency for Information Society (AKSHI / NAIS)
The National Agency for Information Society (Agjencia Kombëtare e Shoqërisë së Informacionit - AKSHI) serves as the technical backbone for state digital infrastructure. For Fiskalizimi, AKSHI:
Acts as the central trust service provider issuing mandatory electronic certificates.
Generates and secures public key infrastructure (PKI) credentials required for cryptographic message signing.
Administers the national e-Albania portal used for administrative business onboarding and authentication.
Ministry of Finance and Economy
The Ministry oversees national fiscal policy, drafts primary legislation, and publishes binding administrative guidelines defining implementation timelines and fiscal parameters.
Scope of the mandate
The Albanian mandate applies to all natural and legal persons conducting economic activities within the territory of the Republic of Albania.
B2G | B2B | B2C |
Mandatory | Mandatory | Mandatory |
Cashless e-invoicing | Cashless e-invoicing | Cash & cashless sales |
Real-time CIS clear | Real-time CIS clear | POS fiscalisation |
State Treasury routing | Self-Care / API delivery | Verifiable QR code |
Business-to-Government (B2G)
Mandatory since 1 January 2021. Economic operators supplying goods, works, or services to public sector entities must generate structured electronic invoices. These invoices must clear the DPT central system and register with the public treasury system before public bodies can issue disbursements.
Business-to-Business (B2B)
Mandatory since 1 July 2021. All domestic sales between corporate entities, sole proprietorships, and freelance professionals must be issued as structured electronic invoices. This covers all cashless operations settled via bank wire, credit card, or payment intermediaries. Without exception, paper invoices and plain PDF documents exchanged directly between companies carry no legal validity for tax deduction purposes.
Business-to-Consumer (B2C)
Mandatory since September 2021. Commercial retailers and consumer service providers must issue fiscalised receipts for every point-of-sale supply, encompassing both physical cash transactions and card payments.
Cross-border and non-resident supplies
The mandate governs international transactions involving Albanian taxable persons:
Exports: Domestic suppliers exporting goods or delivering services to non-resident entities must issue an electronic invoice through the central system, clearing the transaction under standard export VAT exemption codes.
Imports of services (reverse charge): Where an Albanian enterprise purchases services from a foreign supplier unable to access the central platform, the local purchaser must execute a self-invoicing (vetëfaturim) procedure and clear the record through the system no later than the 10th day of the following calendar month.
Foreign entities registered for VAT: Non-resident companies maintaining a tax identification number (NIPT) in Albania must fully interface with the Fiskalizimi platform for all taxable supplies located within Albanian jurisdiction.
E-invoicing requirements
Under Law No. 87/2019, an electronic invoice is legally defined as a structured XML document created, transmitted, validated, and archived electronically in a machine-readable format.
To issue compliant electronic invoices, economic operators must fulfill strict operational prerequisites:
Tax Identification Number (NIPT/NUIS): Registered with the National Business Centre (Qendra Kombëtare e Biznesit - QKB).
AKSHI Electronic Certificate: An official digital certificate for fiscalisation obtained via the e-Albania portal, linked to the enterprise NIPT.
Certified billing software: Invoicing software certified by the DPT or direct use of the state-provided Self-Care web portal.
Business unit registration: Mandatory pre-registration of every physical office, warehouse, retail store, and commercial website on the DPT portal at least 24 hours before issuing the first invoice.
Authorised operator registration: Active registration of every commercial employee or software operator authorised to generate invoices on behalf of the business.
Technical data elements: NIVF and NSLF
Every cleared electronic invoice displays two critical technical control parameters:
NSLF (Numri Serial i Sigurisë së Lëshuesit): The Invoice Issuer Security Code. A cryptographic hash generated by the taxpayer's software using the issuer's private key, signing an input string that combines the taxpayer NIPT, issue timestamp, invoice sequence number, business unit code, operator code, and total invoice price.
NIVF (Numri i Identifikimit të Vlefshëm të Faturës): The Unique Invoice Identification Code (equivalent to a clearance UUID). This 32-character hexadecimal code is generated exclusively by the DPT central clearing server upon successful semantic and mathematical validation of the invoice payload.
An electronic invoice possesses no legal standing in Albania unless it incorporates both the issuer's NSLF and the tax administration's cleared NIVF.
Invoice presentation and QR code
When delivering a human-readable visual rendering (PDF or printed receipt) to a trading partner or consumer, the document must embed a standardised, scannable QR code. The QR code encodes a dynamic verification URL hosted on the DPT portal:
https://efiskalizimi-app.tatime.gov.al
Scanning this code directs the recipient to the government database, displaying real-time confirmation that the transaction has been recorded, approved, and cleared.
Accepted invoice formats
Albania requires structured XML messaging following internationally recognised semantic data models:
UN/CEFACT XML (Schema 16B): Heavily utilised for standard transactional web services and POS communications.
ISO/IEC 19845:2015 (UBL 2.1): Standard Universal Business Language schema, aligned with the European e-invoicing standard EN 16931.
Unstructured formats, including scanned images, Microsoft Excel sheets, and stand-alone PDFs sent by email without an underlying cleared XML structure, are legally invalid.
Archival obligations
Both issuers and recipients must store all structured electronic invoices, clearance tokens, and validation logs in their original XML format for a minimum statutory period of 5 years from the end of the calendar year in which the invoice was issued. Archived records must guarantee authenticity of origin, content integrity, and human legibility throughout the retention timeframe.
E-reporting requirements
Unlike jurisdictions that separate structured electronic invoice exchange from periodic digital tax reporting, Albania embeds Continuous Transaction Controls (CTCs) directly into the invoicing workflow.
Real-time transaction clearance
E-reporting in Albania operates in true real time:
Pre-issuance submission: The billing software transmits the complete XML transaction payload to the DPT central server via secure SOAP/REST APIs over HTTPS before the document is released to the buyer.
Immediate processing: The DPT clearance engine checks mathematical calculations, VAT rates, buyer and seller registration statuses, and cryptographic certificates within milliseconds.
Synchronous return: The DPT server appends the cleared NIVF code and returns the approved fiscal payload to the issuer.
Fallback procedures and offline contingency reporting
The law accounts for connectivity interruptions, recognizing that network outages must not paralyze commercial operations:
Offline issuance: If an active internet connection fails, the taxpayer's software issues the invoice locally, generating the cryptographic NSLF code but omitting the NIVF code.
Mandatory printed indicator: The human-readable invoice must state that it was generated in offline mode.
The 48-hour submission window: The taxpayer must establish internet connectivity and transmit all cached offline transactions to the central DPT clearing server within 48 hours of issuance. Upon successful post-clearance, the central server registers the invoices and returns the corresponding NIVF codes.
Technical architecture: The centralised clearance model
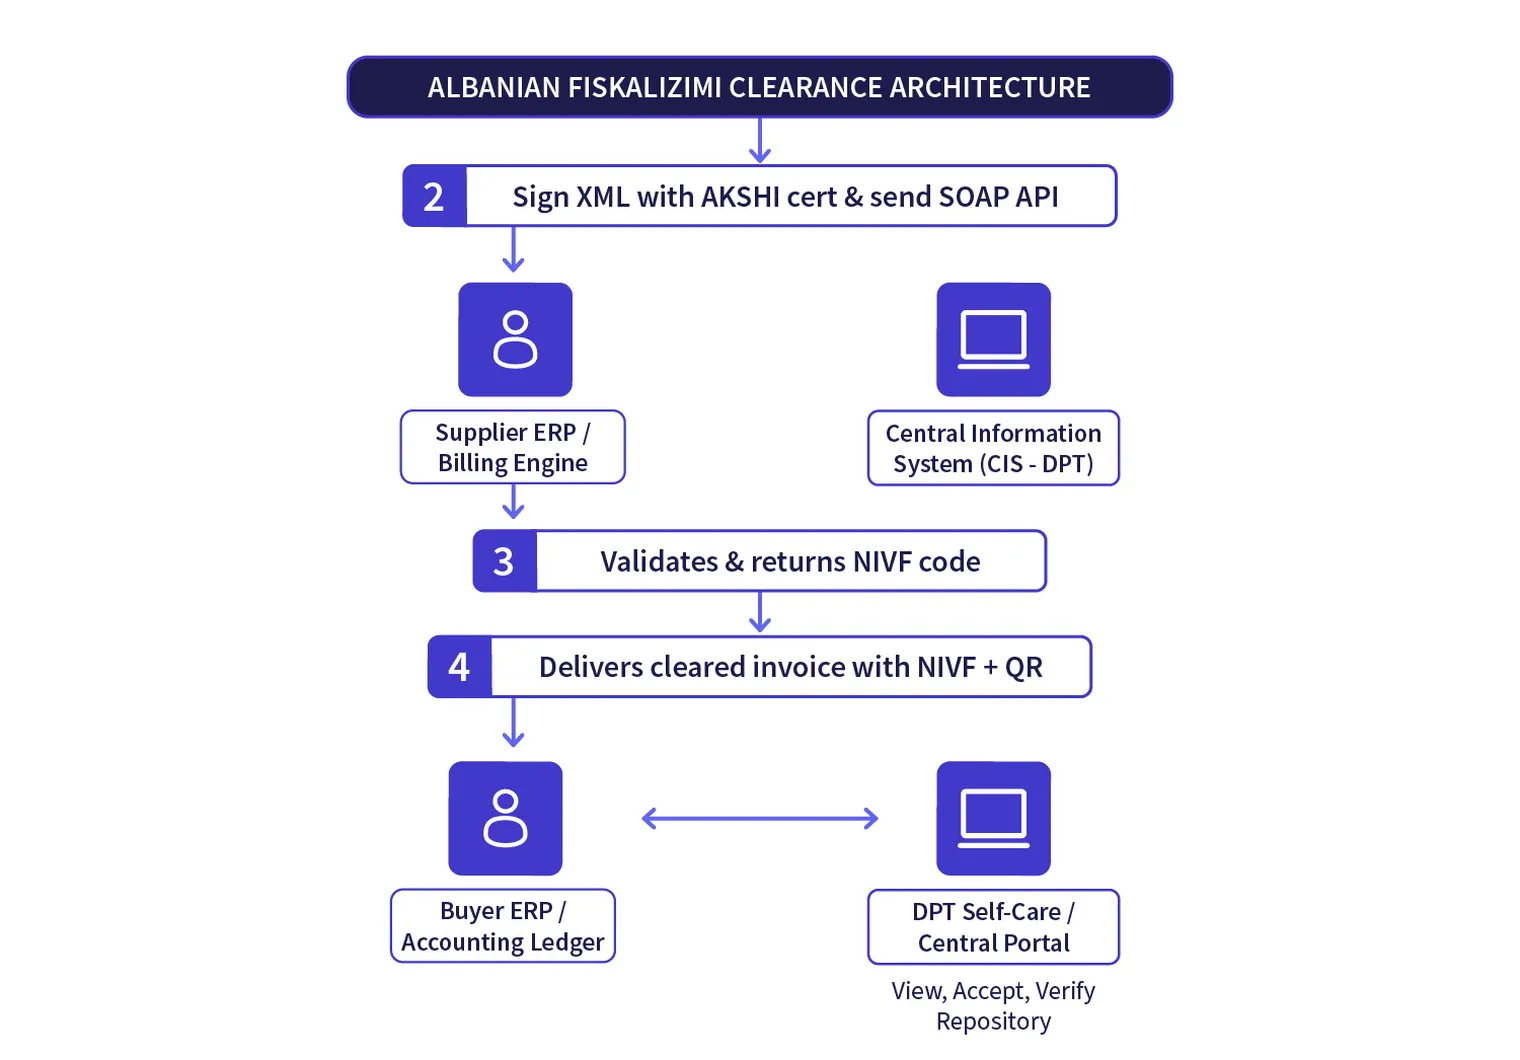
Albania operates a centralised clearance model. All billing systems communicate through a central clearinghouse operated by the state, rather than routing data through private, decentralised networks.
Workflow mechanics
Invoice generation: The supplier generates the invoice within certified accounting software, compiling mandatory transaction metadata, tax rates, and line items.
Cryptographic hashing: The software hashes the payload using the enterprise AKSHI certificate, producing the NSLF code.
Transmission to CIS: The signed payload is transmitted via secure web services to the Central Information System.
Validation and clearance: The DPT system verifies the payload, issues the NIVF clearance code, and logs the transaction in the national fiscal ledger.
Buyer delivery: The supplier delivers the cleared electronic invoice (containing both NSLF and NIVF) to the buyer. Delivery occurs through direct software-to-software integration or through the DPT Self-Care web portal, where registered buyers can review, accept, or reject incoming bills.
Penalties for non-compliance
Non-compliance with Law No. 87/2019 triggers stringent financial penalties, administrative sanctions, and business closures under the Albanian Tax Procedures Law:
Violation category | In-scope entity | Statutory fine (Albanian Lek - ALL) |
Failure to issue a fiscalised invoice (omitting real-time clearance or issuing unverified invoices) | Sole proprietors / Natural persons | ALL 25,000 to ALL 50,000 |
Failure to issue a fiscalised invoice (omitting real-time clearance or issuing unverified invoices) | Legal corporate entities | ALL 100,000 to ALL 200,000 |
Operating uncertified billing software | Software vendor or maintainer | ALL 200,000 to ALL 400,000 |
Failure to register business premises/operators | Taxpayers conducting economic activity | ALL 50,000 per unregistered unit |
Failure to upload offline invoices within 48 hours | Taxpayers experiencing connection failure | ALL 25,000 to ALL 100,000 |
Persistent repeat violations (within 12 months) | Any commercial enterprise | Temporary closure of business operations for up to 30 days |
Commercial and operational consequences
Disallowance of input VAT deduction: The DPT strictly disallows input VAT deductions on commercial purchases unsupported by an invoice bearing a verified NIVF clearance code.
Disallowance of corporate income tax expense: Operating expenses lacking a validated Fiskalizimi record are treated as non-deductible for corporate profit tax (Tatimi mbi Fitimin) assessments, increasing corporate tax liabilities.
Treasury blockades on public contracts: Public sector buyers are legally barred from processing payments for public procurement contracts unless the supplier's electronic invoice is validated in the central system.
How businesses can prepare
Maintaining compliance under Albania's real-time fiscalisation framework requires ongoing operational discipline and secure IT systems. Organisations should adopt the following structured approach:
1. Maintain active AKSHI digital certificates
Electronic certificates issued by AKSHI have defined validity periods. Organisations must establish administrative tracking to renew credentials well ahead of expiry. An expired certificate halts billing software operations immediately, preventing real-time clearance.
2. Verify software certification and API health
Confirm that your ERP or billing software is officially certified by the DPT and can handle real-time SOAP/REST XML exchange. For multinational entities using global ERPs (such as SAP, Microsoft Dynamics, or Oracle), implement certified local middleware to translate internal invoice data into the required UN/CEFACT or UBL 2.1 schemas.
3. Cleanse taxpayer master data
The CIS clearance engine validates recipient data instantly. Inaccurate buyer Tax Identification Numbers (NIPT), mismatched legal trade names, or invalid business unit codes trigger immediate rejection. Perform periodic master data clean-ups across customer registers.
4. Implement offline resilience protocols
Ensure your billing software supports offline operation, caching transactions and generating valid NSLF hashes during network outages. Configure automated queues that dispatch cached documents to the DPT server as soon as connectivity recovers, guaranteeing compliance with the mandatory 48-hour submission rule.
5. Establish inbound AP verification workflows
Accounts payable teams must systematically verify received supplier invoices. Staff should confirm that incoming bills display valid NIVF numbers and check the DPT verification portal before booking invoices to ledger accounts, safeguarding corporate input VAT deductions.
Conclusion
Albania's Fiskalizimi framework stands as an advanced continuous transaction control system. By mandating that every commercial event across B2G, B2B, and B2C channels clear the central government platform in real time, the General Directorate of Taxes maintains comprehensive visibility over the national economy.
For domestic and international businesses operating in Albania, compliance requires reliable IT infrastructure. Maintaining active AKSHI electronic certificates, deploying certified invoicing software, cleansing master data, and verifying inbound NIVF codes are essential operational measures.
As digital tax standards continue to develop across Europe under the EU VAT in the Digital Age (ViDA) initiative, organisations that embed robust, automated compliance workflows today will safeguard their input VAT deductions, avoid severe operational penalties, and trade confidently within Albania's digital marketplace.
FAQ
No. Standard PDF invoices, word processor documents, or spreadsheets delivered by email do not constitute legal tax invoices for domestic B2B transactions. A valid invoice must be generated in a structured XML format, cleared through the Central Information System (CIS), and display both the NSLF and NIVF codes.