This article was updated on 21 September 2026 to reflect the latest regulatory directives issued by the General Directorate of Internal Taxes (Dirección General de Impuestos Internos - DGII). It incorporates Aviso 14-26 published on 26 August 2026, which mandates the exclusive issuance of type "E" electronic tax receipts (comprobantes fiscales electrónicos - e-CF) for Large Local and Medium taxpayers from 1 November 2026 and invalidates legacy type "B" sequences after 31 October 2026. It also details Aviso 06-26, which extends the mandatory compliance deadline for small, micro, and unclassified enterprises to 15 November 2026 under Law No. 32-23 and Decree No. 587-24.
Introduction & digital tax strategy
The Dominican Republic is establishing one of the Caribbean's most advanced digital tax systems through the mandatory adoption of electronic invoicing (facturación electrónica). Administered by the General Directorate of Internal Taxes (Dirección General de Impuestos Internos - DGII), the national reform transitions the entire commercial economy from paper documents to digitally validated Electronic Tax Receipts (comprobantes fiscales electrónicos - e-CF). The strategic objective is to widen the formal tax base, eliminate invoice falsification, improve Value Added Tax (Impuesto sobre las Transferencias de Bienes Industrializados y Servicios - ITBIS) collection, and modernise commercial trade.
Unlike decentralised post-audit regimes, the Dominican Republic operates an authentic Continuous Transaction Controls (CTC) pre-clearance model. Every taxable transaction must be converted into a structured, digitally signed XML document and cleared by the DGII central platform before or at the moment of issuance to the buyer. This approach gives the tax administration immediate visibility over commercial activity, curbing carousel fraud and phantom invoicing schemes.
On 26 August 2026, the DGII issued an urgent regulatory directive, Aviso 14-26, declaring that from 1 November 2026, all Large Local (Grandes Locales) and Medium (Medianos) taxpayers must exclusively issue electronic tax receipts bearing type "E" series identifiers. Ordinary type "B" legacy paper sequences assigned to these businesses will lose legal validity after 31 October 2026, remaining accessible solely for cases of officially declared contingency. Concurrently, under Aviso 06-26, the final wave of small, micro, and unclassified taxpayers must complete their technical onboarding by 15 November 2026. This milestone marks the final phase of the country's multi-year digital tax overhaul.
Historical evolution & global context
The digitalisation of tax administration in the Dominican Republic has developed over two decades, transitioning from basic serial control numbers to real-time electronic data validation:
Introduction of the Tax Receipt Number (2006 - 2007): The Dominican tax system established structural transaction oversight through Decree No. 254-06, which introduced the standard Tax Receipt Number (Número de Comprobante Fiscal - NCF). This mechanism assigned alphanumeric series (such as type "B" sequences) to track invoicing and curb sales under-reporting.
Electronic Invoicing Pilot Project (2019 - 2020): Seeking greater operational efficiency, the DGII launched a voluntary pilot programme in February 2019 with major corporate enterprises. This initiative tested electronic invoice generation, digital signature validation using X.509 certificates, and automated API communication. The formal regulatory framework for this pilot was codified under General Norm No. 01-2020.
Enactment of Law No. 32-23 (May 2023): On 16 May 2023, the Dominican Government enacted Law No. 32-23 on Electronic Invoicing, establishing mandatory e-invoicing across all commercial enterprises and public sector institutions. The law defined a phased implementation roadmap over 36 months and introduced targeted tax incentives to accelerate early adoption.
Implementing Decree No. 587-24 (October 2024): To operationalise Law No. 32-23, the Executive Branch issued Decree No. 587-24, establishing formal regulations on technical XML schemas, digital signature certification, contingency protocols, and accredited Electronic Invoicing Service Providers (Proveedores de Servicios de Facturación Electrónica - PSFE).
Latin American CTC alignment: The Dominican Republic's clearance model aligns structurally with mature Latin American Continuous Transaction Control (CTC) architectures, such as Mexico's CFDI, Chile's DTE, and Brazil's NF-e. In contrast to European decentralised approaches, such as the Peppol 5-corner network or France's Y-model, the Dominican framework relies on direct real-time clearance through a central government portal. To compare how these different models function worldwide, read our detailed guide on navigating global e-invoicing architectures.
Complete compliance timeline
The implementation of mandatory electronic invoicing in the Dominican Republic follows a phased roadmap based on taxpayer classification, culminating in nationwide coverage in November 2026.
Date | Taxpayer group | Regulatory requirement |
16 May 2023 | Nationwide | Promulgation of Law No. 32-23 on Electronic Invoicing, initiating the statutory transition schedule. |
15 January 2024 | National Large Taxpayers (Group 1) | Mandatory e-CF issuance enters into force for the first cohort of National Large Taxpayers. |
15 May 2024 | National Large Taxpayers (Full scope) | Deadline for all National Large Taxpayers (Grandes Contribuyentes Nacionales) to complete production onboarding under DGII Notice 08-23. |
15 November 2025 | Large Local & Medium Taxpayers | Extended onboarding deadline for Large Local and Medium taxpayers actively integrating certified software. |
6 May 2026 | Small, Micro & Unclassified | DGII issues Aviso 06-26, granting a six-month administrative extension to 15 November 2026. |
26 August 2026 | Large Local & Medium Taxpayers | DGII issues Aviso 14-26, establishing exclusive type "E" e-CF issuance and sunsetting type "B" legacy sequences. |
31 October 2026 | Large Local & Medium Taxpayers | Expiry date for standard commercial use of non-electronic type "B" Tax Receipt Numbers for Large Local and Medium taxpayers. |
1 November 2026 | Large Local & Medium Taxpayers | Mandatory exclusive issuance of type "E" e-CF takes effect. Legacy type "B" sequences are restricted to declared emergency contingencies. |
15 November 2026 | Small, Micro & Unclassified Taxpayers | Final nationwide deadline for small, micro-enterprises, and unclassified taxpayers to issue mandatory e-CF under Law No. 32-23. |
Legal framework
Electronic invoicing in the Dominican Republic is governed by primary statutory legislation, presidential decrees, and administrative general norms issued by the DGII:
Law No. 32-23 on Electronic Invoicing (Ley Núm. 32-23 de Facturación Electrónica): Enacted on 16 May 2023, this statute establishes the nationwide mandate for electronic invoicing, defines the legal validity of electronic tax receipts, details taxpayer obligations, establishes the phased implementation calendar, and prescribes penalties for non-compliance.
Decree No. 587-24 (Decreto Núm. 587-24): Published in October 2024, this decree sets out the formal implementing regulations for Law No. 32-23. It specifies the technical parameters for XML creation, accredited digital certificates, contingency protocols under Chapter IX, and the operational framework for third-party electronic invoicing software providers.
Tax Code of the Dominican Republic (Ley Núm. 11-92 - Código Tributario de la República Dominicana): Serves as the overarching tax legislation governing general taxpayer duties, bookkeeping standards, and administrative penalty mechanisms.
Law No. 126-02 on Electronic Commerce, Documents and Digital Signatures (Ley Núm. 126-02 sobre Comercio Electrónico, Documentos y Firmas Digitales): Regulates the legal equivalence of digital signatures and electronic records compared to physical documents.
DGII Aviso 14-26: Published on 26 August 2026, this binding administrative notice enforces the exclusive issuance of type "E" electronic tax receipts for Large Local and Medium taxpayers starting 1 November 2026, restricting type "B" non-electronic receipts to declared contingencies.
DGII Aviso 06-26: Published on 6 May 2026, this notice formalises the administrative extension of the mandatory e-invoicing deadline for small, micro, and unclassified taxpayers to 15 November 2026.
Competent authorities
The governance, validation, and enforcement of electronic invoicing in the Dominican Republic involves several public institutions:
General Directorate of Internal Taxes (DGII)
The General Directorate of Internal Taxes (Dirección General de Impuestos Internos - DGII) is the state tax authority responsible for administering domestic taxes, value-added tax (ITBIS), and excise duties. Under Law No. 32-23, the DGII operates the national electronic invoicing clearinghouse, maintains the official e-CF portal, approves digital billing software, and monitors taxpayer compliance across the country.
Dominican Institute of Telecommunications (INDOTEL)
The Dominican Institute of Telecommunications (Instituto Dominicano de las Telecomunicaciones - INDOTEL) is the regulatory authority for telecommunications and postal services. Under Law No. 126-02, INDOTEL accredits and supervises public certification authorities (Entidades de Certificación) that issue legally valid digital signature certificates (X.509) required for signing electronic invoices.
Ministry of Finance (Ministerio de Hacienda)
The Ministry of Finance establishes national fiscal policy and oversees revenue mobilisation strategies. It coordinates with the DGII to ensure that digital tax tools integrate with broader state budget systems and public expenditure controls.
Scope of the mandate
The Dominican electronic invoicing mandate applies to all natural and legal persons registered in the National Taxpayer Registry (Registro Nacional de Contribuyentes - RNC) carrying out commercial activities. The scope covers domestic business, government procurement, retail transactions, and specific international operations.
Business-to-Business (B2B) transactions
All commercial sales of goods and supplies of services between domestic businesses must be documented via electronic tax receipts. Businesses must issue Electronic Tax Credit Invoices (Factura de Crédito Fiscal Electrónica - type E31). Input ITBIS deductions and corporate income tax expense deductibility are strictly contingent upon holding a validated type E31 e-CF issued by the supplier and verified by the DGII.
Business-to-Government (B2G) transactions
Supplies to the Central Government, decentralised agencies, social security institutions, and state-owned enterprises must be invoiced electronically using Electronic Governmental Receipts (Comprobante Gubernamental Electrónico - type E45). Public sector accounting offices are legally prohibited from processing payment vouchers that lack a cleared type E45 receipt.
Business-to-Consumer (B2C) transactions
Retail sales and consumer services are documented using Electronic Consumer Invoices (Factura de Consumo Electrónica - type E32). For transactions under DOP 250,000, simplified issuance mechanisms apply. If the transaction exceeds this statutory threshold, the customer's national identity card (Cédula) or tax identification number (RNC) must be included within the electronic XML record.
Cross-border and export transactions
Cross-border supplies are covered by dedicated electronic document categories:
Exports (type E46): National exporters and companies operating in Free Trade Zones (Zonas Francas) must document export sales using Electronic Export Receipts (Comprobante para Exportaciones Electrónico - type E46).
Payments to non-residents (type E47): When domestic entities make payments for taxable Dominican-source income to foreign entities without local tax registration, they must issue Electronic Receipts for Foreign Payments (Comprobante para Pagos al Exterior Electrónico - type E47) to document statutory income tax withholdings.
Scope overview table
Transaction category | Applicable e-CF series | Mandatory clearance channel | Recipient requirement |
Commercial B2B | Type E31 (Crédito Fiscal) | Centralised DGII web service API | Structured XML delivery to buyer |
Public Procurement (B2G) | Type E45 (Gubernamental) | Centralised DGII web service API | Cleared e-CF delivery to state body |
Retail Consumer (B2C) | Type E32 (Consumo) | Real-time or batch daily clearance | Printed or digital visual representation |
Cross-Border Exports | Type E46 (Exportaciones) | Centralised DGII web service API | International commercial dispatch |
Foreign Remittances | Type E47 (Pagos al Exterior) | Centralised DGII web service API | Documenting foreign tax withholding |
Special Tax Regimes | Type E44 (Regímenes Especiales) | Centralised DGII web service API | Supplies to tax-exempt entities |
Dominican Republic e-invoicing requirements
Under Law No. 32-23, an electronic invoice is not an unstructured document such as a standard PDF sent via email. To be legally valid, an invoice must be constructed as a structured electronic document conforming to official technical specifications, signed cryptographically, and cleared through the DGII clearance hub.
Key Takeaway: An invoice in the Dominican Republic is legally non-existent unless cleared by the DGII; relying on legacy paper type B sequences after statutory phase deadlines eliminates buyer ITBIS deductions and triggers financial sanctions.
Digital signature requirements
Every electronic tax receipt must be signed digitally by the issuer before submission to the DGII. The digital signature must be backed by a qualified digital certificate (X.509 standard) issued by a certification entity accredited by INDOTEL. The certificate must be linked to the taxpayer's legal identity and representative registered with the RNC. The digital signature ensures three core principles:
Authenticity of origin: Guarantees that the document was generated by the registered taxpayer.
Integrity of content: Ensures that the document has not been altered after transmission.
Non-repudiation: Establishes conclusive legal evidence that the issuer dispatched the transaction.
Commercial delivery to the buyer
Once an e-CF is cleared by the DGII, the issuer must deliver the document to the buyer:
Electronic receivers: If the buyer is registered with the DGII as an electronic receiver, the supplier must deliver the cleared XML document electronically (via system-to-system web services or secure email).
Non-electronic receivers: If the recipient is not yet onboarded to the e-CF framework (such as retail consumers), the issuer must provide a standard visual representation (Representación Impresa - RI) in physical printout or electronic PDF format.
Visual representation standards and QR code
The visual representation must contain mandatory summary data elements, including:
Identification of the issuer and buyer (legal name, RNC, commercial address).
The electronic series number (e-NCF) with its characteristic "E" prefix.
Transaction totals, line-item breakdowns, and calculated ITBIS.
The digital security code (Código de Seguridad), which is an encrypted alphanumeric hash generated during clearance.
A dynamic, two-dimensional QR code. When scanned with a mobile device, this QR code links directly to the official DGII validation portal, allowing immediate confirmation of document authenticity.
Archiving obligations
Law No. 32-23 establishes that all issued and received electronic tax receipts, together with their clearance receipts and digital signature metadata, must be archived securely for a minimum of 10 years. The archive must preserve the original XML files in readable and unaltered condition to satisfy audit requirements.
E-reporting requirements & transactional filings
The Dominican Republic maintains a comprehensive transactional reporting framework that operates alongside electronic invoicing. As taxpayers transition to real-time e-CF clearance, their monthly reporting duties are simplified, but formal filing obligations remain active during the transitional period.
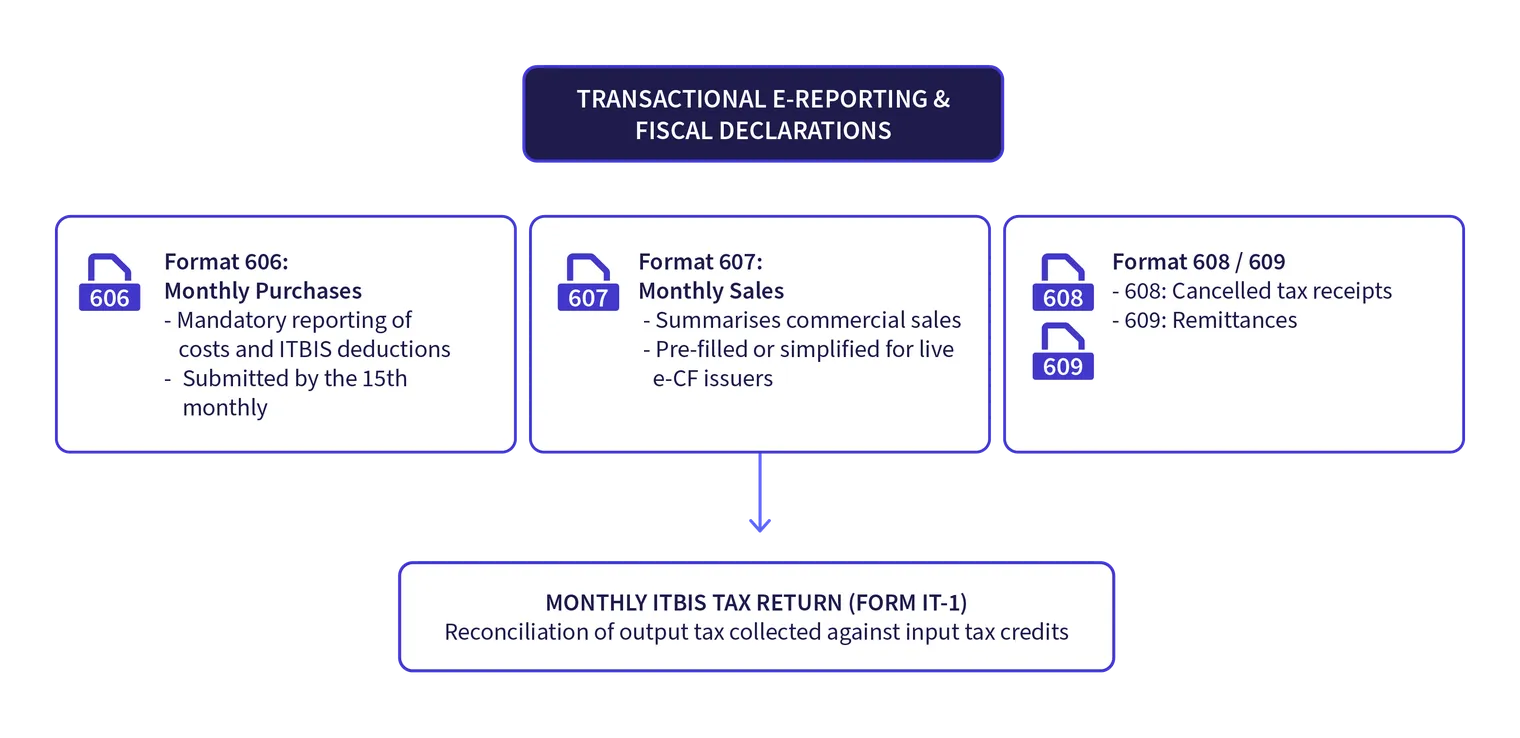
Interplay between e-CF and periodic reporting formats
Dominican tax legislation requires registered entities to submit detailed periodic electronic registers using designated formats:
Format 606 (Purchases of goods and services): Taxpayers must submit a monthly breakdown of all business purchases, operating costs, and input ITBIS deductions by the 15th day of the following month. Even when receiving electronic invoices, businesses must maintain this register to support deductions.
Format 607 (Sales of goods and services): Taxpayers must file a monthly report of all commercial sales. For taxpayers who issue 100% of their sales through type E electronic tax receipts, the DGII automatically reconciles and pre-populates sales data, reducing the manual burden of this filing.
Format 608 (Cancelled receipts): Used to report cancelled or voided NCF and e-NCF numbers during the tax period, ensuring sequential integrity.
Format 609 (Payments abroad): Reports payments made to foreign entities for services rendered or intangible assets used in the Dominican Republic.
Form IT-1 and automated VAT pre-population
The transactional data cleared through e-CF platforms feeds directly into the DGII tax intelligence database. This structural integration allows the tax authority to cross-examine reported ITBIS withholdings, sales outputs, and input deductions prior to the submission of the monthly VAT return (Form IT-1), reducing audit disputes and processing delays.
Technical architecture
The Dominican e-invoicing architecture is structured as a centralised clearance model. It requires direct, system-to-system electronic data exchange between the taxpayer's Enterprise Resource Planning (ERP) or point-of-sale software and the DGII processing centre.
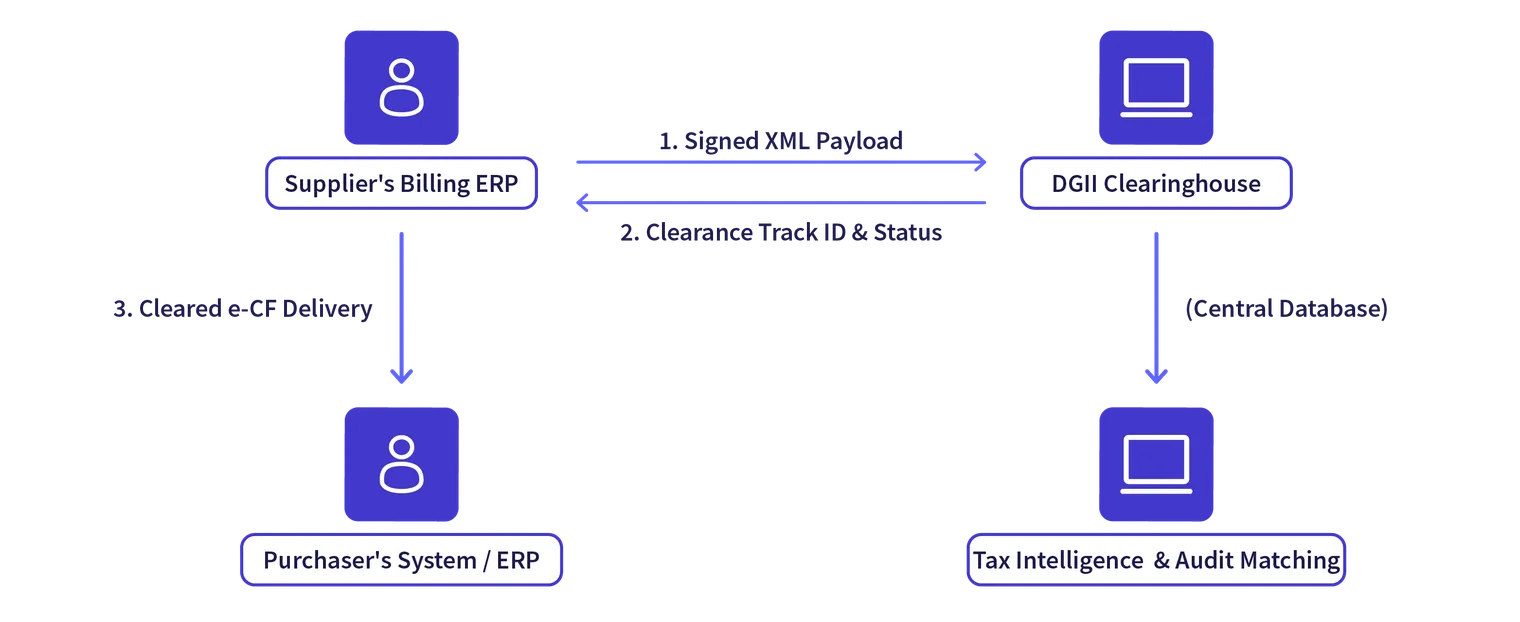
Core architectural components
Billing engine: The taxpayer's accounting software or ERP creates the structured invoice payload in XML syntax.
Cryptographic signing module: A software engine or Hardware Security Module (HSM) applies the X.509 digital certificate, generating a cryptographic hash over the XML document.
DGII clearance API: A dedicated web service interface exposed by the tax authority. The taxpayer's billing system establishes a secure TLS connection, authenticating with access tokens to submit the signed XML.
Validation engine: The DGII clearinghouse automatically parses the payload, validates structural schemas, checks sequence numbers, verifies the active status of both RNC identifiers, and returns an immediate clearance track ID (TrackID) with an acceptance, conditional approval, or rejection status code.
Electronic Invoicing Service Providers (PSFE): Entities certified by the DGII to provide software, integration tools, and hosting services to commercial taxpayers.
How the centralised clearance model works
The operational workflow for generating and issuing a compliant electronic tax receipt follows a continuous transaction sequence:
Step 1: Document generation
The commercial transaction takes place. The supplier's ERP software compiles all commercial data (buyer details, line items, unit prices, discounts, and applicable ITBIS rates) and generates an XML file following the technical schema established by the DGII.
Step 2: Digital signing
The supplier's billing system processes the XML document through its cryptographic module, applying the digital signature using the taxpayer's certified X.509 certificate. This step locks the content against post-issuance tampering.
Step 3: Web service transmission to DGII
The signed XML document is transmitted via secure REST or SOAP web services to the DGII clearinghouse.
Step 4: Clearance validation
The DGII platform performs real-time automated checks:
Validates that the issuer's RNC is active and authorised to issue e-CF.
Checks that the recipient's RNC exists and matches official tax registry data.
Verifies that the electronic sequence number (e-NCF) is valid and unconsumed.
Evaluates the mathematical calculation of line items and tax totals.
Verifies that the digital signature is mathematically valid and unexpired.
Step 5: Clearance response
The DGII issues an automated clearance response containing:
An acceptance code (Aceptado), conditional acceptance, or rejection error notice.
A unique tracking identifier (TrackID).
The official digital security code (Código de Seguridad).
Step 6: Commercial delivery to the buyer
Upon receipt of the DGII clearance confirmation, the supplier delivers the cleared electronic invoice to the buyer:
To electronic buyers: Transmission of the approved XML payload via web service or secure electronic channels.
To non-electronic buyers: Issuance of the visual representation (RI) containing the mandatory two-dimensional QR code and digital security code.
What a Dominican e-invoice looks like
A Dominican electronic invoice is an XML file structured according to the DGII's mandatory technical schema. The document is divided into defined operational modules containing standardised fiscal tags.
Mandatory data components
Document header (Encabezado): Identifies the document type code, the 11-character alphanumeric e-NCF series number, issue date, payment terms, and expiration date.
Issuer information (Emisor): Full legal company name, commercial trade name, RNC number, registered fiscal address, municipality, and administrative contact details.
Purchaser information (Comprador): Legal entity name, RNC or identity card (Cédula), fiscal domicile, and buyer classification.
Itemised details (Detalle de Bienes o Servicios): Line-by-line item numbering, proprietary product code, standard commercial description, quantity, unit of measurement, unit pricing, applicable commercial discounts, and itemised ITBIS tax rates (typically 18%, 16%, or exempt).
Totals module (Totales): Total net taxable base, total non-taxable amount, total calculated ITBIS, total excise taxes (Impuesto Selectivo al Consumo - ISC) where applicable, and final payable balance in Dominican Pesos (DOP) or foreign currency with applicable exchange rates.
Cryptographic signature block (Firma Digital): Contains the cryptographic digest value, the public key certificate details, and the XML-DSig structure confirming authenticity.
Accepted invoice formats & electronic tax receipts
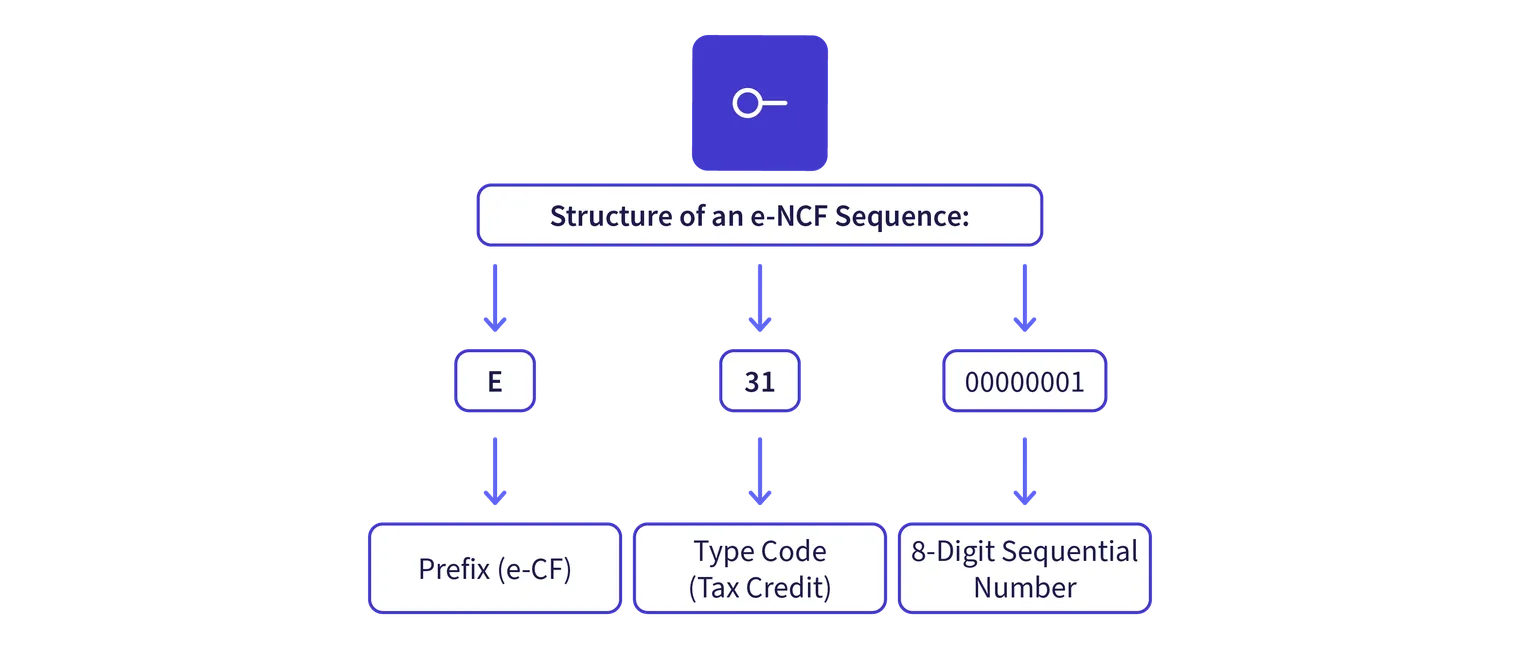
Under the Dominican digital tax framework, electronic tax receipts are classified into specific series. Each series begins with the uppercase letter "E", followed by a two-digit type identifier and an eight-digit sequential serial number.
Structure of an e-NCF Sequence:
Complete directory of e-CF document types
The DGII defines ten specialised electronic tax receipt categories:
Type E31 - Electronic Tax Credit Invoice (Factura de Crédito Fiscal Electrónica): Used for commercial B2B sales between registered taxpayers. It provides legal documentation for business expenses and input ITBIS tax deductions.
Type E32 - Electronic Consumer Invoice (Factura de Consumo Electrónica): Used for retail B2C transactions with final consumers. It documents final consumption and does not confer tax deduction rights to the purchaser.
Type E33 - Electronic Debit Note (Nota de Débito Electrónica): Used by sellers to recover post-issuance commercial costs, such as interest penalties or shipping adjustments, related to a previously cleared invoice.
Type E34 - Electronic Credit Note (Nota de Crédito Electrónica): Used to correct, void, or adjust a previously cleared invoice, documenting partial returns, commercial discounts, or price reductions.
Type E41 - Electronic Purchase Receipt (Comprobante Electrónico de Compras): Issued by registered commercial entities when acquiring goods or services from natural persons not registered with the RNC.
Type E43 - Electronic Minor Expense Receipt (Comprobante Electrónico para Gastos Menores): Issued by taxpayers to justify internal operating expenses and petty disbursements incurred by staff (such as local travel or consumables).
Type E44 - Electronic Special Regime Receipt (Comprobante Electrónico para Regímenes Especiales): Used to document sales to natural or legal entities operating under preferential tax regimes or duty-free exemptions.
Type E45 - Electronic Governmental Receipt (Comprobante Electrónico Gubernamental): Mandatory for commercial sales of goods and services supplied to Central Government ministries, state institutions, and municipal entities.
Type E46 - Electronic Export Receipt (Comprobante Electrónico para Exportaciones): Used by domestic exporters and companies in Free Trade Zones to register sales of goods to foreign buyers outside the Dominican Republic.
Type E47 - Electronic Foreign Payment Receipt (Comprobante Electrónico para Pagos al Exterior): Issued when remitting taxable Dominican-source payments to foreign entities without a domestic permanent establishment, supporting statutory tax withholdings.
Contingency procedures
Chapter IX of Decree No. 587-24 and Aviso 14-26 regulate operational handling during technical disruptions. Because commercial trade cannot stop during system outages, the law provides contingency mechanisms.
Declared contingency conditions
A contingency situation arises when an issuer cannot communicate with the DGII clearinghouse due to:
Documented internet connectivity failures or extended telecommunication blackouts.
Power system breakdowns affecting local servers.
Scheduled or unannounced downtime of the central DGII clearinghouse.
Use of legacy type "B" receipts in contingency
Under Aviso 14-26, Large Local and Medium taxpayers whose standard type "B" sequences lose general validity after 31 October 2026 are permitted to maintain a limited reserve of contingency type "B" numbers. When a contingency event occurs, the taxpayer may issue physical type "B" receipts to customers.
Post-contingency reconciliation
Once connectivity is restored, the taxpayer must transmit all transactions issued under contingency to the DGII within the statutory timeframe prescribed by the tax administration (typically within 48 to 72 hours). Failure to reconcile contingency documents on schedule constitutes a formal tax violation.
Statutory penalties for non-compliance
The Dominican tax administration enforces electronic invoicing through financial sanctions, administrative restrictions, and operational penalties established in Law No. 32-23 and the Tax Code.
Violation category | Statutory reference | Legal & financial consequence |
Failure to issue e-CF | Law No. 32-23, Art. 27 & Tax Code, Art. 257 | Administrative fines ranging from 5 to 30 national minimum wages. |
Use of expired type "B" sequences | DGII Aviso 14-26 & Law No. 32-23 | Document declared legally invalid; failure to issue valid tax receipt. |
Disallowance of tax deductions | Tax Code, Art. 288 & Law No. 32-23 | Complete disallowance of input ITBIS deductions and corporate income tax expense deductibility for the purchaser. |
Repeat non-compliance | Tax Code, Art. 257 | Temporary commercial closure of premises for 3 to 60 business days. |
Falsification of digital records | Penal Code & Law No. 32-23 | Criminal prosecution and suspension of taxpayer commercial operations. |
Beyond direct financial fines, non-compliant enterprises face significant operational disruption. The DGII automatically suspends the taxpayer's ability to obtain tax compliance clearance certificates (Certificaciones Tributarias), excluding the business from state tenders, commercial credit approvals, and normal financial operations.
How businesses can prepare
Meeting the Dominican electronic invoicing deadlines requires structured collaboration across internal IT, procurement, accounting, and tax operations. Businesses should take the following operational steps:
1. Verify taxpayer classification and implementation wave
Review the company's status in the DGII Virtual Office (Oficina Virtual). Determine whether your business is classified as a Large Local, Medium, or Small/Micro taxpayer to confirm your binding compliance deadline:
Large Local and Medium taxpayers: Must configure systems for exclusive type "E" issuance before 1 November 2026.
Small, Micro, and Unclassified taxpayers: Must complete technical onboarding before 15 November 2026.
2. Procure an INDOTEL-accredited digital certificate
Acquire a qualified digital signature certificate (X.509 standard) from an accredited certification provider in the Dominican Republic. Ensure the certificate is registered under the legal representative's credentials and configured within the billing software.
3. Evaluate billing software and integration options
Assess current ERP software (such as SAP, Oracle, Microsoft Dynamics, or local accounting tools). Choose the appropriate deployment model:
In-house development: Connect internal ERP engines directly to DGII web services via API.
Certified Electronic Invoicing Service Provider (PSFE): Partner with an accredited software provider to manage XML transformation, digital signing, and automated clearance.
DGII free invoicing tool (Facturador Gratuito): Designed for micro-enterprises and solo entrepreneurs with low monthly invoice volumes, accessible directly through the DGII Virtual Office.
4. Cleanse customer and supplier master data
Perform an audit across customer and vendor master files. Ensure all Dominican trading partners have verified RNC identifiers, correct legal names, and updated commercial addresses to prevent real-time clearance rejections by the DGII platform.
5. Establish automated accounts payable validation
Configure accounts payable workflows to verify incoming invoices. Ensure systems can read XML files, validate clearance tracking numbers (TrackID), and check QR code integrity before processing supplier payments.
Conclusion
The implementation of mandatory electronic invoicing under Law No. 32-23 and Decree No. 587-24 represents the most significant modernisation of the Dominican Republic's tax system in decades. By moving to a real-time Continuous Transaction Controls (CTC) clearance model, the DGII is creating a transparent commercial environment that reduces fraud, secures ITBIS revenue, and streamlines business administration.
With 1 November 2026 marking the strict cut-off for Large Local and Medium taxpayers to discontinue ordinary type "B" sequences under Aviso 14-26, and 15 November 2026 establishing full nationwide enforcement across all small and micro-enterprises under Aviso 06-26, businesses must take immediate action.
Organisations that review their internal billing processes, partner with certified software providers, and upgrade their ERP systems will ensure uninterrupted commercial operations while benefiting from automated invoice processing in the Dominican Republic's digital marketplace.
FAQ
No. An unstructured PDF delivered via email is not a legally valid tax invoice under Law No. 32-23. To be legally recognised for tax credit and corporate expense deduction purposes, transactions must be documented through a structured XML file bearing an accredited digital signature and cleared by the DGII. The PDF serves solely as a visual representation for human reading.