Why e‑invoicing/e‑reporting is different from past compliance projects
Over the past years, the landscape of tax compliance - and with it, the relationship between tax authorities and businesses - has shifted fundamentally. We are no longer living in an era of sporadic, batch-based reporting; instead, we are talking about a complete restructuring, moving toward a paradigm of “real-time compliance”.
From periodic returns to continuous transaction controls (CTCs): We are moving away from retrospective, monthly, or quarterly VAT returns. Tax authorities now want real‑time or near real‑time visibility into your invoice data flows. This shift from “batch” reporting to “transactional” reporting means that data quality issues can no longer be fixed at the end of the month: they must be resolved at the point of creation.
Direct impact on core business processes: Because these mandates connect directly to your transaction systems, e‑invoicing is not just a tax issue; it directly impacts your Order‑to‑Cash (O2C), Procure‑to‑Pay (P2P), and Record‑to‑Report processes. If your systems fail, your payments stop. This is a critical business continuity risk, not a compliance footnote.
A multi‑jurisdiction challenge: With overlapping mandates across the EU (ViDA), GCC, LATAM, and APAC, a country‑by‑country approach is increasingly risky. You need a unified strategy, or you risk being buried under fragmented, unmanageable local requirements that create massive overhead for your finance teams.
Key takeaway: E‑invoicing is a cross‑functional transformation programme, not a one‑off compliance task. It requires a shift in mindset from “tax compliance” to “digital business transformation”.
The stakeholder landscape: who needs to be involved and why
Because e‑invoicing cuts across departments, it requires a multidisciplinary task force of stakeholders, aligned on business objectives as well as technical execution. If any of these groups are siloed, the project risks either missing a compliance deadline or, worse, breaking critical operational workflows.
Core stakeholder groups (common to all organisations)
Tax / Indirect Tax / VAT: As the primary sentinels of the organisation, the Tax department must monitor legislative changes, assess the impact, and define the compliance requirements and the overall risk appetite. Their role is to translate complex, local legislative changes into clear functional requirements for the IT and Finance teams, and to liaise with external advisors and, where relevant, tax authorities.
Finance / Accounting / Accounts Receivable & Payable: This group owns the “meat” of the process: the actual cash flow. They must ensure that shifting to e-invoicing doesn't disrupt liquidity, nor the customer/supplier experience. Their primary focus is validating that invoice content, approval workflows, and general ledger posting remain intact throughout the transition.
IT / Enterprise Architecture / ERP: The IT department acts as the architect for the infrastructure. They must assess system impact and integration options, and design a solution that avoids “spaghetti integrations” - those messy, ad-hoc connections that become impossible to maintain over time. Their role is to ensure system performance, data quality, and iron-clad security.
Procurement / Supply Chain (especially for inbound/e‑reporting): Often overlooked, this group is the gateway for inbound processes. They must lead the strategic effort of onboarding suppliers to e-invoicing networks, ensuring that vendors are capable of meeting your new legal and operational standards, and, where applicable, align purchase‑to‑pay processes with any new requirements. This may include new requirements around digital archiving and compliance; monitoring of incoming invoices via tax authority portals, and ensuring rejections, if any, are flagged immediately; updating the matching logic to incorporate PO vs. receipt vs. invoice, and any automatic data enrichment to avoid having to revert to manual data entry.
Legal / Compliance / Data Protection: With the increasing scrutiny on digital data transfer, Legal must review the contractual implications with customers and suppliers while assessing data residency and privacy obligations across various global regimes.
Additional stakeholders for larger or international groups
Country finance / local statutory reporting teams: These individuals act as your local reality check. While global templates are useful, local statutory teams possess the nuanced understanding of regional administrative practices, language barriers, and the specific expectations of local auditors. They are the ones who must bridge the gap between global standardised processes and the “on-the-ground” legal reality of their jurisdiction.
Global process owners (Order‑to‑Cash / Procure‑to‑Pay): The GPO role is to act as the guardian of the global standard. Their challenge is to resist the temptation to “over-localise”. When each country demands a unique customisation, the system becomes brittle. The GPO must balance the need for global process efficiency with the hard requirements of local legal mandates, ensuring that exceptions are minimised rather than institutionalised.
Shared services / BPO providers: Shared service centres are the primary operators of your new invoicing ecosystem. Their operating models, Service Level Agreements (SLAs), and key performance indicators (KPIs) must be completely overhauled to account for the move from manual, document-centric tasks to automated, data-centric workflows. They are the front line for reconciling centralised processing with the country-specific mandates that inevitably crop up.
Information security / cybersecurity: E-invoicing necessitates connecting your internal ERP to external tax authority portals, often in real-time. This changes your threat surface. Cybersecurity must review your API connections, encryption standards, authentication protocols, and access controls. They must also perform rigorous third-party risk assessments on any vendors or platforms you use to process these transactions.
Customer success / sales operations: Invoices are not just accounting documents; they are a key part of the customer journey. If an invoice format changes or a new digital portal is introduced, Sales Operations must lead the communication strategy. They must proactively manage the message to customers to mitigate the risk of payment delays, disputes, or damaged relationships caused by the friction of new digital processes.
How the stakeholder landscape evolves by organisation type
The composition of your project team will inevitably shift depending on your organisation’s scale and footprint. While the core principle, i.e., that e-invoicing cannot be owned by one function alone, remains universal, the “weight” and number of stakeholders involved change significantly as complexity increases.
For SMEs and smaller businesses, the project is often handled by a lean team, frequently the owner, manager, or an external accountant, who wears multiple hats. In these scenarios, the focus is squarely on simplicity, cost, and minimising disruption. Because these businesses typically lack dedicated tax or IT departments, the strategy is less about internal orchestration and more about vendor reliance. The organisation relies heavily on their existing ERP or accounting vendor to act as their “compliance partner”, ensuring that the technical heavy lifting is outsourced.
Domestic corporates with a single-country focus face a different challenge. Here, internal functions like Tax, Finance, and IT are well-defined, allowing for a structured internal project team. The primary stakeholder challenge is aligning existing systems with the specific requirements of that single jurisdiction. Because international complexity is limited, the focus is on process efficiency and ensuring the e-invoicing solution integrates seamlessly into established ERP workflows. The risk here is not global fragmentation, but rather creating a “one-off” solution that fails to scale if the business eventually expands.
For multinationals, the complexity becomes exponential. With multiple jurisdictions, languages, and varying legislative timelines, the project transforms into an exercise in high-level orchestration. You are managing a dense web of stakeholders, including global and regional tax leads, local country finance teams, Global Process Owners (GPOs), and shared service centres. The critical success factor here is maintaining global standardisation while navigating the necessity of localisation. The ultimate goal is to avoid the trap of “country-by-country silos”, where each region develops its own unique technical solution, by implementing a global governance framework that prioritises common standards over local idiosyncratic needs.
A practical project lifecycle and stakeholder involvement
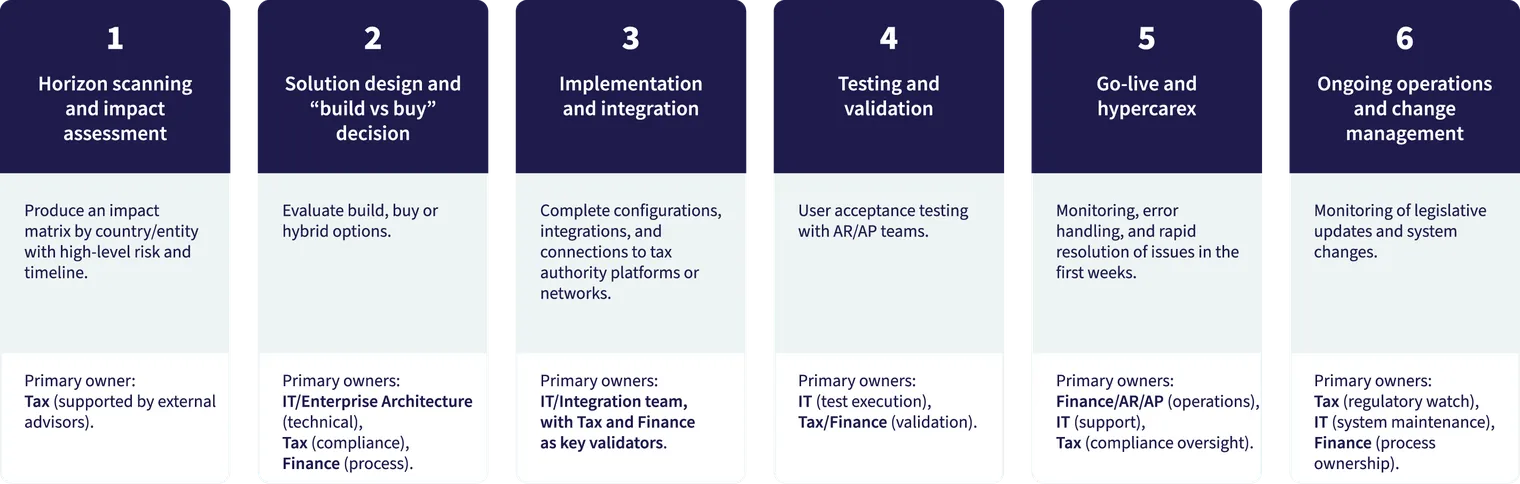
Successful e-invoicing is not a project with a fixed end date; it is an ongoing lifecycle. The process begins with Horizon scanning or Compliance watch, where the tax team acts as a “radar system”, monitoring new mandates and draft laws to identify which of the upcoming mandates will impact the organisation, and to assess precisely which entities, systems, and processes will be affected.
This leads into Solution design, where IT, Tax, and Finance must collaborate to define future functional and technical requirements, and to map current systems and data flows. During this phase, you should also initiate your initial “build vs. buy” assessment: determining whether to develop a proprietary solution or procure a managed service (see our strategic breakdown in Section 4), before selecting a vendor, if applicable.
Following design, the Implementation phase requires intense IT-business coordination and involves configuring or developing the solution, as well as integrating with ERPs, billing, procurement, and document management systems. This is also the step where any connections to tax authority platforms or networks (such as Peppol or other national portals) are set up.
Once implemented, it is crucial to move from the theory of design to the reality of Testing and Training: never rely solely on a vendor’s “sandbox” environment. Be sure to involve the frontline business teams who will know what real-world invoice scenarios you should use to validate the data. Crucially, this phase is your best opportunity for change management. By involving frontline AR/AP staff in testing, you not only validate the data but also train them on new systems, ensuring that when go-live day arrives, the team is already comfortable with the new processes.
Finally, the Go-live and Hypercare phase requires a “Command Centre” approach, with a carefully choreographed cutover plan and customer/supplier communication. We strongly recommend smoke testing on launch day, i.e., running a small, controlled batch of live transactions with trusted suppliers or customers before scaling to large volumes. Key aspects are active monitoring of the first invoices and error handling, where regular (even daily, if needed) meetings in the first 30 days solve the inevitable “teething issues” that arise when new integrations go live. This creates a feedback loop that ensures the system evolves with the business.
Once the initial hypercare period ends, the focus shifts to sustainability and to Ongoing operations and change management. This involves establishing a permanent routine for monitoring legislative updates, conducting periodic reviews of vendor performance and internal controls, and planning the scale-up to additional countries. This ensures your project remains a resilient asset rather than a technical debt.
Build vs buy: strategic considerations
The boardroom debate regarding “Build vs. Buy” is often framed as a technology decision, but it is actually a strategic decision regarding your business model. Put simply: do you want to own and maintain the technical infrastructure to stay compliant with hundreds of global tax rules, or do you want to pay a specialist to shoulder that burden for you? This debate pits the desire for absolute control against the need for agility and speed. 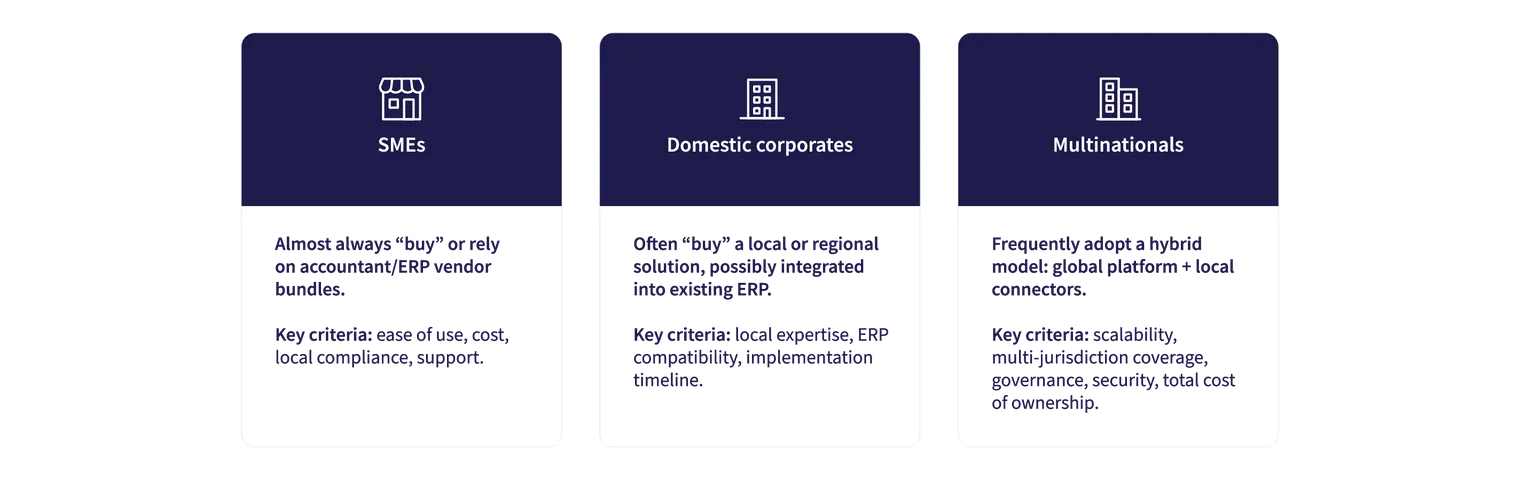 When “buy” (vendor/managed service) makes sense
Buying a managed service is the logical path for organisations that need speed, multi-country coverage, and the “regulatory watch” service that keeps you compliant as laws change. It effectively outsources the risk. Some key drivers to select the buy model include:
Limited internal development capacity (typical for SMEs and many mid‑caps).
Need for speed to meet tight legislative deadlines.
Desire for pre‑certified, regularly updated compliance content.
Multi‑country coverage via a single platform or network.
Preference for predictable OPEX over large CAPEX projects.
When “build” (in‑house/custom) may be justified
Building in-house is typically only justified for massive, proprietary systems where an off-the-shelf product cannot integrate without extensive, costly middleware. Some key drivers include:
Very large scale with highly standardised global processes.
Strong internal development and integration capabilities.
Complex, unique business models not well served by standard products.
Strategic desire to control roadmap and data flows end‑to‑end.
Hybrid models
For most multinationals, a hybrid model is the gold standard: using a global compliance platform as the “core” for consistency, paired with local, custom connectors that handle specific, idiosyncratic country mandates.
Core compliance engine from a vendor, with custom front‑ends or workflows.
Central platform with local extensions for specific country rules.
Internal team managing integration and vendor relationships.
Strategic drivers for the build vs. buy decision
SMEs
Almost always “buy” or rely on accountant/ERP vendor bundles.
Key criteria: ease of use, cost, local compliance, support.
Domestic corporates
Often “buy” a local or regional solution, possibly integrated into existing ERP.
Key criteria: local expertise, ERP compatibility, implementation timeline.
Multinationals
Frequently adopt a hybrid model: global platform + local connectors.
Key criteria: scalability, multi‑jurisdiction coverage, governance, security, total cost of ownership.
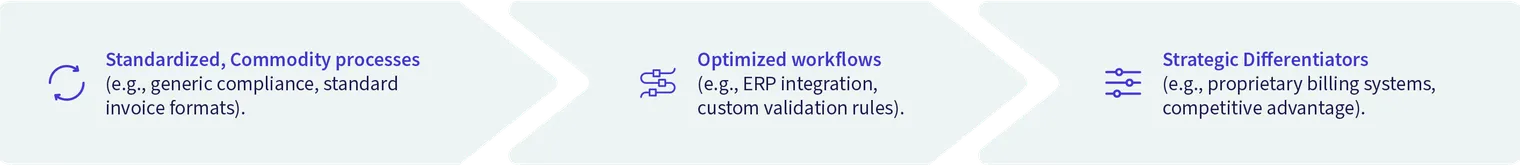 Ultimately, this choice is less about technology preference and more about your appetite for risk, your internal capabilities, and your long-term operating model.
Governance and operating model
Without a formal governance structure, you will inevitably end up with a project that is “compliant but broken” (Tax-heavy, ignoring O2C flows) or “operational but non-compliant”(IT-heavy, ignoring regulations).
The governance structure
To manage this, we recommend a tiered approach:
At the top, a steering committee consisting of senior representation from across the business (Tax, Finance, IT, and, for multinationals, regional leads) must exist to set priorities, approve budgets, and resolve trade-offs, not just to receive status reports.
Beneath them, the project core team (Project Manager, Tax/IT/Finance leads, and process owners) drives day-to-day execution.
Finally, you must empower country/local workstreams; these local tax/finance/IT representatives are essential, as they are the only ones capable of implementing the specific nuances of a local jurisdiction.
RACI clarity
Crucially, you must establish RACI clarity early. Who is truly accountable for the final “Go-Live” decision? If this is left ambiguous, you will face months of finger-pointing when the first invoice fails. By clearly defining who is Responsible, Accountable, Consulted, and Informed for each milestone, from regulatory interpretation to solution design, testing, and finally to sign-off, you transform a complex, multi-stakeholder programme into a manageable series of decisions.
Common pitfalls and how to avoid them
Most failures in e-invoicing are organisational, not technical. The most common killer is the so-called “silo effect” combined with the late involvement of key stakeholders; when IT runs the show in a vacuum, or when AR/AP and local country teams are brought in only at the eleventh hour, you build a system that works technically but fails to address operational realities.
Conversely, the “data trap”, underestimating the state of your master data, is a frequent oversight. If your customer tax IDs are missing, invalid, or incorrectly mapped in the ERP, your automation will fail regardless of how much you spend on the platform.
Furthermore, many teams ignore the external side of the equation. E-invoicing is a change for your customers and suppliers. If you do not communicate with them early and prepare them for the shift, you will face delays in payment and potential data disputes.
Finally, avoid over-customisation. Creating a solution that is so bespoke it becomes impossible to maintain when regulations change is a strategic dead end.
Practical guidance for implementation
For SMEs
Prioritise simplicity. Your focus should be on “does this connect to my accounting software?” Engage your accountant or ERP partner early and seek out a solution that offers strong local support. Test with a small set of invoices before rolling out globally.
For domestic corporates
Pilot first. Do not attempt a “big bang” rollout across your entire company. Appoint a project lead who can bridge the gap between tax and IT, map your current processes, and evaluate vendors based on their ability to integrate with your existing ERP.
For multinationals
Develop a “global playbook”. Make your processes repeatable so that when the next country mandate hits, you don't have to start from scratch. Establish a Global Programme Office and prioritise your rollout based on risk, transaction volume, and legislative deadlines.
For SMEs | For domestic corporates | For multinationals |
|
|
|
Conclusion
E‑invoicing and e‑reporting are now permanent features of the tax and finance landscape. For SMEs, the priority is choosing simple, compliant solutions and avoiding last‑minute rushes. For domestic corporates, the focus is on aligning one jurisdiction’s rules with existing systems. For multinationals, the challenge is orchestrating multiple stakeholders, systems and timelines without creating fragmented, country‑specific silos.
Across all organisation types, the differentiator between success and struggle is rarely the technology itself. It is clear stakeholder engagement, disciplined governance and a realistic “build vs buy” strategy that can evolve as mandates multiply. The capabilities built for today’s requirements will become the foundation for future digital tax and reporting obligations.

Danielle Kiener
Lead Key Account Manager, Banqup Group
Danielle has more than 15 years of experience in customer relationship management within invoicing and financial administration. She currently works in Geneva, supporting global customers at Banqup Group and helping multinational companies digitalise their processes. Over the years, she has been closely involved in the digital transformation of invoicing, including leading e-invoicing initiatives across the EMEA and Asia-Pacific regions for a major multinational. Her extensive experience means she’s always up to date on the latest e-invoicing regulations and changes around the world.