This article was updated on 21 September 2026 to incorporate the latest regulatory and technical developments issued by the National Tax Service (Servicio de Impuestos Nacionales - SIN). This update reflects the active consultation under Board Resolution No. 102600000034 regarding proposed modifications to the technical annex of the billing system, alongside the finalised compliance deadline of 1 October 2026 for Taxpayer Groups 9 to 12 enacted under Resolution RND No. 102600000007.
Introduction & digital tax strategy
Bolivia operates a digital billing system that mandates structured electronic invoicing and real-time transaction reporting across its domestic economy. Administered by the National Tax Service (Servicio de Impuestos Nacionales, commonly known as SIN), the Integrated Tax Administration System (Sistema Integrado de la Administración Tributaria - SIAT) establishes continuous transaction controls over corporate and retail commerce. The strategic objective of the Bolivian government is to broaden the formal tax base, eliminate Value Added Tax (Impuesto al Valor Agregado - IVA) evasion, and modernise commercial accounting workflows through end-to-end digital audit trails.
The Bolivian framework shifts commercial accounting away from detached, retrospective declarations towards continuous fiscal clearance and synchronous reporting. Under the current regulatory structure, taxpayers assigned to an online billing modality must generate each fiscal invoice in structured XML syntax, validate security credentials with the tax administration, and transmit document payloads to SIAT in real time or within strict contingency windows. Taxpayers and their accounting advisors can independently confirm their assigned billing modality using the official online classification portal operated by SIN.
While Groups 1 through 8 have passed their statutory enforcement dates, enterprise and mid-market taxpayers in Groups 9 through 12 face an imminent compliance deadline on 1 October 2026. Concurrently, SIN continues to refine the underlying technical specifications, evidenced by the release of Board Resolution No. 102600000034 in September 2026. This administrative act initiated an early consultation on upcoming technical adjustments to the SIAT technical annex, demonstrating that tax compliance in Bolivia requires constant technical vigilance and ongoing infrastructure alignment.
"Electronic invoicing in Bolivia is not an isolated IT project: it is an active legal condition for commercial validity and corporate VAT deductibility."
Historical evolution & global context
Bolivia's transition toward digital tax administration spans nearly two decades of legislative trials, infrastructure upgrades, and iterative technical models:
New Invoicing System (2007): Bolivia initiated structured invoice controls under the New Invoicing System (Nuevo Sistema de Facturación - NSF-07), enacted through Resolution RND No. 10-0016-07. This early mechanism introduced initial computerised authorisation codes (Código de Autorización de Facturas) but relied heavily on physical paper printouts and delayed batch declarations.
Virtual Invoicing System (2016): On 1 January 2016, SIN launched the Virtual Invoicing System (Sistema de Facturación Virtual - SFV), regulated under Resolution RND No. 10-0025-14. The SFV introduced digital invoice modalities, QR codes, and electronic bookkeeping ledgers (Libro de Compras y Ventas IVA), though connectivity limitations prevented universal real-time clearance.
The 2018 electronic transition attempt: SIN attempted a full shift toward online billing under Resolution RND No. 101800000026 on 20 November 2018 (Sistema de Facturación Electrónica - SFE). This model was repeatedly postponed and eventually restructured to accommodate domestic IT constraints and industry readiness.
Modern SIAT online modalities (2021 - Present): The current regulatory framework was codified through Resolution RND No. 102100000011, establishing three modern online modalities (Portal Web en Línea, Computarizada en Línea, and Electrónica en Línea). Rollout began on 1 December 2021 with large taxpayers (Principales Contribuyentes - PRICOS) under Resolutions RND No. 102100000012 and RND No. 102100000017.
Regional and global comparative context
Within the broader Latin American landscape, Bolivia's SIAT aligns with the centralised Continuous Transaction Control (CTC) clearance mechanisms established in Chile, Mexico, and Brazil. Unlike European decentralised models, such as the Peppol-based 4-corner networks emerging under the EU's VAT in the Digital Age (ViDA) initiative or France's Partner Dematerialisation Platform (PDP) Y-model, Bolivia routes fiscal authority directly through a state clearinghouse. Every digital document generated in the economy must interface with SIN servers to secure unique algorithmic authorisation. For multinational businesses operating across both European and South American jurisdictions, adapting to Bolivia requires implementing direct API pipelines, daily authorisation codes, and digital signature certificates rather than open-network routing.
To examine how centralised clearance frameworks compare with decentralised 5-corner models globally, consult our technical analysis on navigating global e-invoicing compliance architectures.
Complete compliance timeline
The transition to mandatory online invoicing in Bolivia has progressed through staged administrative resolutions targeting specific taxpayer groups based on commercial turnover, economic sector, and transaction volume:
Date | Legal instrument | Regulatory milestone |
18 May 2007 | RND No. 10-0016-07 | Launch of the New Invoicing System (Nuevo Sistema de Facturación - NSF-07). |
1 January 2016 | RND No. 10-0025-14 | Enactment of the Virtual Invoicing System (Sistema de Facturación Virtual - SFV). |
20 November 2018 | RND No. 101800000026 | Initial publication of the Electronic Invoicing System (Sistema de Facturación Electrónica - SFE), subsequently redesigned. |
11 August 2021 | RND No. 102100000011 | Promulgation of the regulatory baseline governing the SIAT online billing modalities. |
1 December 2021 | RND No. 102100000012 & 17 | Phase 1 go-live: Mandatory compliance for Group 1 taxpayers, including designated large enterprises (PRICOS). |
1 August 2022 | RND No. 102200000002 | Phase 2 go-live: Mandatory online invoicing enforced for Group 2 taxpayers. |
1 April 2023 | RND No. 102200000024 | Phase 3 go-live: Mandatory online invoicing enforced for Group 3 taxpayers. |
1 August 2023 | RND No. 102300000006 | Phase 4 go-live: Mandatory online invoicing enforced for Group 4 taxpayers. |
1 October 2023 | RND No. 102300000019 | Phase 5 go-live: Mandatory online invoicing enforced for Group 5 taxpayers. |
1 March 2024 | RND No. 102300000032 | Phase 6 go-live: Mandatory online invoicing enforced for Group 6 taxpayers. |
1 July 2024 | RND No. 102400000004 | Phase 7 go-live: Mandatory online invoicing enforced for Group 7 taxpayers. |
1 October 2024 | RND No. 102400000013 | Phase 8 go-live: Mandatory online invoicing enforced for Group 8 taxpayers. |
1 April 2026 | RND No. 102500000028 | Interim compliance deadline set for Groups 9, 10, 11, and 12, subsequently postponed. |
1 October 2026 | RND No. 102600000007 | Enforceable deadline for Groups 9, 10, 11, and 12: Mandatory transition to assigned online billing modalities. |
September 2026 | RND No. 102600000034 | Publication of early consultation on technical modifications to the SIAT billing system annex. |
Legal framework
The statutory baseline governing electronic invoicing in Bolivia derives from national fiscal legislation, presidential decrees, and administrative board resolutions issued by the tax administration:
Law No. 2492 (Bolivian Tax Code - Código Tributario Boliviano): Establishes the statutory authority of the National Tax Service to enforce tax compliance, inspect accounting records, mandate billing systems, and penalise illicit tax activities.
Law No. 843 (Tax Reform Law - Ley de Reforma Tributaria): Defines the legal rules for Value Added Tax (Impuesto al Valor Agregado - IVA), invoicing obligations for the sale of goods and provision of services, and the conditions governing fiscal credit (crédito fiscal).
Supreme Decree No. 21530 (VAT Regulations): Outlines executive parameters for tax documentation, invoice validity, and the timing of tax point generation.
Board Resolution RND No. 102100000011: The definitive administrative regulation governing the SIAT online billing system. It establishes the technical definitions, document types, operational modalities, contingency mechanisms, and digital security standards for all electronic tax documents.
Group allocation resolutions (RND No. 102100000012 through RND No. 102600000007): Successive administrative acts that categorise specific taxpayers by Tax Identification Number (Número de Identificación Tributaria - NIT) into mandatory compliance waves.
Board Resolution RND No. 102600000034: Enacts the formal consultation phase for technical revisions to the official SIAT technical annex, governing future data dictionary alignments, schema updates, and security protocols.
Authorities
The administration, technical architecture, and digital certification of the Bolivian e-invoicing model are governed by two principal state entities:
National Tax Service (Servicio de Impuestos Nacionales - SIN)
The Servicio de Impuestos Nacionales is the national tax administration body under the Ministry of Economy and Public Finance (Ministerio de Economía y Finanzas Públicas). SIN is responsible for:
Developing and maintaining the SIAT technical infrastructure.
Classifying taxpayers into specific invoicing modalities and publishing group assignments.
Issuing unique daily authorisation codes (CUFD) and individual system authorisation codes (CUIS).
Validating, clearing, and archiving structured XML documents submitted by taxpayers.
Conducting fiscal audits and imposing penalties for non-compliance.
Agency for the Development of the Information Society in Bolivia (ADSIB)
The Agencia para el Desarrollo de la Sociedad de la Información en Bolivia is the official national digital certification authority under the Vice Presidency of the State. ADSIB is responsible for:
Issuing legally valid digital certificates (certificados digitales) to legal entities and authorised commercial representatives.
Administering cryptographic standards for public key infrastructure (PKI) under Bolivian digital signature legislation.
Guaranteeing the non-repudiation, authenticity, and legal integrity of structured XML invoices issued under the Modalidad Electrónica en Línea.
Scope of the mandate
Bolivia's online invoicing mandate applies comprehensively across commercial sectors, corporate revenue tiers, and transaction classifications.
Which taxpayers must comply?
Compliance is mandatory for all legal entities, public institutions, and natural persons that have been explicitly assigned to an online billing modality by SIN via published Board Resolutions. Taxpayer categorization is determined by corporate turnover, industry complexity, and transaction frequency. Unassigned micro-enterprises and small taxpayers continue to operate under computerised or manual paper billing until formally incorporated into a future group.
Taxpayers must verify their statutory status by entering their NIT into the official SIN modality consultation tool.
Which transactions are covered?
The mandate applies to all economic operations requiring an official fiscal invoice under Bolivian tax law:
Business-to-Business (B2B): Commercial sales of goods, corporate services, raw materials, wholesale operations, and capital investments.
Business-to-Government (B2G): Public procurement supplies, commercial services delivered to state ministries, public works contracts, and state agency provisioning.
Business-to-Consumer (B2C): Point-of-sale retail sales, utilities (electricity, water, telecommunications), hospitality, healthcare, and educational billing.
Sector-specific documents: SIAT enforces specialised XML document schemas for banking and financial services, hydrocarbons, commercial exports, imports, medical services, hotels, leasing, and educational institutions.
Cross-border and export transactions
Export operations are fully integrated within SIAT. Invoices for commercial goods exported outside Bolivia must be issued electronically using the dedicated Commercial Export Invoice schema (Factura Comercial de Exportación), capturing foreign buyer data, tariff codes, and foreign currency values alongside the local equivalent.
E-invoicing requirements
Bolivia's SIAT framework establishes three distinct online invoicing modalities. Taxpayers must configure their billing systems strictly according to the specific modality assigned by the tax administration:
Electrónica en Línea | Computarizada en Línea | Portal Web en Línea |
Custom/Commercial ERP | Custom/Commercial ERP | Direct SIN Web Portal |
XML 1.0 UTF-8 format | XML 1.0 UTF-8 format | Form-based manual input |
ADSIB digital signature mandatory | Software hash-code algorithm | Free of charge |
Automated real-time clearance | Automated real-time clearance | Intended for micro-SMEs |
Technical document generation standards
Invoices generated under the online modalities must satisfy exact structural standards:
Data syntax: Structured XML 1.0, encoded strictly in UTF-8.
Validation schemas: Document payloads must validate against official XSD schemas published by SIN for each respective economic sector.
Unique Authorisation Codes:
CUIS (Código Único de Inicio de Sistemas): System initialisation token issued by SIN to authorise a certified billing application.
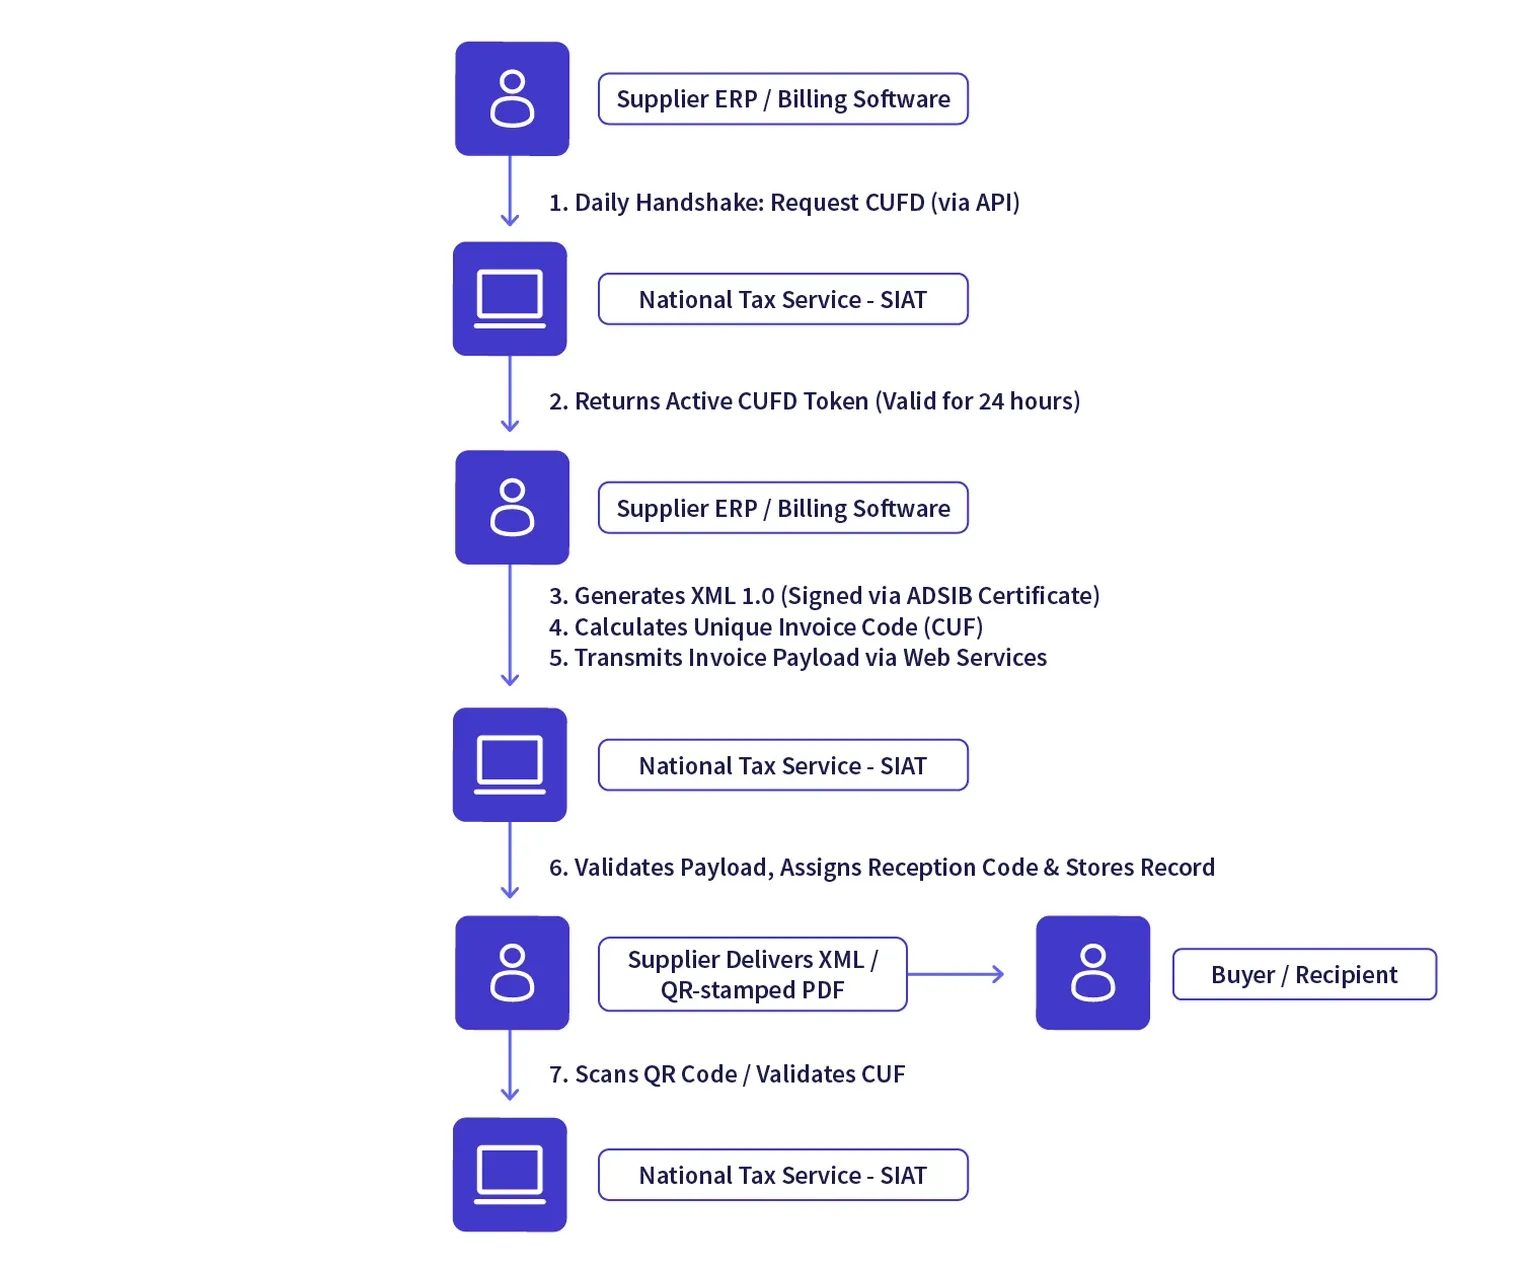
CUFD (Código Único de Facturación Diaria): Daily authorisation code obtained automatically via an API handshake, valid for 24 hours. Invoices cannot be generated without an active CUFD.
CUF (Código Único de Factura): Unique algorithmic string calculated for each invoice, combining the taxpayer's NIT, issuance date, branch office code, document type, and a cryptographic security hash.
Digital signatures: Invoices generated under the Electrónica en Línea modality must be digitally signed using an X.509 v3 digital certificate issued by ADSIB. The signature ensures non-repudiation and content integrity.
Graphical representation & QR codes: When delivering an invoice to a buyer in physical form or via PDF, the document must include a two-dimensional QR code. The QR code encodes transaction totals, the CUF, and security metadata, allowing instant verification on the SIN portal.
E-reporting requirements
In Bolivia, e-reporting is not a retrospective, detached monthly summary; it is integrated directly into the real-time invoice generation lifecycle.
Continuous real-time reporting workflow
Under normal operating conditions, whenever an enterprise billing engine issues an invoice, it transmits the signed XML payload via secure web services directly to the SIAT servers. SIAT executes automated syntax and business rule validations:
SIAT verifies the active validity of the taxpayer's CUIS and daily CUFD.
SIAT inspects the XML payload against the assigned sector XSD schema.
SIAT validates the ADSIB digital signature (for Electrónica en Línea).
SIAT returns an instant electronic reception acknowledgement code (Código de Recepción).
Contingency reporting and package transmissions
Because connectivity outages can occur, Bolivian law establishes strict operational rules for offline contingencies. When communication with SIAT fails due to internet disruption, system maintenance, or local hardware issues, taxpayers are permitted to issue offline invoices using their last valid offline CUFD.
Once normal network connectivity is restored, the taxpayer's billing system must bundle all offline invoices into a compressed contingency package. This package must be digitally signed and transmitted to SIAT within a maximum statutory window of 48 hours. Failure to report offline transaction packages within this 48-hour limit invalidates the underlying documents and triggers statutory non-compliance penalties.
Elimination of detached manual purchase and sales ledgers
Taxpayers operating under online modalities are largely freed from filing traditional, detached manual purchase and sales books (Libro de Compras y Ventas - LCV). Instead, SIAT automatically populates the taxpayer's electronic register (Registro de Compras y Ventas - RCV) based on cleared incoming and outgoing XML documents, enabling automated reconciliation against the monthly Form 200 VAT return.
Technical architecture
The Bolivian e-invoicing architecture is a centralised Continuous Transaction Controls (CTC) clearance model. In this framework, the state tax administration acts as the central clearing hub through which invoice integrity is guaranteed:
System certification process
Commercial enterprises cannot simply connect an off-the-shelf software package to SIAT. Any proprietary ERP, bespoke internal billing engine, or commercial software platform must undergo a rigorous, multi-stage certification process (Proceso de Certificación de Sistemas) within the official SIN testing sandbox.
The certification sequence requires software developers to execute automated test cases across various business scenarios (standard sales, discount allowances, foreign currency transactions, credit notes, and contingency package simulations). Once all automated test scripts pass without error, SIN issues an official Software Certification Certificate, authorising the system to request production CUIS tokens.
Penalties
Bolivian fiscal legislation enforces strict financial and operational sanctions for non-compliance with billing regulations under Law No. 2492 (Bolivian Tax Code) and supplementary administrative resolutions:
Financial fines for formal duties (Incumplimiento a Deberes Formales)
Administrative penalties are calibrated in Housing Development Units (Unidades de Fomento de Vivienda - UFVs), a daily index-linked accounting unit tied to domestic inflation:
Operating an uncertified billing system: Using an uncertified billing application carries fines ranging from 1,500 to 5,000 UFVs, depending on corporate registration size.
Late submission of contingency packages: Failing to upload offline contingency invoice packages within the statutory 48-hour window triggers penalties up to 2,000 UFVs.
Failure to issue invoices under the assigned modality: Continued issuance of computerised or paper invoices after a taxpayer's mandatory group deadline incurs operational penalties and recurring fines.
Loss of fiscal credit (Pérdida del Crédito Fiscal)
The most severe commercial risk in Bolivia is the immediate disqualification of input Value Added Tax deductions. Under Bolivian tax regulations, an invoice issued outside the assigned online modality or lacking an authorised CUF has zero fiscal validity. Commercial buyers cannot utilise the document to offset their output VAT liabilities or substantiate corporate income tax (Impuesto sobre las Utilidades de las Empresas - IUE) expenses. This shifts commercial friction directly to the supplier, resulting in immediate payment withholding and commercial disputes.
Temporary establishment closures
Under Article 164 of Law No. 2492, commercial establishments caught failing to issue valid fiscal invoices for commercial transactions face mandatory physical closure for a minimum of six continuous days, escalating to twelve days for repeat infractions.
How businesses can prepare
Navigating the Bolivian SIAT mandate requires cross-functional alignment across IT, tax, accounting, and supply chain departments:
Verify statutory group allocation immediately: Access the official SIN modality consultation portal and submit your enterprise NIT. Determine whether your organization is mandated under Group 9, 10, 11, or 12 for the upcoming 1 October 2026 enforcement deadline.
Procure ADSIB digital signature certificates: If assigned to the Modalidad Electrónica en Línea, apply immediately for digital signature certificates through ADSIB. Ensure certificates are acquired for authorised legal representatives well ahead of production deployment.
Audit ERP readiness and XSD schema compatibility: Review internal ERP billing engines to confirm they can generate structured XML 1.0 payloads aligned with sector-specific XSD schemas. Ensure your system supports real-time SOAP or REST web service calls to SIAT.
Implement automated CUFD token management: Build automated scheduling routines capable of requesting, caching, and rotating daily CUFD tokens every 24 hours without requiring manual IT intervention.
Configure offline contingency handling: Establish robust local storage mechanisms to capture transactions during network failures. Ensure billing systems automatically trigger compressed, signed contingency package uploads within the mandatory 48-hour recovery window.
Execute rigorous sandbox certification: Complete the formal SIN certification pipeline early. Conduct end-to-end integration tests covering standard sales, voided transactions, sector-specific documents, and credit-debit notes.
Monitor ongoing regulatory updates: Closely observe revisions to the SIAT technical annex introduced under Board Resolution No. 102600000034 to maintain ongoing system compliance.
Conclusion
Bolivia's electronic invoicing framework represents a decisive shift toward modern continuous transaction controls. By combining daily algorithmic authorisations, structured XML payloads, ADSIB digital signatures, and automated tax register population, the National Tax Service has established a highly integrated compliance ecosystem.
With compliance deadlines for Taxpayer Groups 9 through 12 set for 1 October 2026, organizations operating in Bolivia must complete their technical preparations without delay. Businesses that proactively audit their billing architectures, automate daily CUFD management, configure robust contingency workflows, and monitor ongoing updates to the SIAT technical annex will not only secure regulatory compliance but also eliminate invoicing friction and enhance operational efficiency across their South American operations.
FAQ
No. A simple PDF or scanned document possesses no legal validity on its own. The authoritative tax invoice is exclusively the structured XML file validated by SIAT and bearing a valid CUF. A PDF is merely a graphic representation and must include a functional QR code linking to the SIN database.