This article was updated on 21 September 2026 to reflect the latest regulatory directives from the Independent Authority for Public Revenue (AADE) and the Ministry of National Economy and Finance regarding the nationwide rollout of mandatory B2B e-invoicing under Law 5222/2025. It incorporates the operational commencement of Period B on 1 October 2026 for all businesses outside Period A, the transitional adjustment window running until 31 December 2026, the last-minute postponement that rescheduled Period A to 2 March 2026, and updated validation workflows within the myDATA platform.
Introduction & digital tax strategy
Greece is executing one of Southern Europe's most decisive tax administration modernisations, transforming its digital bookkeeping platform into a comprehensive, mandatory Business-to-Business (B2B) electronic invoicing regime. While businesses operating in Greece have reported transactional accounting ledgers electronically since 2021 through the myDATA (my Digital Accounting and Tax Application) platform, the issuance of the commercial invoice itself remained largely unstructured. Under Law 5222/2025, Greece closed this compliance gap, mandating that taxable commercial transactions be issued, transmitted, and validated electronically in structured digital formats.
The strategic objectives behind this reform are clear: closing Greece's historical Value Added Tax (VAT) collection gap, eliminating systemic invoice fraud, automating corporate tax assessments, and establishing parity between commercial trade and digital tax registers. Rather than operating as an isolated domestic mandate, Greece's strategy forms an integral part of wider European digitisation efforts, positioning domestic commercial operators for the upcoming European Union VAT in the Digital Age (ViDA) package.
Following the initial enforcement wave for large corporations under Period A, which went live on 2 March 2026 after a last-minute administrative deferral, the mandate enters its defining stage. From 1 October 2026, Period B extends mandatory B2B structured electronic invoicing to all remaining economic entities across Greece, including small and medium-sized enterprises (SMBs) and sole proprietors. To mitigate operational disruption, tax authorities have established a gradual adjustment period running through 31 December 2026, providing businesses with the necessary runway to stabilise integrations and secure compliance.
Historical evolution and EU context
Greece's transition toward digital tax administration has evolved through distinct legislative phases, progressing from retrospective data reporting to real-time Continuous Transaction Controls (CTCs):
Establishment of Greek Accounting Standards (2014): Law 4308/2014 established the modern legal foundation for Greek commercial bookkeeping, setting out fundamental rules for invoice content, issuance timing, and accounting records (Ελληνικά Λογιστικά Πρότυπα - ELP).
The birth of myDATA (2020 - 2021): Administered by the Independent Authority for Public Revenue (Ανεξάρτητη Αρχή Δημοσίων Εσόδων - AADE), the myDATA platform launched to collect electronic summaries of revenue and expenses. While mandatory transmission commenced on 1 November 2021, myDATA initially functioned as an electronic reporting mechanism rather than a mandatory e-invoicing clearance exchange.
Mandatory B2G electronic invoicing (2023 - 2025): Pursuant to Joint Ministerial Decision 52445 EX 2023, Greece phased in mandatory Business-to-Government (B2G) electronic invoicing under EU Directive 2014/55/EU, requiring public procurement suppliers to transmit structured invoices compliant with the European standard EN 16931 via certified Peppol Access Points. This obligation culminated on 1 September 2025, covering all general government expenditures exceeding €2,500.
EU derogation approval (March 2025): Under Council Implementing Decision (EU) 2025/502, the Council of the European Union granted Greece a formal derogation from Articles 218 and 232 of Directive 2006/112/EC (the EU VAT Directive). This authorised Greece to enforce mandatory domestic B2B e-invoicing and remove the requirement that the invoice recipient must accept the use of electronic invoices, valid from 1 July 2025 to 31 December 2027.
Enactment of Law 5222/2025 (July 2025): The Hellenic Parliament officially passed Law 5222/2025, amending Article 14 of Law 4308/2014 to formally establish structured electronic invoicing as the exclusive statutory mechanism for domestic B2B transactions.
Alignment with ViDA (2026 - 2030): By mandating European-standard structured data files and pre-clearance validation via certified service providers, Greece's domestic framework directly anticipates the EU ViDA Digital Reporting Requirements (DRRs) scheduled to take effect across cross-border Intra-Community transactions from 1 July 2030.
Complete compliance timeline
The nationwide rollout of electronic invoicing and transactional data reporting in Greece follows a strictly regulated calendar:
Date | Target group/transaction scope | Compliance milestone |
1 November 2021 | All Greek VAT-registered businesses | Mandatory phased transmission of revenue data into the myDATA platform begins. |
12 September 2023 | Suppliers to designated public entities | Phase 1 of mandatory B2G electronic invoicing commences for major ministries. |
1 January 2024 | All taxable persons using ERP / billing tools | Mandatory generation of a dynamic QR code linking directly to myDATA on all issued invoices. |
1 September 2025 | All public contracting authorities | B2G e-invoicing becomes fully mandatory across the General Government for all public contracts exceeding €2,500. |
16 September 2025 | National business landscape | AADE publishes the official B2B implementation roadmap establishing Period A and Period B. |
17 February 2026 | Large corporate enterprises | AADE and the Ministry of National Economy and Finance issue an administrative decision rescheduling the Period A commencement from 2 February 2026 to 2 March 2026. |
2 March 2026 | Period A: Large enterprises (2023 gross turnover exceeding €1,000,000) | Mandatory application of B2B e-invoicing commences, accompanied by a graduated adjustment phase running through 3 May 2026. |
3 August 2026 | Period B businesses seeking early adoption | Statutory deadline to submit the Declaration of Commencement and unlock early-adopter tax incentives under Article 71Z of the Income Tax Code. |
1 October 2026 | Period B: All remaining businesses (turnover below €1,000,000, SMBs, sole proprietors) | Mandatory application of B2B e-invoicing commences, initiating the universal coverage of the private commercial sector. |
1 October – 31 December 2026 | Period B businesses | Gradual adjustment period: Parallel operations and progressive system calibration are permitted to allow smooth onboarding before strict financial penalties apply. |
1 January 2027 | Entire Greek commercial sector | Full enforcement of mandatory structured B2B e-invoicing across all commercial entities without transitional leniency. |
1 July 2030 | All cross-border commercial operators | Convergence with EU VAT in the Digital Age (ViDA) digital reporting directives and standardised cross-border e-invoicing. |
Legal framework
The Greek digital compliance framework rests upon primary legislative statutes, European Community decisions, and secondary ministerial decrees:
Council Implementing Decision (EU) 2025/502 (5 March 2025): Authorises the Hellenic Republic to introduce a special measure derogating from Articles 218 and 232 of Directive 2006/112/EC, granting legal authority to mandate electronic invoicing for domestic B2B transactions without requiring buyer consent.
Law 5222/2025 (Government Gazette ΦΕΚ Α΄ 134/28.7.2025): Titled National Customs Code and other provisions – Pension provisions, this statute enacted the domestic mandate. Specifically, it amended Article 14 of Law 4308/2014 (Greek Accounting Standards), establishing that invoice authenticity, integrity, and legibility must be guaranteed exclusively via certified electronic invoicing providers or designated state software applications.
Law 4172/2013 (Income Tax Code), Article 71Z / 71Θ: Codifies statutory tax incentives (φορολογικά κίνητρα) for commercial entities that voluntarily adopt certified electronic invoicing ahead of their legal deadline. Eligible businesses receive a 100% accelerated depreciation rate on hardware and software acquired for e-invoicing implementation in the purchase year, alongside a 100% enhanced tax deductibility on production, transmission, and archival operating expenses during the initial 12 months.
Decision A.1129/2025 of the Governor of AADE: Formally establishes the operational specifications for selecting, registering, and declaring transmission channels. It regulates how taxpayers submit their Declaration of Commencement of Electronic Issuance of Data via a certified provider (YPAES) or the timologio portal.
Law 5104/2024 (Tax Procedure Code): Sets forth the statutory enforcement architecture, audit powers, and financial penalty scales applied by tax authorities for non-issuance, non-transmission, or inaccurate recording of electronic commercial records.
Authorities
The implementation and ongoing administration of the Greek electronic invoicing and reporting framework are governed by three primary bodies:
Independent Authority for Public Revenue (Ανεξάρτητη Αρχή Δημοσίων Εσόδων - AADE): The autonomous national tax authority responsible for administering revenue collection, executing tax audits, publishing technical specifications, licensing certified private providers, and operating the core myDATA digital platform.
Ministry of National Economy and Finance (Υπουργείο Εθνικής Οικονομίας και Οικονομικών): The central government department responsible for national tax policy, sponsoring primary legislation before the Hellenic Parliament, and negotiating derogation instruments with the European Council.
General Secretariat of Information Systems and Digital Governance (Γενική Γραμματεία Πληροφοριακών Συστημάτων και Ψηφιακής Διακυβέρνησης - GSIS): Operates the public IT backbone, manages state interoperability registries, and maintains the central receiving infrastructure for public procurement electronic invoicing across Greek contracting authorities.
Scope of the mandate
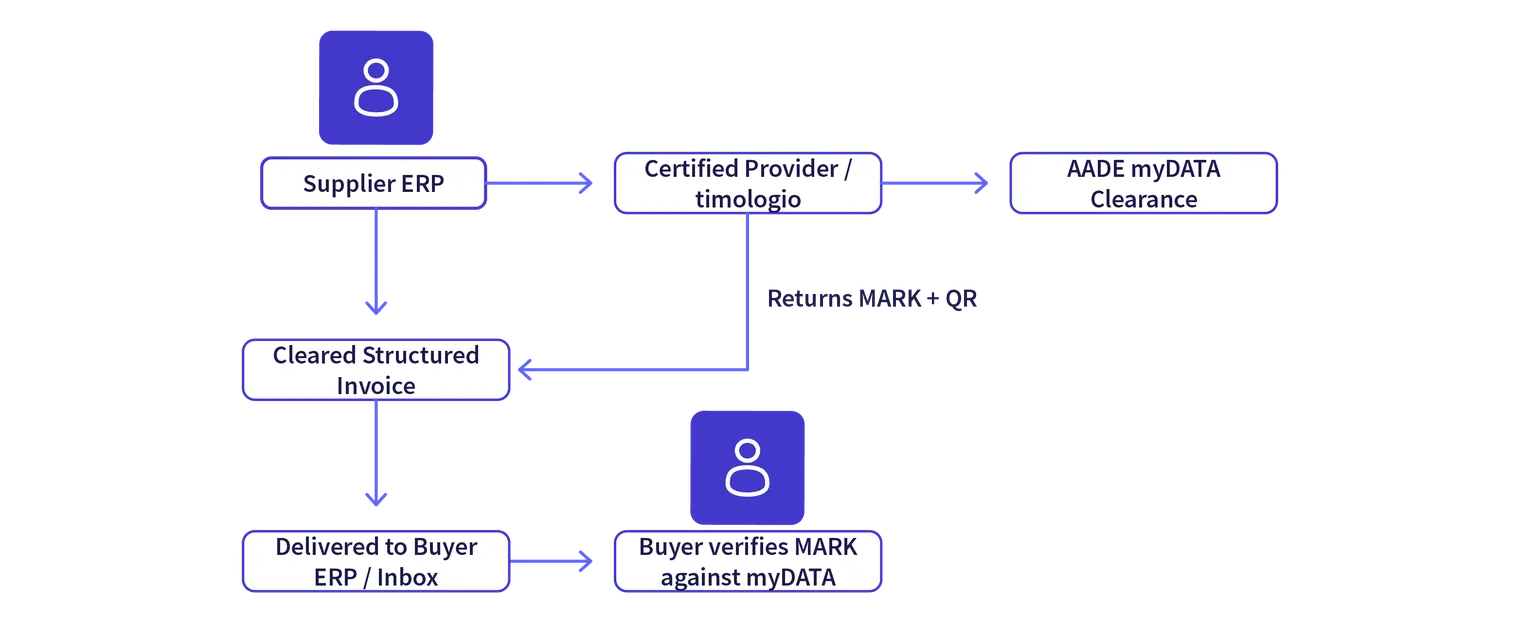
Law 5222/2025 establishes a comprehensive transaction scope, distinguishing between mandatory domestic electronic execution, cross-border reporting rules, and retail fiscalisation:
Who is affected?
The mandate applies universally to all entities that maintain accounting records under Greek Accounting Standards (Law 4308/2014) and are established or registered for VAT in Greece:
Period A entities (active since 2 March 2026): Large businesses whose gross turnover in financial year 2023 exceeded €1,000,000.
Period B entities (active from 1 October 2026): All remaining commercial businesses, SMBs, micro-enterprises, and individual sole traders, subject to the transitional adjustment window through 31 December 2026.
Foreign commercial entities: Non-resident companies operating via a permanent establishment (μόνιμη εγκατάσταση) in Greece must issue compliant electronic invoices for domestic supplies.
Which transactions are in scope?
Domestic B2B supplies: All commercial sales of goods and supplies of services carried out between VAT-registered businesses where the place of supply is Greece. Both the supplier and buyer must process the transaction through the statutory framework.
Sales to third-country businesses (non-EU): Commercial exports and services rendered to business customers established outside the European Union. While foreign non-EU recipients are not obligated to consume the file via Greek channels, the Greek supplier is legally required to issue the invoice as a structured electronic document cleared via the statutory system.
Public sector transactions (B2G): Commercial supplies of goods and services rendered to Greek contracting authorities and public bodies, which must route through certified Peppol access channels.
Transactions outside the direct B2B mandate
Intra-EU cross-border supplies: Invoicing for business customers located within other EU Member States remains optional under domestic rules until the application of EU ViDA directives on 1 July 2030. If the EU counterparty cannot accept a structured e-invoice, alternative formats remain permissible, provided transactional data is reported to myDATA.
Business-to-Consumer (B2C) transactions: Retail sales to natural persons are excluded from the B2B e-invoicing mandate. Instead, retail operations are regulated under Greece's separate fiscal cash register (ΦΗΜ) architecture, requiring interconnected point-of-sale (POS) systems that print receipts bearing a verifiable cryptographic QR code validated against myDATA.
E-invoicing requirements
Under Law 5222/2025, commercial invoices have no legal standing unless issued through an authorised digital issuance channel. Businesses cannot issue unstructured PDF files, word-processing documents, or paper invoices for in-scope B2B transactions.
To achieve legal compliance, invoices must be issued through one of two statutory channels:
1. Certified Electronic Invoicing Service Providers (YPAES)
Commercial enterprises, ERP users, and high-volume billing operations must contract with an accredited private provider (Υπηρεσίες Παρόχου Ηλεκτρονικής Έκδοσης Στοιχείων - YPAES / ΥΠΑΗΣ). These entities are licensed and audited by AADE to ensure technical security, system uptime, and rigorous data validation.
The provider receives the raw billing payload from the enterprise ERP or commercial software.
The provider converts the payload into the European-standard EN 16931 XML format.
The provider clears the invoice with AADE in real time, obtains the unique registration identifier (MARK), embeds the statutory cryptographic QR code, and routes the cleared electronic file to the buyer.
2. Free state applications (timologio and myDATAapp)
To prevent administrative overhead from overwhelming micro-enterprises and individual professionals, AADE provides free web and mobile tools:
Timologio: A free online billing portal operated by AADE designed for small businesses without sophisticated ERP software. Users manually enter customer data, line items, and VAT rates. The platform automatically generates the electronic invoice, registers it within myDATA, generates the MARK, and issues the document.
MyDATAapp: A mobile application designed for tradespeople and mobile professionals, supporting immediate on-site digital invoice generation and real-time validation.
STATUTORY E-INVOICING PILLARS | ||
Structured Data | Unique Registration | Dynamic QR Code |
EN 16931 semantic model (UBL / CII) | Mandatory MARK issued by AADE myDATA engine | Direct hyperlink to AADE verification page |
AADE classification and category codes | Embedded on visual and XML payloads | Instant authenticity audit for counterparties |
Invoice content and technical specifications
Compliant Greek electronic invoices must include standard VAT details (tax identification numbers, sequential numbering, taxable base, applicable VAT percentages) alongside Greek-specific data structures:
The MARK identifier (Μοναδικός Αριθμός Καταχώρισης): A unique numerical reference assigned by myDATA upon successful clearance.
AADE income and expense classification codes: Detailed tax categorisations identifying the specific commercial nature of the revenue (e.g., standard merchandise sales, service provisions, or exempt operations).
Cryptographic QR code: A scannable two-dimensional barcode printed on the visual representation of the invoice, containing an encrypted URL directing the recipient to AADE's public validation portal.
Archival obligations: Electronic invoices and their corresponding myDATA validation tokens must be archived securely in their original structured digital format for a statutory period of 5 years (extended in cases of active tax investigations or unresolved audits).
E-reporting requirements
Greece operates a dual compliance framework where structured electronic invoicing functions in tandem with continuous electronic reporting via myDATA.
While e-invoicing governs the legal issuance and delivery of the billing document between trading counterparties, myDATA acts as the state's digital accounting ledger. The platform maintains two complementary books for every Greek enterprise:
The detailed book (Αναλυτικό Καθολικό): Records the granular line-item breakdown of every issued and received invoice, expense, and credit adjustment.
The summary book (Συνοπτικό Βιβλίο): Aggregates total monthly and annual financial metrics, serving as the benchmark against which statutory tax returns are audited.
Expense matching and pre-filled VAT returns
Under Greek tax regulations, input VAT recovery and corporate income tax deductions are legally restricted: a business cannot claim an expense or recover input VAT unless that transaction has been successfully transmitted to and registered within myDATA.
Furthermore, AADE enforces a zero-tolerance deviation rule between myDATA books and submitted VAT declarations. When submitting quarterly or monthly VAT filings, the figures are pre-populated directly from myDATA. Taxpayers cannot manually override these figures unless formal discrepancy procedures (διαφωνία) are initiated against a non-compliant supplier.
Technical architecture
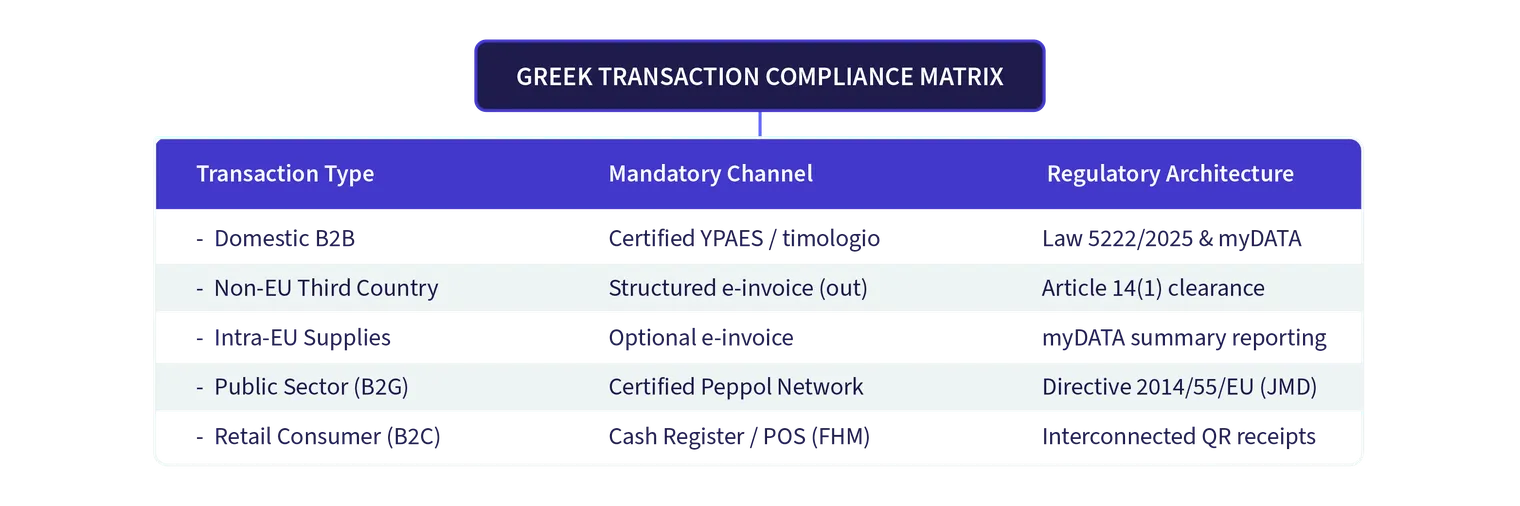
Greece's compliance architecture is structured as a hybrid clearance and continuous transaction control model. Rather than forcing all documents through a single government mailbox, the system separates fiscal validation from commercial delivery while retaining strict state oversight.
The clearance workflow in practice
Invoice generation: The supplier generates invoice data within their accounting software or ERP system, incorporating mandatory Greek classification codes.
Transmission to issuance channel: The payload is routed either to a certified private provider (YPAES) via secure API or manually keyed into timologio.
Real-time clearance with AADE: Before the invoice is delivered to the customer, the issuance channel communicates with AADE's myDATA REST API. The system verifies business registration status, tax calculations, and schema integrity.
Assignment of MARK and QR code: Upon successful validation, AADE returns a unique MARK identifier and an encrypted security token. The issuance engine embeds this data alongside a verifiable QR code onto the final structured document.
Delivery to recipient: The cleared invoice is delivered to the buyer as a structured XML file (or hybrid PDF containing embedded structured XML).
Recipient synchronisation: The buyer's accounting software retrieves the invoice details from their certified provider or synchronises directly with myDATA via API, matching the incoming expense to their digital purchase ledger.
To explore how this architecture compares with international models such as Latin American clearance hubs, the French Y-model, or the Peppol 5-corner model, read our comprehensive analysis on navigating global compliance models.
Penalties for non-compliance
Non-compliance with Greece's electronic invoicing and reporting regulations triggers strict financial and operational sanctions under the Tax Procedure Code (Law 5104/2024):
Statutory monetary fines
Transactions subject to VAT: Failure to issue a compliant structured electronic invoice attracts an administrative fine equal to 50% of the VAT amount associated with the undisclosed transaction.
Transactions exempt from VAT: For commercial operations exempt from VAT or not subject to tax, failure to issue a valid e-invoice incurs a flat fine of €500 per audit for entities using single-entry bookkeeping, and €1,000 per audit for entities maintaining double-entry accounting books.
Repeated offences: Where repeated non-compliance is identified in subsequent tax audits within a five-year period, fines scale progressively to 100% and up to 200% of the underlying VAT amount.
GREEK COMPLIANCE RISK PROFILE | ||
Direct financial fines | Expense disallowance | Operational disruption |
50% to 200% of the underlying VAT amount | Immediate forfeiture of input VAT credits | Mandatory cancellation of invoice validity |
€500 to €1,000 flat fines for VAT-exempt | Disallowance of income tax expense deductions | High-priority tax audit profiling by AADE |
Commercial and operational risks
Loss of input VAT recovery (buyer liability): If a buyer accepts and books an invoice that was not cleared through a certified provider or timologio and lacks a valid MARK identifier, AADE will disallow the input VAT deduction during tax audits, leaving the buyer liable for the tax difference plus surcharges.
Corporate income tax expense disallowance: Unsupported invoices cannot be deducted as legitimate operating expenses for corporate income tax purposes, increasing the net taxable profit of the purchasing business.
Audit escalation: Entities exhibiting systemic discrepancies between issued commercial invoices and myDATA ledger records are automatically flagged by AADE algorithms for comprehensive, on-site tax audits.
How businesses can prepare
The expansion of mandatory B2B electronic invoicing under Period B requires structured preparation across finance, procurement, and technical IT teams. Organisations should implement the following steps:
1. Confirm your compliance deadline and current phase
Verify your commercial status against statutory criteria:
Large enterprises with 2023 gross revenues exceeding €1,000,000 should already be operational under Period A.
All other commercial operators must begin mandatory electronic invoicing under Period B on 1 October 2026, utilising the gradual adjustment window through 31 December 2026 to eliminate integration errors.
2. Choose your statutory transmission pathway
Evaluate your commercial invoice volume and IT infrastructure:
High-volume and ERP users: Contract with an accredited Certified Electronic Invoicing Service Provider (YPAES) capable of integrating directly into your ERP system via API to manage automated XML conversion, MARK acquisition, and QR code placement.
Micro-enterprises and low-volume issuers: Register for AADE's free timologio web portal or download the myDATAapp mobile application.
Submit legal declaration: Submit the mandatory Declaration of Commencement of Electronic Issuance of Data via the AADE portal pursuant to Decision A.1129/2025 before issuing your first e-invoice.
3. Review and clean master data
Clearance engines reject transaction payloads containing invalid tax parameters. Audit customer and supplier files to verify Greek VAT identification numbers (ΑΦΜ), legal trade names, registered business addresses, and contact emails.
4. Implement inbound accounts payable validation
Compliance is an equal responsibility for buyers and sellers. Configure accounts payable workflows to verify that every incoming supplier invoice contains a verifiable MARK identifier and a functional AADE QR code. Establishing automated verification before booking invoices prevents the loss of input VAT credits.
5. Educate finance and accounting personnel
Ensure billing teams and external accountants understand the operational distinction between real-time e-invoicing clearance and periodic myDATA classifications. Provide practical training on managing system exceptions, handling credit notes, and executing dispute declarations (διαφωνία) within statutory timeframes.
Conclusion
The universal implementation of mandatory B2B electronic invoicing marks a defining milestone in the digitalisation of Greece's commercial economy. By combining primary legislation under Law 5222/2025 with real-time clearance mechanics, AADE has established a transparent compliance framework designed to eliminate tax fraud and modernise financial operations.
With Period A already operational for large enterprises and Period B taking effect on 1 October 2026 for all remaining commercial entities, electronic invoicing is no longer optional. Organisations must take full advantage of the transitional adjustment period through 31 December 2026 to evaluate their technical capabilities, select an appropriate transmission route through a certified provider (YPAES) or timologio, and establish robust inbound invoice validation workflows.
Businesses that take a proactive approach to digital compliance will not only safeguard their operations against severe tax penalties and disallowed VAT deductions, but will also gain substantial efficiencies through automated processing, faster transaction cycles, and seamless alignment with upcoming European digital reporting standards under ViDA.
FAQ
No. Standard PDF invoices sent via email, word-processing files, and paper printouts do not meet the legal requirements for domestic B2B transactions covered by Law 5222/2025. In-scope invoices must be generated in a structured electronic format compliant with EN 16931, validated in real time by AADE, and carry an official MARK identifier and QR code.