This article was updated on 5 October 2026 to incorporate the latest updates of the Ministerial Order published in this date (BOE-A-2026-20587), establishing the public e-invoicing solution (SPFE), in addition to the Royal Decree-law 15/2025 regarding VERI*FACTU deadlines (1 January 2027 for corporate taxpayers and 1 July 2027 for sole traders), and the approved Royal Decree under the Crea y Crece Law (BOE-A-2026-7295).
Introduction & digital tax strategy
Spain's digital tax strategy pursues two fundamental policy objectives that run on parallel tracks: combating tax fraud and eradicating commercial delinquency. Fiscal surveillance is the main reason behind SII and VERI*FACTU, driven by the Ministry of Finance (Ministerio de Hacienda) and the Spanish Tax Agency (Agencia Estatal de Administración Tributaria - AEAT).
On the other hand, Law 18/2022 (Ley Crea y Crece), enacted by the Ministry of Economic Affairs and Digital Transformation, includes mandatory business-to-business (B2B) electronic invoicing (amongst other norms to improve business efficiency), not only for fiscal control but primarily as an instrument to ensure commercial transparency, enforce maximum 60-day payment windows under the Late Payment Act (Law 3/2004), and protect the liquidity of small and medium-sized enterprises (SMEs). The legal implementation of the Law (via Royal Decree 238/2026 and the Ministerial Order, expected to be published in October 2026) has been coordinated with the Ministry of Finance and especially with the Spanish Tax Agency, who are implementing the technical systems to support it.
Spain's constitutional structure features special historic charter territories (Territorios Forales) that exercise independent fiscal and taxation autonomy. B2B e-invoicing is applicable across all of Spain, but e-reporting is fragmented: companies and freelancers based in the Basque Country must comply with TicketBAI, while the rest of the territory is obliged to use VERI*FACTU (or SII for large corporates). For business-to-government (B2G) e-invoicing (mandatory since 2015), the national platform, FACe, coexists with Basque Country equivalents (all using Facturae as format).
Spain’s economic network has a high number of SMEs and freelancers (autónomos), often dealing with public bodies, private companies and end consumers, and, consequently, subject to several of the mandates. Understanding how these regional and national business-to-consumer (B2C), B2B and B2G, e-reporting and e-invoicing frameworks interact with each other (and with the European harmonisation initiatives) is essential for any enterprise operating in the Spanish market.
Historical evolution & EU/global context
Spain's transition toward continuous digital compliance has evolved across distinct legislative waves spanning more than a decade:
Public procurement pioneers (2013-2015): Spain introduced mandatory electronic invoicing for public sector transactions exceeding €5,000 on 15 January 2015, establishing the central entry point FACe (Punto General de Entrada de Facturas Electrónicas) and standardising the XML Facturae syntax.
Real-time digital VAT ledgers (SII) (2017): On 1 July 2017, Spain launched the Immediate Supply of Information (Suministro Inmediato de Información - SII). Obligatory for large enterprises (whose prior-year volume of operations exceeded approx. €6 million), taxpayers registered in the Monthly VAT Refund Register (REDEME), and entities within Spanish VAT groups, SII requires the submission of specified invoice-record data within four calendar days of issuance or receipt.
Basque Country decentralisation (TicketBAI) (2020-2024): Between 2020 and 2024, the Basque Foral Treasuries developed and phased in TicketBAI, requiring compliant invoicing software, electronic signature chaining and QR code generation for every point-of-sale and B2B invoice, independent of central state regulations.
Anti-fraud invoicing-software controls (2021): Enacted on 9 July 2021, Spain outlawed dual-use software (software de doble uso) that permits the concealment, alteration or manipulation of records. This laid the foundation for the Computerised Invoicing Systems Regulation (Reglamento de Sistemas Informáticos de Facturación - RRSIF), commonly known as VERI*FACTU, which aims to ensure invoice-record integrity and traceability.
Private-sector B2B e-invoicing mandate (2022): In September 2022, Spain established the policy basis for mandating electronic invoicing between all private businesses and freelancers, to reduce late payments and foster enterprise growth.
Invoicing-software integrity controls (VERI*FACTU) (2025): In late 2025, Spain postponed the VERI*FACTU implementation timetable until 2027, allowing businesses additional time to adapt their invoicing software to the integrity, traceability and record-standardisation requirements. Companies subject to corporate income tax must generally comply from 1 January 2027; other affected taxpayers generally follow from 1 July 2027.
B2B operating model and technical rules (2026): In March 2026, Spain established the operating framework for mandatory B2B electronic invoicing between businesses and professionals. The framework addresses private exchange platforms, the public e-invoicing solution, invoice-status communications and the submission of faithful copies of privately exchanged invoices to the tax authorities. A draft technical order issued for consultation in April 2026 proposed UBL as the exclusive syntax for invoices exchanged through the public solution.
Senate motion on European ViDA alignment (June 2026): On 17 June 2026, the Spanish Senate approved a motion urging the government to evaluate how VERI*FACTU, SII, and the Crea y Crece B2B e-invoicing mandate converge into a unified model compatible with the EU's VAT in the Digital Age (ViDA) package. With ViDA introducing mandatory Digital Reporting Requirements (DRR) for intra-Community supplies from July 2030 and harmonising domestic reporting from January 2035, Spanish business associations and lawmakers seek to prevent duplicate reporting burdens. According to our local experts, this motion is not binding, and so its impact might be limited.
B2B e-invoicing technical rules (2026): On October 5th, 2026, the Ministerial Order, confirming the technical rules (including detailed requirements for UBL 2.5 messages), was published. This milestone starts the count of 12 months for the B2B e-invoicing under the Ley Crea y Crece to be mandatory (24 months for enterprises with turnover < €8 million).
Complete compliance timeline
The Spanish digital compliance rollout follows distinct statutory deadlines depending on the legislative mandate, business size, and regional jurisdiction:
Date | Legal mandate | Business Category | Compliance obligation |
15 January 2015 | B2G e-invoicing (FACe) | Suppliers to the public sector | Mandatory B2G e-invoicing via FACe for invoices over €5,000 using Facturae. |
1 July 2017 | SII | Large businesses (>€6M), REDEME, VAT groups | Mandatory submission of invoice data to SII within 4 calendar days. |
1 January 2022 - 2024 | TicketBAI | All businesses & freelancers in Basque Country (Gipuzkoa, Álava, & Bizkaia) | Phased entry of TicketBAI (complete coverage achieved). |
1 January 2027 | VERI*FACTU | Corporate Income Tax payers (IS) | Mandatory implementation of certified VERI*FACTU billing software. |
1 July 2027 | VERI*FACTU | Sole traders & freelancers (IRPF) | Mandatory implementation of certified VERI*FACTU billing software. |
6 October 2027 | B2B e-invoicing (Ley Crea y Crece) | Enterprises and professionals with turnover > €8 million | Mandatory issuance, receipt, and status reporting of B2B electronic invoices. |
6 October 2028 | B2B e-invoicing (Ley Crea y Crece) | Enterprises and professionals with turnover < €8 million | Mandatory issuance and receipt of B2B electronic invoices. |
6 October 2029 | B2B e-invoicing (Ley Crea y Crece) | Professionals under IRPF with turnover < €8 million | Status reporting. |
1 July 2030 | EU ViDA | All EU cross-border operators | Mandatory e-invoicing and 10-day Digital Reporting Requirements (DRR). |
Legal framework
Spain's electronic invoicing and tax reporting governance is codified in distinct statutes, royal decrees, and ministerial orders:
Law 25/2013, of 27 December 2013 (public-sector e-invoicing): Published in BOE No. 311 of 28 December 2013, it governs public sector electronic invoicing and created the Accounting Register of Invoices (Registro Contable de Facturas, RCF).
Royal Decree 596/2016, of 2 December 2016 (SII VAT-record reporting): Published in BOE No. 294, 6 December 2016, regulating the Immediate Supply of Information (SII) system for near-real-time electronic submission of VAT invoice-record data.
Law 11/2021, of 9 July 2021 (anti-fraud invoicing-software controls): Published in BOE No. 164, 10 July 2021, amending the General Tax Law (Law 58/2003) to mandate integrity and non-manipulation safeguards in billing systems.
Law 18/2022, of 28 September 2022 (Ley Crea y Crece, B2B e-invoicing mandate): Published in BOE No. 234, 29 September 2022, amending Law 56/2007 on Measures to Promote the Information Society, it establishes mandatory electronic invoicing between businesses and self-employed professionals.
Royal Decree 1007/2023, of 5 December 2023 (Computerised Invoicing Systems Regulation RRSIF / VERI*FACTU): Published in BOE No. 291, 6 December 2023, establishing technical and functional specifications for computerised billing systems and verifiable records.
Ministerial Order HAC/1177/2024, of 17 October 2024 (VERI*FACTU technical specifications): Published in BOE No. 260, 28 October 2024, defining detailed technical validation rules, hash algorithms, QR codes, and transmission schemas for VERI*FACTU.
Royal Decree-law 15/2025, of 2 December 2025 (VERIFACTU implementation deferral): Published in BOE-A-2025-24446, it amends previous implementation dates, formally deferring VERI*FACTU obligations to 2027.
Royal Decree 238/2026, of 24 March 2026 (B2B e-invoicing operating framework): Published in BOE-A-2026-7295, it approves the regulation implementing the electronic invoicing requirements between enterprises and professionals under Law 18/2022.
Ministerial Order HAC/1028/2026 on the Public E-Invoicing Solution (technical rules for the SPFE): Published in BOE-A-2026-20587 on 5 October 2026. It regulates the technical operations, security architecture, and data dictionary of the Public Electronic Invoicing Solution (Solución Pública de Facturación Electrónica - SPFE).
Regulatory & tax authorities
Several administrative and technical entities support and oversee the Spanish digital tax framework:
State Tax Administration Agency (AEAT): The national revenue service responsible for administering SII, reviewing VERI*FACTU submissions in common fiscal territory, managing developer testing sandboxes, and maintaining the technical infrastructure of the public e-invoicing platform (SPFE).
Foral Treasuries (Diputaciones Forales): The historical provinces of the Basque Country (Álava, Bizkaia, and Gipuzkoa) possess autonomous fiscal sovereignty governed by the Economic Agreement (Concierto Económico). Each Foral Treasury (Hacienda Foral) enacts its own tax legislation and administers TicketBAI and regional corporate taxes. Navarra also operates with independent fiscal sovereignty, but they are not subject to TicketBAI, and, to date, they have not issued any e-reporting mandate. Basque Country and Navarra are subject to the rules of e-invoicing under Ley Crea y Crece.
Tax Administrations in territories with special tax regime: Canary Islands, Ceuta and Melilla do not possess fiscal sovereignty but operate under non-EU VAT regimes, with separate Tax Administrations. IGIC (Canary Islands) and IPSI (Ceuta y Melilla) are the equivalents to VAT for these territories. For legal entities located in these territories, there are some differences in the tax reporting (including SII), as they have to be reported to local Tax Administrations instead of to the AEAT. For the rest of e-invoicing and e-reporting obligations (namely VERI*FACTU and Ley Crea y Crece), the national rules fully apply.
Scope of the mandates
While nationwide mandates like Ley Crea y Crece and VERI*FACTU apply generally across Spain, the country's decentralised structure includes distinct regional frameworks. Most notably, the Basque Country operates its own independent transaction control system (TicketBAI), which exempts local businesses from national e-reporting while still requiring adherence to nationwide B2B e-invoicing standards.
It is important to understand that digital compliance in Spain covers domestic B2B, B2G, and B2C transactions across distinct, concurrent legal regimes.
Spanish invoicing operations | ||
B2G transactions (Law 25/2013 - FACe) | B2B transactions (Law 18/2022 - B2B) | B2C transactions (Law 11/2021 & Foral) |
|
|
|
Business-to-Government (B2G)
Regulated under Law 25/2013, mandatory e-invoicing applies to all public administrations (national, regional, and municipal). Suppliers must issue structured invoices using the Facturae schema for any transaction exceeding €5,000 (though public bodies may mandate e-invoicing for amounts below this threshold). Invoices must include specific administrative directory codes (DIR3 codes) representing the accounting office, competent body, and processing unit.
B2G transactions are also subject to anti-fraud reporting obligations: SII, VERI*FACTU or TicketBAI depending on the type of business and the location.
Business-to-Business (B2B)
Under Law 18/2022 (Ley Crea y Crece) , Royal Decree 238/2026 and Ministerial Order HAC/1028/2026, all domestic B2B transactions between Spanish businesses, permanent establishments, and self-employed professionals must be documented via structured electronic invoices. Public companies and Temporary Business Associations (Uniones Temporales de Empresas - UTEs) fall within scope.
The mandate applies to domestic supplies. Cross-border B2B transactions remain outside the immediate scope of Crea y Crece, continuing under general VAT rules until the EU ViDA cross-border Digital Reporting Requirements (DRR) take effect in July 2030.
B2B transactions are also subject to anti-fraud reporting obligations: SII, VERI*FACTU or TicketBAI depending on the type of business and the location.
Business-to-Consumer (B2C)
Consumer transactions are expressly excluded from the Crea y Crece B2B e-invoicing mandate. However, retail transactions and simplified invoices (facturas simplificadas) fall squarely under anti-fraud billing software rules (VERI*FACTU) in common territory and under TicketBAI across the Basque Country. These frameworks require fiscal data generation, digital chaining, and QR code printing for consumer-facing receipts.
Spain's B2B e-invoicing requirements (Ley Crea y Crece)
The B2B electronic invoicing framework introduces structural obligations governing technical syntaxes, authentication, and continuous status tracking.
Mandatory syntaxes and technical formats
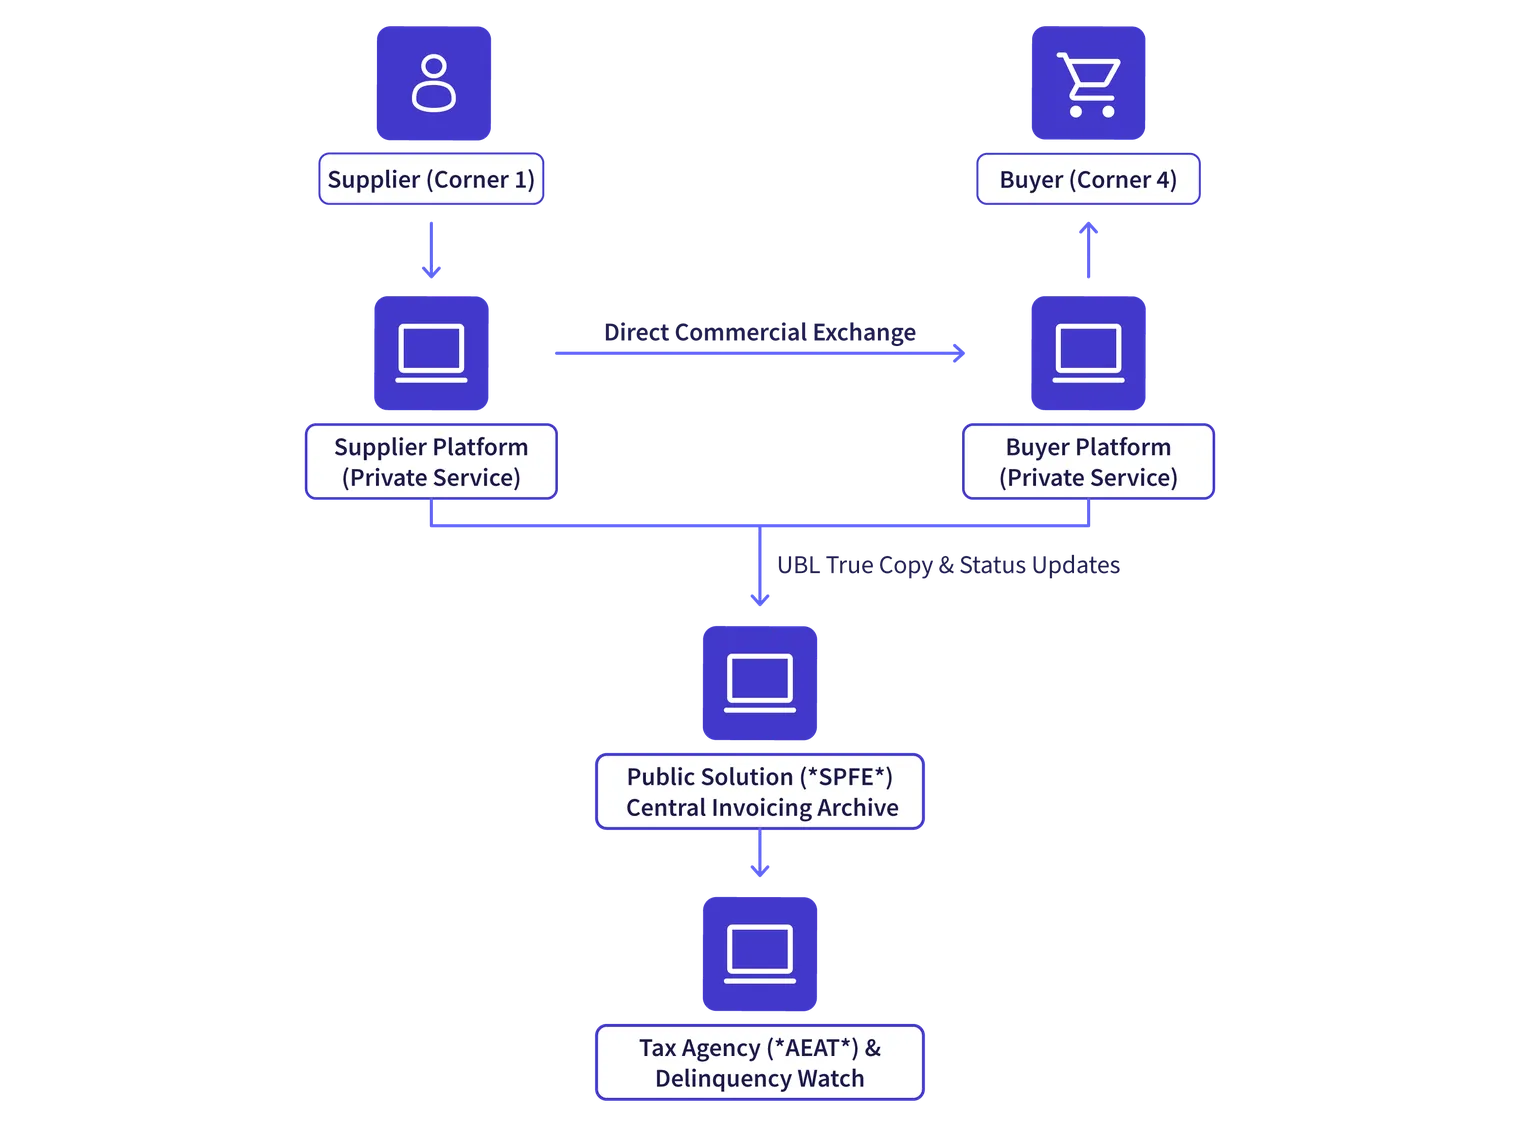
Under Royal Decree 238/2026, which develops the B2B e-invoicing operating framework, an electronic invoice is legally defined as a structured computer file meeting European standard EN 16931. The following Ministerial Order specifies that the Public Electronic Invoicing Solution (SPFE) uses Universal Business Language (UBL) syntax, aligned with the applicable EN 16931 standard.
Businesses using private exchange platforms may agree to exchange structured invoices in one of the formats permitted by Spain’s B2B e-invoicing framework:
Universal Business Language (UBL 2.5): Structured XML syntax compliant with EN 16931. Under the current draft technical rules, it is mandatory for all transmissions to the public solution (SPFE).
Cross Industry Invoice (CII): UN/CEFACT XML schema compliant with EN 16931.
Facturae (v3.2.x): The Spanish national XML syntax, historically used for B2G invoicing via FACe.
EDIFACT: A long-established electronic-data-interchange format widely utilised across retail, automotive, and fast-moving consumer goods sectors.
Where private platforms utilise formats other than UBL (such as EDIFACT or Facturae), the software must automatically convert and deposit an identical true copy (copia fiel) to the public platform (SPFE) in structured UBL 2.5 format at the time the invoice is issued. This true copy must preserve the substantive content of the invoice exchanged between the parties.
Electronic signatures and authentication
All electronic invoices issued outside the public portal must be authenticated using an advanced electronic signature, based on a qualified certificate for either electronic signatures or electronic seals, in each case in accordance with the European eIDAS Regulation (EU 910/2014). Taxpayers may delegate signature issuance to certified electronic invoicing service providers.
Every invoice must contain a Unique Invoice Identifier (UUID), calculated systematically from the issuer's tax identification number (NIF), invoice series and number, and issue date.
Mandatory invoice lifecycle tracking
A distinctive feature of the Spanish future B2B e-invoicing framework is the mandatory communication of invoice lifecycle statuses. To eliminate abusive commercial payment delays, Law 18/2022 requires recipients of electronic invoices to record and report transaction milestones within four calendar days (excluding national weekends and public holidays). The required milestones are:
Commercial acceptance or rejection: The buyer must record formal commercial acceptance or rejection of the invoice, including the exact date on which the event occurred.
Full effective payment: The buyer must report full payment of every received invoice that has not been rejected, together with the date on which payment was cleared. This is the date on which the supplier receives payment, not the date on which the payment instruction was merely dispatched or authorised.
These status updates must be transmitted back to the supplier electronically via the exchange arrangement used and communicated to the public platform (SPFE). The framework also permits voluntary reporting of commercial acceptance or rejection, payment including the amount paid and payment date, and assignment of the invoice to a third-party for collection or payment. These optional statuses do not alter the statutory calculation of the invoice payment period.
Large enterprises with turnover exceeding €8 million must comply with status reporting immediately from the date their B2B e-invoicing obligation becomes effective, whereas smaller businesses benefit from a transitional period: they are not required to communicate the mandatory invoice-status information until 36 months after the Ministerial Order enters into force.
Visual PDF transition rules
During the initial phased rollout, structured electronic invoices must be accompanied by an easily readable PDF rendering to guarantee legibility for trading partners whose mandatory receipt obligations have not yet entered into force. Once all enterprises and freelancers are incorporated into the mandate, structured data files become the sole authoritative legal instrument.
Archival obligations
Under Article 30 of the Spanish Commercial Code (Código de Comercio) and the General Tax Law, electronic invoices, cryptographic signatures, and status certificates must be preserved for a minimum statutory period of six years (or up to ten years for auditing transactions involving capital assets or complex deductions). Archival systems must ensure continuous authenticity, integrity, and accessibility.
Technical architecture: Hybrid exchange and clearance
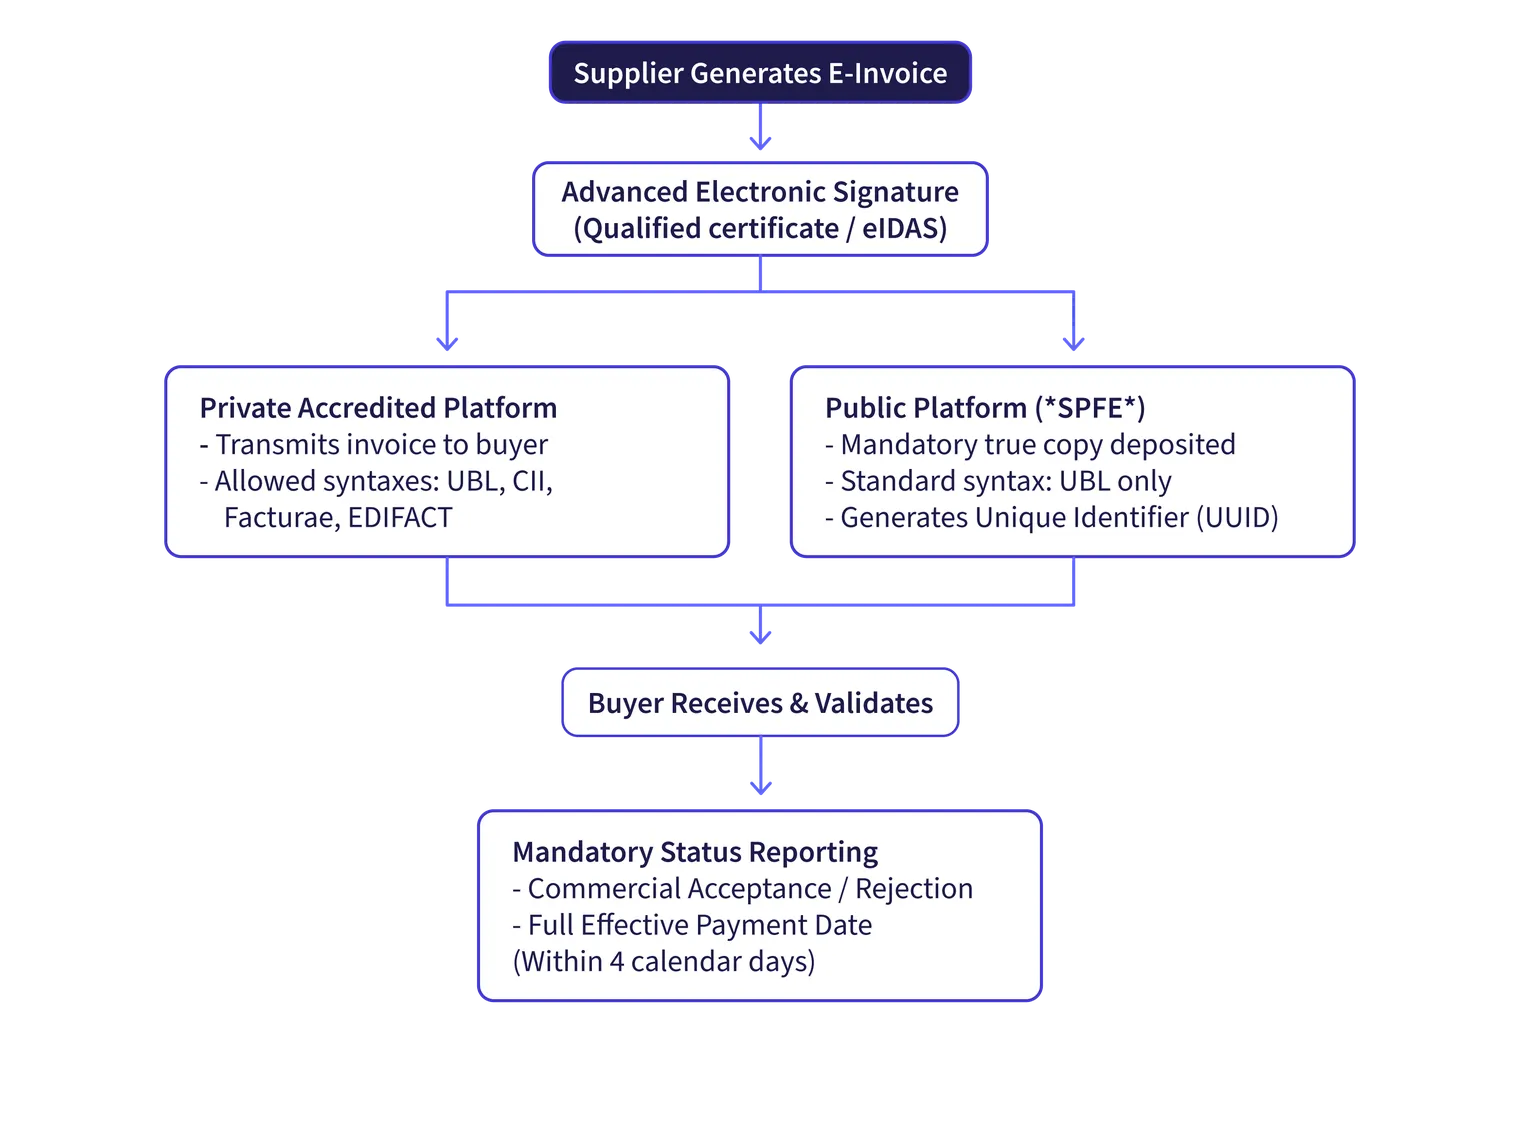
Spain has rejected both the centralised clearance model, such as the one used in Italy (where all invoices pass through a single clearance hub), and the purely decentralised peer-to-peer approach, like Belgium. Instead, Spain operates a hybrid decentralised CTC model, combining private e-invoicing platforms with a centralised public repository.
Core architectural elements
Supplier (Corner 1): Generates an EN 16931-compliant structured invoice within an internal ERP or billing application.
Private e-invoicing service providers (Corner 2 & Corner 3): Private technology platforms handle direct point-to-point commercial transmission between trading partners via AS2, AS4, or secure SFTP protocols. These platforms must maintain ISO/IEC 27001 information security certification, guarantee full interoperability free of interconnection surcharges, support advanced electronic signatures, and translate alternative syntax formats into UBL.
Public Electronic Invoicing Solution (SPFE - Corner 5): Managed by the AEAT, the SPFE does not clear invoices before transmission. Instead, it acts as a central repository and directory. Whenever an invoice is issued via a private platform, the supplier's platform must transmit a faithful copy in structured UBL syntax to the SPFE. Smaller enterprises may also use the SPFE web interface directly to generate and deliver invoices free of charge.
Buyer (Corner 4): Ingests the structured invoice directly into accounts payable software, records receipt, and dispatches mandatory lifecycle status updates.
This hybrid structure ensures that business operations continue unhindered by potential public platform latency, while providing public authorities with complete transaction data to monitor payment durations.
Spain's e-reporting requirements (SII and VERI*FACTU)
Spain operates two separate transactional tax reporting frameworks alongside B2B commercial invoicing:
Spain’s e-reporting landscape | |
Suministro Inmediato de Información (SII) | VERI*FACTU (Computerised Billing Systems) |
|
|
The “Immediate Supply of Information” (SII)
The Suministro Inmediato de Información (SII) - mandatory for large enterprises with a prior-year turnover exceeding approx. €6 million, participants in the Monthly VAT Refund Register (*REDEME*), and entities within Spanish VAT groups - requires these approximately 62,000 taxpayers to submit electronic VAT ledger records to the AEAT web portal via SOAP/XML web services. The system requires transmission within four calendar days of invoice issuance (for issued invoices) or accounting registration (for received invoices).
Reporting to the SII does not constitute electronic invoicing; it is a live tax reporting regime. The advent of mandatory B2B e-invoicing under Crea y Crece does not dismantle the SII. Companies subject to SII must continue submitting VAT ledgers while adopting structured e-invoicing for commercial document exchange.
The VERI*FACTU regime
VERI*FACTU governs the software systems used by enterprises and freelancers to produce invoices. Enacted to eliminate unaccounted cash transactions and sales suppression software, VERI*FACTU mandates that billing engines must generate a standardised billing record (registro de facturación) at the exact moment an invoice is generated.
Under Ministerial Order HAC/1177/2024, the detailed technical and functional specifications for the VERI*FACTU regime, software developers and users must choose between two operating modes:
Verifiable billing system (Sistema de emisión de facturas verificables - VERI*FACTU): The software automatically and continuously transmits encrypted billing records to the AEAT in real time via a secure API. The invoice prominently displays the mark "Factura verificable en la sede electrónica de la AEAT" alongside a dynamic QR code.
Non-verifiable billing system (Non-VERI*FACTU): The software does not transmit records automatically. Instead, it must store records internally inside an immutable, cryptographically chained event logbook signed with a digital certificate, subject to inspection on demand.
Invoices generated through the Crea y Crece public platform automatically fulfil VERI*FACTU requirements. Royal Decree-law 15/2025 postponed VERI*FACTU enforcement to 1 January 2027 for corporate taxpayers and 1 July 2027 for individual freelancers.
Basque Country: TicketBAI
The Basque Country exercises fiscal independence through the three Foral Treasuries of Álava, Bizkaia, and Gipuzkoa. These territories developed and deployed their own continuous transaction control system, known as TicketBAI, prior to the enactment of central state billing initiatives.
TicketBAI applies to all natural and legal persons carrying out economic activities in the Basque Country, covering B2B, B2G, and B2C transactions. Every billing software system must generate an unalterable, signed XML file for each invoice, incorporate a unique cryptographic signature, chain the invoice mathematically to the preceding transaction, and print a compliant TicketBAI identification code (TBAI) and QR code on the invoice output.
While the technical TicketBAI engine is common across the three provinces, its operational execution varies:
Gipuzkoa: Operates TicketBAI as a direct electronic reporting system to the Foral Treasury (Diputación Foral de Gipuzkoa). Fully deployed across all economic sectors.
Álava: Operates TicketBAI via the Diputación Foral de Álava, with phased deployment fully complete.
Bizkaia (Batuz): Bizkaia embedded TicketBAI into a comprehensive digital tax ecosystem known as Batuz, which includes other tax reporting obligations.
Basque businesses subject to TicketBAI are legally exempt from the central AEAT's VERI*FACTU requirements, as their provincial obligations impose equivalent fiscal safeguards. However, Basque businesses must still comply with nationwide B2B commercial e-invoicing under Ley Crea y Crece when transacting across Spain.
B2G e-invoicing regime: FACe
The landscape wouldn’t be complete without a mention of FACe (B2G e-invoicing), the first e-invoicing mandate issued in Spain.
Governed by Law 25/2013 on public sector e-invoicing and mandatory since 2015, Spain’s Business-to-Government (B2G) regime mandates electronic invoicing for suppliers delivering goods or services to public sector entities, including central, regional, and local administrations.
Submissions are managed through FACe (Punto General de Entrada de Facturas Electrónicas), the central government general entry point, or compatible regional hubs. Core technical requirements include:
Standardised syntax: Invoices must be generated in the national XML-based Facturae schema (versions 3.2.x).
Administrative routing (DIR3): Submissions require mandatory DIR3 identification codes specifying the Accounting Office (Oficina Contable), Managing Centre (Órgano Gestor), and Processing Unit (Unidad Tramitadora).
Digital Security: Every invoice must bear an advanced electronic signature (XAdES format) using a qualified digital certificate to guarantee origin authenticity and content integrity.
Lifecycle Tracking: Vendors can monitor invoice processing statuses (Submitted, Registered, Approved, Paid) in real time via a web interface or integrated web services APIs.
While the national baseline sets a €5,000 exemption threshold, the vast majority of public bodies require FACe submission for all invoice amounts regardless of value.
Although there are voices suggesting that it will merge with Ley Crea y Crece, the most probable scenario is that FACe will co-exist with B2B e-invoicing, and also with e-reporting obligations, for some years.
Penalties for non-compliance
Non-compliance across Spain's multi-layered invoicing landscape carries severe commercial, operational, and financial sanctions across separate legal statutes:
Statutory section regimes in Spain | |
Ley Crea y Crece (Law 18/2022) | Ley Anti-Fraude (LGT Article 201 bis) |
|
|
Sanctions under Ley Crea y Crece
Operational non-compliance: Businesses that refuse to issue structured electronic invoices, fail to grant clients access to e-invoices, or obstruct access to invoices for the statutory duration face administrative fines of up to €10,000 issued by the Ministry of Economic Affairs.
Commercial delinquency sanctions: Companies that breach the statutory 60-day payment threshold under the Late Payment Act (Law 3/2004) face severe non-financial penalties:
Exclusion from public procurement contracts under the Public Sector Contracts Law (LCSP).
Ineligibility to receive official public subsidies and grants, including European Union recovery funds (such as the Kit Digital programme).
Public listing on the State Delinquency Watchdog (Observatorio Estatal de la Morosidad Privada), which publishes an annual list of late-paying entities whose overdue commercial liabilities exceed €600,000 and represent more than 5% of total payables.
Sanctions under the Anti-Fraud Law (LGT Article 201 bis)
Use of non-compliant billing software: Enterprises caught utilising uncertified, non-verifiable, or dual-use software systems that fail to comply with VERI*FACTU requirements face fixed financial penalties of €50,000 per financial year.
Developer and distributor liability: Software vendors that market, license, or distribute non-compliant billing software face penalties of up to €150,000 per fiscal year, or €1,000 per unlicensed software package distributed.
How businesses can prepare
Navigating Spain's multifaceted digital compliance obligations requires a structured, proactive preparation programme:
Audit regional exposure: Determine whether your business operations, subsidiaries, or suppliers fall under common fiscal territory (AEAT) or under regional jurisdictions.
Evaluate billing systems against VERI*FACTU: Verify that ERP and invoicing platforms comply with Royal Decree 1007/2023 and Order HAC/1177/2024. Confirm whether your systems will connect directly via the automated VERI*FACTU web service or maintain local encrypted logbooks ahead of the 2027 deadlines.
Implement UBL 2.5 syntax generation: Although private transactions accept Facturae or EDIFACT, ensure your software or service provider can generate and transmit true copies in standard UBL format to the public SPFE repository.
Establish 4-day status reporting workflows: Review accounts payable procedures to automate commercial acceptance notifications and capture the exact date of bank payment clearance, ensuring transmission within the four-calendar-day statutory limit.
Enforce master data cleanliness: Validate client and vendor tax identification numbers (NIF), corporate addresses, and administrative DIR3 routing codes across customer records.
Select an accredited private service provider: Partner with a compliance provider operating certified infrastructure (ISO/IEC 27001), automated status transmission, and multi-format translation capabilities. Explore Banqup compliance management solutions to future-proof your Spanish and European operations.
Conclusion
E-invoicing and e-reporting mandates starting in 2027 (VERI*FACTU, Ley Crea y Crece) represent a major shift in digital transformation in Spain. By replacing paper documents with structured electronic formats, mandatory lifecycle tracking, and automated e-reporting, the Spanish Government is establishing a modern, transparent VAT system to combat tax fraud and eradicate commercial delinquency.
The go-live schedule of these mandates will expand over 2027, 2028 and 2029, depending on the type of business and its size, and will co-exist with previous systems: B2G (FACe), e-reporting (SII) and regional platforms (TicketBAI). However, Spanish organisations should evaluate their systems now. Selecting an accredited platform partner, auditing master data, integrating banking and payments systems and establishing compliant accounts payable and receivable workflows will ensure a smooth transition and ongoing tax compliance.
FAQ
The short answer is no. Once an enterprise's mandatory implementation wave enters into force, a plain PDF sent via email does not qualify as a valid electronic invoice for domestic B2B transactions. Invoices must be structured, machine-readable data files (such as UBL or Facturae) accompanied by advanced digital signatures. A human-readable PDF is only permitted as a temporary visual aid during the initial rollout.