This article was updated on 21 September 2026 to reflect the nationwide expansion of Uganda's Electronic Fiscal Receipting and Invoicing Solution (EFRIS) administered by the Uganda Revenue Authority (URA). This update incorporates the mandatory onboarding of 12 commercial sectors irrespective of VAT registration status under General Notice No. 2218, income tax expense disallowance rules under the Tax Procedures Code Act, system-to-system API specifications, and East African Community cross-border alignment.
Introduction & digital tax strategy
The Republic of Uganda operates one of East Africa's most comprehensive Continuous Transaction Controls (CTC) regimes through the Electronic Fiscal Receipting and Invoicing Solution (EFRIS). Administered by the Uganda Revenue Authority (URA), the system requires commercial operators to record business transactions digitally and transmit fiscal data to the central tax authority in real time.
Uganda's digital tax strategy is designed to mobilise domestic revenues, curtail Value Added Tax (VAT) avoidance, eliminate fictitious invoice trading, and integrate informal retail distribution into the formal fiscal register. Rather than relying on periodic post-audit reviews or annual tax declarations, the government enforces immediate transaction oversight at the point of exchange.
Unlike decentralised regimes where invoice routing remains entirely between private intermediaries, the URA maintains a centralised clearance and fiscal validation platform. Every transaction must be authenticated by the revenue authority before a final invoice or receipt is issued to the buyer. Under this architecture, an invoice carries no legal validity for tax deduction or input credit recovery unless it bears an encrypted Fiscal Document Number (FDN), a verification code, and a machine-readable QR code.
The scope of Uganda's digital regime has widened substantially beyond traditional VAT taxpayers. Following the enforcement of official gazetted notices expanding compliance to twelve specific economic sectors, digital fiscalisation now governs a broad range of enterprise and medium-sized operations. Understanding these requirements is essential for domestic traders, multinational corporations, and software vendors operating across East Africa.
Historical evolution & regional context
Uganda's transition to continuous digital taxation began with the enactment of the Tax Procedures Code (Amendment) Act 2018, which inserted statutory provisions empowering the Minister of Finance and the Commissioner General to mandate electronic receipting and invoicing devices.
The path from pilot to universal VAT enforcement
The technical implementation of EFRIS formally commenced in 2020 under the Tax Procedures Code (Electronic Fiscal Receipting and Invoicing) Regulations 2020. While an initial pilot was scheduled for mid-2020, administrative challenges and commercial readiness prompted the URA to defer full statutory enforcement to 1 January 2021. From that date, all taxpayers registered for VAT in Uganda were legally obligated to onboard onto EFRIS to validate sales and purchase ledgers.
The 12-sector expansion
Recognising that large segments of taxable commerce remained outside the standard VAT threshold of UGX 150 million, the Ministry of Finance, Planning and Economic Development and the URA broadened the operational net. Under General Notice No. 2218, the government expanded the mandatory use of EFRIS to twelve designated commercial sectors, effective from 1 July 2025. Crucially, businesses operating within these designated sectors are obligated to issue EFRIS electronic invoices and receipts regardless of whether they meet the annual VAT registration threshold.
Regional economic alignment: East African Community (EAC)
Uganda's digital tax framework forms an integral component of the East African Community (EAC) digital harmonisation agenda. Operating alongside regional peers such as Kenya (with its software-based eTIMS platform), Rwanda (Electronic Billing Machines - EBM v2), and Tanzania (EFDMS / VFD), Uganda participates in the EAC Single Customs Territory.
While the EAC has not yet enacted a unified supranational digital tax directive akin to the European Union's VAT in the Digital Age (ViDA) initiative, the technical architectures across East Africa are converging toward cloud-connected REST APIs, standardised JSON/XML payloads, and automated input VAT cross-matching. Furthermore, the commercial protocols established under the African Continental Free Trade Area (AfCFTA) Digital Trade Protocol are reinforcing the necessity for interoperable electronic transaction ledgers across regional supply chains.
Complete compliance timeline
The table below outlines the historical milestones, enacted expansions, and active operational deadlines governing electronic invoicing in Uganda:
Date | Regulatory phase | Scope and compliance requirements |
May 2018 | Legislative enactment | Parliament passes the Tax Procedures Code (Amendment) Act 2018, inserting Section 73A to provide statutory authority for electronic invoicing systems. |
June 2020 | Regulatory formalisation | Publication of the Tax Procedures Code (Electronic Fiscal Receipting and Invoicing) Regulations 2020 in the Uganda Gazette. |
1 January 2021 | Universal VAT mandate | Mandatory deployment of EFRIS enters into force for all VAT-registered taxpayers across Uganda. |
1 July 2022 | Supply chain validation | Enforcement of automated reconciliation between buyer input VAT deduction schedules and seller EFRIS output records. |
25 July 2025 | Sectoral expansion notice | The URA gazettes General Notice No. 2218, expanding mandatory EFRIS compliance to twelve commercial sectors. |
1 July 2025 | Phase 2 enforcement | Mandatory compliance takes effect for all operators in the twelve specified industries, irrespective of their VAT registration status. |
2026 (Ongoing) | Deductibility enforcement | Systematic application of corporate income tax expense disallowances for commercial purchases lacking verified EFRIS fiscal documentation. |
Legal framework
Uganda's electronic invoicing regime is grounded in statutory law, supported by administrative regulations and binding gazetted notices:
Tax Procedures Code Act 2014 (as amended):
Section 73A: The primary legal foundation governing electronic invoicing. It mandates that a taxpayer specified by the Commissioner General shall issue electronic fiscal receipts or invoices, or employ an Electronic Fiscal Device (EFD) linked to the centralised tax authority platform.
Section 73B: Establishes the statutory authority and penalties relating to failure to use electronic fiscal devices or intentional tampering with hardware and data transmissions.
Section 86 & Section 62: Establish civil fines, penal taxes, and criminal liabilities for non-compliance with tax procedures, fraudulent accounting, and evasion.
Tax Procedures Code (Electronic Fiscal Receipting and Invoicing) Regulations 2020:
Prescribes the technical, operational, and procedural rules for connecting to EFRIS.
Establishes standard invoice data fields, transmission timelines, offline contingency rules, and device security standards.
Value Added Tax Act, Cap 349 (as amended):
Section 24 and Section 28 govern invoice issuance rules, tax credit eligibility, and input VAT deduction claims. Under current enforcement rules, an input tax credit cannot be claimed unless the transaction is substantiated by an official EFRIS invoice.
Income Tax Act, Cap 340 (as amended):
Governs corporate expense deductibility. Commercial purchases that cannot be verified through the URA central transaction database are treated as non-deductible for corporate income tax assessment.
General Notice No. 2218 of 2025:
Official statutory notice published in the Uganda Gazette expanding mandatory EFRIS participation to additional taxpayer categories and business sectors.
Authorities
The design, implementation, and regulatory enforcement of Uganda's digital tax ecosystem involve three principal bodies:
Authority | Institutional role and mandate |
Ministry of Finance, Planning and Economic Development (MoFPED) | Develops national fiscal policy, drafts primary tax legislation, and presents statutory amendments regarding digital tax administration to Parliament. |
Uganda Revenue Authority (URA) | Acts as the central tax administration body responsible for administering EFRIS, publishing technical specifications, verifying taxpayer integrations, and enforcing statutory tax compliance. |
Uganda National Bureau of Standards (UNBS) | Collaborates with the URA in testing and certifying physical Electronic Fiscal Devices (EFD) and Electronic Dispenser Controllers (EDC) to guarantee cryptographic hardware integrity. |
Scope of the mandate
Who is required to use EFRIS?
Uganda enforces digital transaction monitoring across two distinct statutory categories:
All VAT-registered businesses: Any legal entity, partnership, or individual sole trader with an annual taxable turnover exceeding UGX 150 million must register for VAT and interface with EFRIS.
Taxpayers in twelve specified commercial sectors: All businesses operating within the twelve gazetted sectors are legally mandated to issue electronic invoices or receipts via EFRIS, regardless of their VAT registration status or annual turnover.
The twelve designated commercial sectors in detail
Pursuant to the official gazette notice issued by the URA, the expanded scope covers:
Manufacturing: Physical or chemical transformation of materials or components into new products.
Mining and quarrying: Extraction of minerals in solid, liquid, or gaseous forms.
Water supply, sewerage, and waste remediation: Water collection, treatment, and industrial/commercial waste disposal activities.
Electricity, gas, steam, and air conditioning supply: Generation, transmission, and distribution of electric power and gas via networks.
Construction: General and specialised commercial, industrial, or residential building and civil engineering projects.
Transportation and storage: Freight transport (rail, road, pipeline, water, air), cargo handling, terminal facilities, postal, and warehousing.
Accommodation and food service activities: Hotels, tourist lodges, short-stay accommodations, restaurants, caterers, and commercial beverage establishments.
Information technology and communication: Software development, data processing, hosting, telecommunications, and media broadcasting.
Real estate activities: Lessors, commercial property managers, sales brokers, appraisals, and escrow agencies.
Professional, scientific, and technical activities: Legal practices, accounting firms, engineering consultancies, management advisory, architectural firms, and technical testing services.
Arts, entertainment, and recreation: Commercial sports facilities, amusement centres, gaming/gambling operators, event production, and cultural operations.
Wholesale and retail of fuel: All service stations, wholesalers, and fuel depots supplying automotive fuels (Petrol/PMS, Diesel/AGO) and kerosene.
Transaction exemptions and out-of-scope operations
Passenger land transport exclusion: For the current phase of the sectoral expansion, the URA explicitly excludes passenger land transport providers from mandatory EFRIS deployment. This exemption encompasses commuter omnibuses (taxis), boda-bodas (motorcycle taxis), airport transfer shuttles, and intercity passenger buses.
Micro-enterprises outside the twelve sectors: Sole traders and micro-businesses operating outside the twelve designated categories whose annual revenue falls below the UGX 150 million VAT registration threshold remain exempt from mandatory EFRIS, although voluntary onboarding is permitted.
Cross-border transactions: Export sales must be cleared through EFRIS using zero-rated VAT codes and linked with Uganda Customs customs declarations (ASYCUDA World). Import transactions are logged upon border clearance, generating reference metrics against which domestic sales are reconciled.
Uganda's e-invoicing requirements
Electronic invoicing under the URA is governed by strict functional and structural parameters designed to establish transaction traceability.
System connectivity channels
Taxpayers subject to the mandate must deploy one of the following technical mechanisms to generate compliant documents:
System-to-system integration (REST APIs): Designed for medium and large enterprises operating modern Enterprise Resource Planning (ERP) platforms (such as SAP, Oracle, Microsoft Dynamics, or custom accounting engines). The ERP transmits transactional JSON or XML data directly to the URA EFRIS web service API in real time.
EFRIS client application: A dedicated desktop or mobile software package provided by the URA for Windows, Android, and iOS, allowing traders to enter sales records manually or through connected barcode scanners.
URA web portal interface: A cloud interface accessed via the official tax authority portal using a Taxpayer Identification Number (TIN) and multi-factor authentication (SMS/email One-Time Password - OTP).
Electronic Fiscal Devices (EFDs): Secure physical Point of Sale (POS) terminals equipped with cryptographic memory modules that communicate with URA servers over cellular networks.
Electronic Dispenser Controllers (EDCs): Mandatory hardware devices connected directly to forecourt fuel dispensers to automatically meter volumes and transmit sales data upon every pump transaction.
USSD mobile service: A basic mobile protocol permitting small, non-smartphone users to record transactions using cellular network short-codes.
Mandatory invoice data elements
A valid EFRIS electronic invoice or receipt must contain the following verified data components:
Fiscal Document Number (FDN): A unique, sequential cryptographic number generated solely by the URA central engine upon invoice approval.
Verification code: A security hash code returned by the URA for verification on public search portals.
Quick Response (QR) code: A 2D barcode containing the encoded URL pointing to the URA validation engine, enabling customers or tax inspectors to verify authenticity instantly using any smartphone camera or the URA EFRIS mobile app.
Taxpayer Identification Numbers (TINs): Validated TIN of the supplier and the customer (mandatory for all B2B transactions).
Commodity category codes: Standardised classification codes defining the precise nature of the goods or services supplied.
Itemised transaction lines: Net unit prices, quantities, gross values, applicable VAT rates (18%, 0%, or exempt), and net tax amounts.
Currency code: Transacted currency, with foreign exchange rates declared where payments are billed in non-UGX currencies.
Document archiving and record-keeping
Under Section 15 of the Tax Procedures Code Act, electronic fiscal records must be archived in their original structured digital format for a statutory minimum of six years. The archive must preserve source authenticity, content integrity, and continuous digital readability for audit retrieval.
Uganda's e-reporting requirements
Unlike compliance regimes that limit reporting to sales values, Uganda's EFRIS architecture couples transaction clearance with continuous inventory tracking.
Integrated stock management and balance tracking
A central component of EFRIS is the mandatory stock management module. Taxpayers who sell physical goods cannot issue an electronic sales invoice unless the underlying stock has been pre-registered within their EFRIS digital warehouse:
Stock initialisation: Businesses must upload their opening inventory quantities, commodity descriptions, and purchase prices into the URA portal.
Stock increments: Inventory balances increase automatically when domestic EFRIS purchase invoices are cleared by local suppliers or when customs import declarations are processed through the URA customs gateway.
Stock decrements: Every approved sales invoice deducts inventory quantities in real time. Manual stock adjustments (e.g. damages, expiry, internal consumption, shrinkage) require formal administrative justifications recorded within the system.
Pre-filled tax returns
Because the URA receives line-item transaction records continuously, EFRIS automatically generates pre-populated monthly VAT returns. Taxpayers log in at the end of each tax period to verify aggregate output VAT and eligible input VAT credits. Discrepancies between internal commercial records and the EFRIS pre-filled return must be formally reconciled prior to submission.
Technical architecture
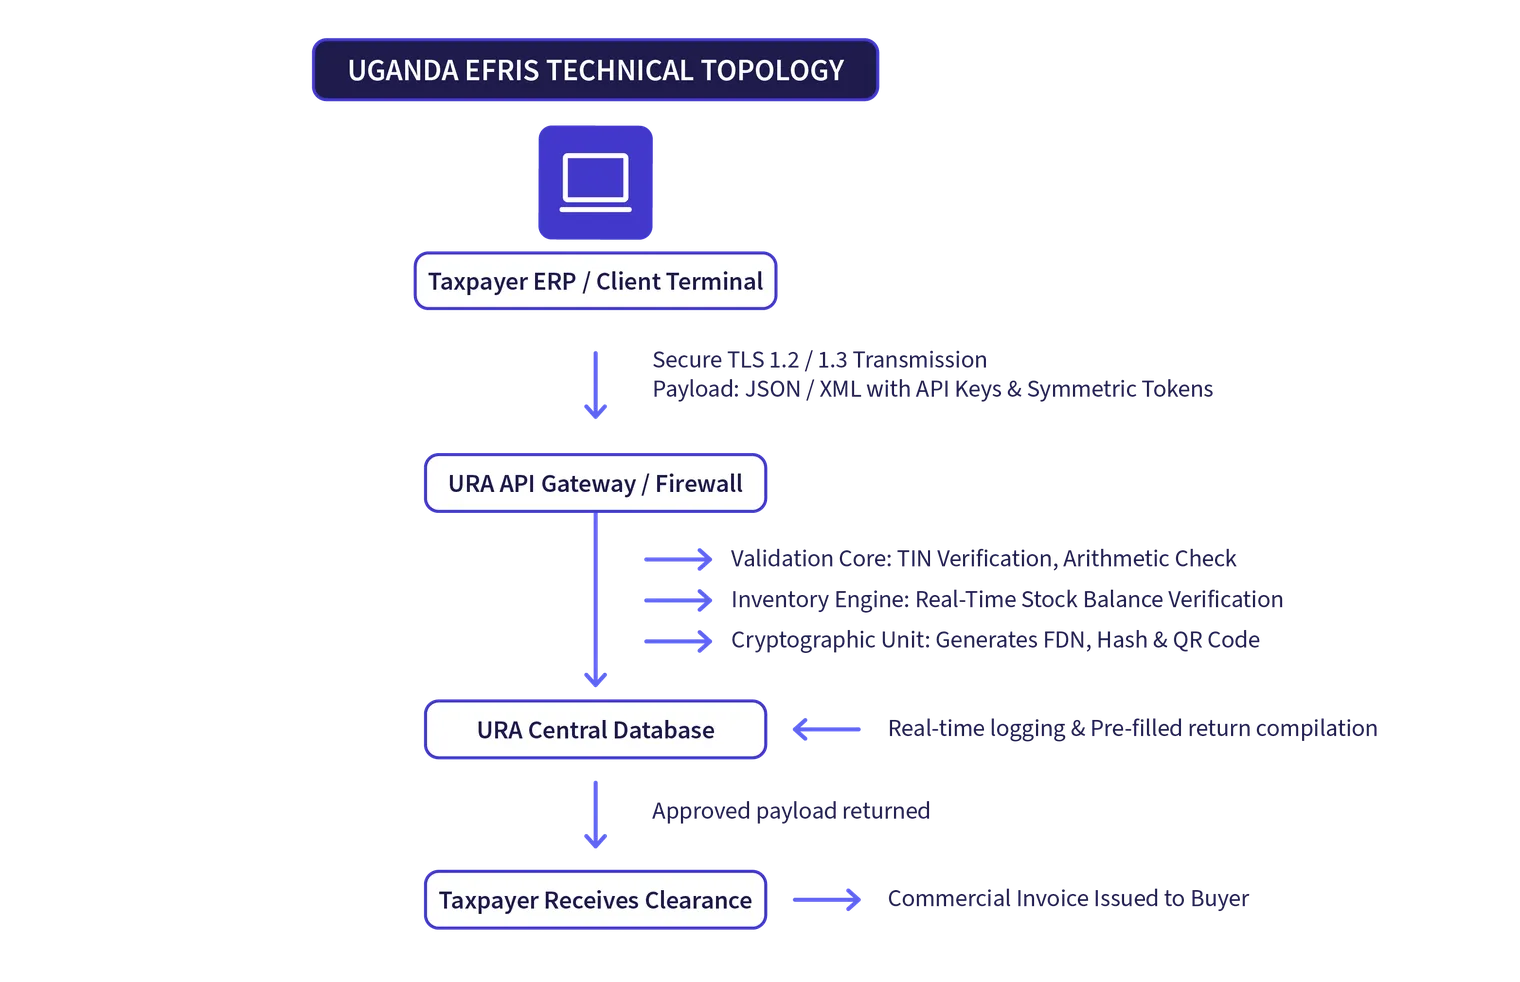
The technical architecture of EFRIS operates as a centralised continuous transaction control and clearance model:
Clearance mechanism vs distributed models
Unlike the 5-corner Continuous Transaction Controls model emerging in jurisdictions such as Oman or Slovakia, or the decentralised Peppol four-corner network used in Western Europe, Uganda uses an authoritative three-corner clearance architecture:
The supplier cannot release an invoice to a customer until the URA system clears the payload.
Transmission occurs over encrypted HTTPS connections using secure RESTful APIs.
Authentication requires system-to-system credentials, including corporate digital certificates and client security tokens issued during portal registration.
Offline operational contingency
To accommodate intermittent internet connectivity across rural commercial zones, the EFRIS architecture permits offline operations for up to five calendar days. During network outages, registered client software and certified EFD devices generate provisional offline invoices bearing internal cryptographic tokens. These queued documents must be automatically synchronised with URA central servers immediately upon network restoration.
Statutory penalties and enforcement risks
Ugandan tax law enforces non-compliance with electronic invoicing through severe financial sanctions, criminal liabilities, and commercial operational disqualifications:
Statutory penal tax under Section 73A
Under Section 73A of the Tax Procedures Code Act, any person specified by the Commissioner General who fails to issue an electronic invoice or receipt via EFRIS, or fails to employ a mandated fiscal device, is liable to pay a penal tax equal to:
UGX 6,000,000 (approximately USD 1,600); or
The total tax amount due on the underlying goods or services, whichever figure is higher.
This penal assessment applies on a per-infraction or periodic basis, creating rapid exposure for high-volume commercial traders attempting to bypass the system.
Penalties for system tampering (Section 73B)
A person who deliberately tampers with, manipulates, damages, or bypasses an Electronic Fiscal Device, or alters the software instructions designed to communicate with EFRIS, commits a criminal offence under Section 73B. Upon conviction, the court may impose a fine not exceeding 1,500 currency points (UGX 30,000,000) or imprisonment for a period up to ten years, or both.
Disallowance of corporate income tax deductions
Beyond direct statutory fines, the most consequential financial risk for enterprise buyers is the loss of business expense deductibility. Under prevailing tax rulings, commercial expenditures incurred by businesses cannot be claimed as allowable deductions for corporate income tax assessment unless the purchase is evidenced by an official EFRIS invoice.
An administrative invoicing error by an unregistered or non-compliant supplier immediately exposes the enterprise purchaser to a 30% corporate tax penalty on the entire value of the disallowable purchase.
Disallowance of input VAT credits
For VAT-registered operators, the URA system automatically disallows input VAT claims during monthly reconciliation if the corresponding supplier has not remitted an approved EFRIS record bearing a valid Fiscal Document Number (FDN). This renders manual paper invoices and unvalidated PDFs completely useless for VAT recovery.
How businesses can prepare
Achieving and maintaining compliance under Uganda's EFRIS requirements requires a structured roadmap across internal business processes, enterprise software infrastructure, and vendor management:
1. Verify sectoral scope and registration status
Commercial operators must evaluate whether their corporate operations fall under the twelve gazetted categories. If a business operates within any of these sectors, management must register the corporate TIN on the EFRIS portal immediately, regardless of historic VAT turnover metrics.
2. Integrate ERP billing systems via system-to-system APIs
Mid-sized and enterprise companies should avoid manual portal entries, which increase errors and administrative overhead. IT teams must interface internal ERP software (such as SAP, Oracle, Microsoft Dynamics, or bespoke platforms) directly with the URA EFRIS API. Integration requires:
Configuring secure API connectivity over HTTPS with URA security keys.
Mapping internal stock keeping units (SKUs) to URA product classification codes.
Enabling the ERP to capture, store, and print the resulting FDN, verification code, and dynamic QR code on outward commercial invoices.
3. Cleanse customer and supplier master data
EFRIS rejects transaction payloads containing incorrect, expired, or deactivated tax identifiers. Organisations must clean customer master files to ensure that all B2B clients possess verified TINs. Inbound vendor management must mandate that all suppliers provide valid EFRIS documentation.
4. Initialise and audit EFRIS inventory balances
Because sales cannot be registered without matching stock balances, physical stock counts must be aligned with EFRIS digital warehouse records. Establish daily or weekly internal reconciliations between actual warehouse stock and the digital balances recorded on the URA portal to avoid billing interruptions.
5. Automate inbound accounts payable verification
Procurement and accounts payable teams must establish controls to scan and validate inbound supplier invoices against the URA verification portal before authorising bank disbursements. Confirming the presence of a genuine FDN and scanning the QR code protects the business from fraudulent tax deductions and corporate tax reassessments.
Conclusion
Uganda's deployment of the Electronic Fiscal Receipting and Invoicing Solution (EFRIS) demonstrates the rapid acceleration of continuous transaction monitoring across East Africa. By anchoring VAT and corporate tax deductibility to real-time clearance, the Uganda Revenue Authority has created an enforcement mechanism that leaves little room for non-compliance.
The expansion of mandatory EFRIS participation across twelve key commercial sectors highlights the government's strategy to broaden the tax net far beyond traditional corporate entities. As the URA strengthens automated cross-matching between supplier declarations and buyer deductions, businesses that rely on manual procedures, unvalidated PDFs, or paper documentation face significant financial penalties and disallowances.
Organisations operating in Uganda must take immediate action to align their commercial operations with EFRIS. By auditing sectoral exposure, cleansing customer master data, automating accounts payable verification, and connecting enterprise ERP software via robust REST APIs, businesses can secure tax compliance, protect their tax deductions, and establish an automated accounting infrastructure built for the future of digital tax compliance in Africa.
FAQ
No. A PDF or printed document sent via email is treated as an unstructured, non-compliant document with no legal standing for tax deduction purposes. To be legally recognised for input VAT recovery or corporate income tax expense deduction, the invoice must be cleared through EFRIS and display an official Fiscal Document Number (FDN), verification code, and verifiable QR code.