This article was updated on 9 July 2026 to reflect the latest developments in Slovakia's mandatory B2B e-invoicing and near real-time e-reporting framework, including the Financial Directorate's published guidance, the implementation of the Peppol-based 5-corner model, and the proposed legislative amendments affecting buyer reporting obligations during the transitional period leading up to 2030.
Introduction & digital tax strategy
Slovakia is introducing one of Europe's most significant VAT digitalisation reforms, requiring VAT-registered businesses to exchange structured electronic invoices and report invoice data electronically for domestic B2B transactions from 1 January 2027. The reform forms part of Slovakia's broader strategy to modernise tax administration while aligning its national framework with the European Union's VAT in the Digital Age (ViDA) initiative.
Unlike clearance models that rely on a central government gateway to approve invoices before issuance, Slovakia has selected a Peppol-based 5-corner model. Accredited service providers, officially known in Slovakia as a Digitálny poštár (Digital Postman), will facilitate both the secure exchange of invoices between commercial trading partners and the automated transmission of required tax data to the Financial Administration.
This comprehensive guide explains Slovakia's e-invoicing and e-reporting framework, including the legal foundation, implementation roadmap, scope of application, operational workflow of the 5-corner model, technical data standards, non-compliance sanctions, and practical steps organisations must take to prepare for the 2027 mandate.
Understanding Slovakia's e-invoicing and e-reporting framework
Slovakia is undergoing a major digital transformation of its VAT system through the introduction of mandatory electronic invoicing and near real-time e-reporting for domestic Business-to-Business transactions. The reform is designed to modernise tax administration, improve VAT compliance and reduce tax fraud, while aligning the country's national framework with the European Union's ViDA initiative.
Although Slovakia has required electronic invoicing for Business-to-Government and Government-to-Government transactions since 2023, the new legislation significantly expands these obligations to the private sector. From 1 January 2027, VAT-registered businesses carrying out domestic B2B transactions will generally be required to issue, receive and exchange structured electronic invoices and report invoice data electronically through an accredited service provider.
A key feature of Slovakia's framework is its adoption of a Peppol-based 5-corner model. Rather than transmitting invoices directly to the tax authority, businesses will exchange invoices through accredited service providers, known as Digital Postmen, which will also handle the near real-time reporting of invoice data to the Financial Administration. This approach is intended to simplify compliance while promoting secure, standardised and interoperable electronic document exchange.
To help businesses prepare for the transition, Slovakia has also planned a voluntary testing period ahead of the mandatory rollout, allowing organisations to adapt their invoicing systems and business processes before the new obligations take effect. As the framework continues to evolve, businesses should monitor legislative developments and official guidance to ensure they remain compliant with the latest requirements.
Historical evolution and EU context
Slovakia's digital tax journey has evolved across multiple legislative iterations over the past decade:
Early fiscalisation and e-Kasa: Slovakia first prioritised consumer-facing cash transactions by introducing the e-Kasa online fiscalisation system in 2019, connecting point-of-sale registers directly to the central tax authority database.
Public sector e-invoicing (B2G): In April 2023, Slovakia introduced mandatory e-invoicing for B2G and Government-to-Government (G2G) transactions under the European e-invoicing standard (EN 16931). Initially designed to operate via a central government portal (Information System of Electronic Invoicing - IS EFA), implementation encountered administrative delays, prompting the government to re-evaluate its long-term technical architecture.
Transition to Peppol and Act No. 385/2025 Coll.: On 9 December 2025, the National Council of the Slovak Republic formally enacted Act No. 385/2025 Coll., amending the national VAT Act. This landmark legislation abandoned the exclusive reliance on a central government exchange portal for B2B transactions in favour of an international Peppol 5-corner architecture, while simultaneously transitioning B2G e-invoicing onto the same framework.
Alignment with EU ViDA: The Slovak model is engineered to comply directly with EU Directive 2014/55/EU and the EU's ViDA package. By establishing structured electronic invoicing based on EN 16931 and standardising digital reporting formats, Slovakia ensures that its domestic infrastructure will seamlessly integrate with upcoming EU-wide cross-border digital reporting requirements scheduled for 1 July 2030.
The phased timeline in Slovakia
Slovakia's transition to mandatory e-invoicing and e-reporting has taken place over several years, evolving from electronic invoicing in the public sector to a comprehensive framework for domestic B2B transactions. The timeline below highlights the key legislative and implementation milestones.
Date | Milestone |
April 2023 | Mandatory e-invoicing for Business-to-Government (B2G) and Government-to-Government (G2G) transactions begins through the IS EFA platform, aligned with the European e-invoicing standard (EN 16931). |
9 December 2025 | The National Council of the Slovak Republic approves amendments to the VAT Act introducing mandatory domestic B2B e-invoicing and near real-time e-reporting from 2027. |
1 January 2026 | Planned start of the voluntary transition period, allowing businesses to test their systems and prepare for the mandatory implementation. |
Q3 2026 | The Financial Administration expects to make digital reporting services available following the implementation of its technical infrastructure (SP / Corner 5), supporting businesses during the testing phase. |
1 January 2027 | Mandatory structured B2B e-invoicing and near real-time e-reporting for domestic transactions between VAT-registered businesses enter into force. Businesses must exchange invoices through accredited Digital Postmen using the Peppol network. |
1 July 2030 | Slovakia plans to extend its framework in line with the EU's VAT in the Digital Age (ViDA) initiative. This includes cross-border e-invoicing and digital reporting requirements, the removal of the Control and Summary Statements, and a reduction of the general invoice issuance deadline from 15 to 10 days. |
Although the core framework has now been approved, Slovakia continues to refine certain aspects of the legislation. In particular, a proposed amendment published in May 2026 would postpone the obligation for domestic buyers to report data from received e-invoices until 1 July 2030, while maintaining the requirement for businesses to be capable of receiving electronic invoices from 1 January 2027. Businesses should therefore continue to monitor legislative developments and official guidance issued by the Financial Directorate and the Ministry of Finance.
Legal framework
Slovakia's mandatory B2B e-invoicing and near real-time e-reporting framework is established through amendments to the country's VAT legislation and supported by implementing guidance issued by the Financial Directorate of the Slovak Republic. Together, these measures create the legal basis for the mandatory exchange of structured electronic invoices and the electronic reporting of invoice data for domestic B2B transactions.
The principal legal instruments include:
Act No. 222/2004 Coll. on Value Added Tax (Zákon o dani z pridanej hodnoty), as amended. This represents the primary statutory instrument governing VAT compliance, invoice content, issuance rules, and deduction rights in Slovakia.
Act No. 385/2025 Coll., which specifically amends Act No. 222/2004 Coll. to introduce mandatory structured electronic invoicing, continuous e-reporting, and the legal framework for accredited service providers (Digitálny poštár) from 1 January 2027.
Decrees and technical specifications published by the Financial Directorate of the Slovak Republic (Finančné riaditeľstvo SR), detailing the Slovak Core Invoice Usage Specification (SK_CIUS), data mapping rules, and security protocols for Corner 5 integration.
EU Directive 2014/55/EU, establishing the European standard for electronic invoicing in public procurement and forming the semantic foundation for Slovakia's domestic rules.
The Slovak framework is also designed to support the European Union's VAT in the Digital Age (ViDA) initiative. Future legislative changes, planned from 1 July 2030, are expected to further align Slovakia's national framework with the EU's harmonised approach to digital reporting and electronic invoicing for cross-border transactions.
Wherever possible, businesses should refer to the official legislation and guidance issued by the Slovak authorities, as technical specifications and implementation requirements may continue to evolve ahead of the mandatory implementation date.
Authorities
Several public authorities are responsible for the development, implementation and administration of Slovakia's e-invoicing and e-reporting framework.
Ministry of Finance of the Slovak Republic
The Ministry of Finance is responsible for developing Slovakia's tax policy and preparing the legislation governing mandatory e-invoicing and digital reporting. It also oversees the country's broader strategy for VAT digitalisation and alignment with the European Union's VAT in the Digital Age (ViDA) initiative.
Financial Directorate of the Slovak Republic
The Financial Directorate is responsible for implementing the framework and publishing the operational guidance businesses need to comply with the new obligations. This includes technical documentation, implementation guidance, frequently asked questions (FAQs) and updates relating to the rollout of the mandate.
Financial Administration of the Slovak Republic
The Financial Administration operates the technical infrastructure that supports Slovakia's e-invoicing and e-reporting framework. Under the new model, invoice data will be transmitted to the Financial Administration through accredited service providers, enabling the tax authority to receive near real-time transaction data while maintaining a decentralised exchange model.
Peppol Authority
Slovakia's framework is based on the Peppol network, which provides the interoperability standards used for exchanging structured electronic invoices. Rather than operating as the national tax authority, Peppol defines the technical framework that enables secure and standardised document exchange between accredited service providers across participating countries.
Scope of the mandate
From 1 January 2027, mandatory e-invoicing and e-reporting apply broadly to domestic commercial activity within the Slovak Republic.
In-scope transactions
Domestic B2B supplies: All taxable supplies of goods and services carried out between VAT-registered businesses where the place of supply is Slovakia.
Taxable entities: Businesses established in Slovakia, as well as foreign entities registered for VAT in Slovakia carrying out domestic transactions.
B2G supplies: All sales of goods and services to public sector entities and state organisations.
Out-of-scope or exempted transactions
Business-to-Consumer (B2C) transactions: Sales to end consumers remain excluded from the e-invoicing mandate, although consumer sales remain subject to fiscalisation via the e-Kasa system.
Cross-border transactions: Intra-Community supplies and exports remain governed by standard VAT rules until the EU ViDA cross-border mandate takes effect on 1 July 2030.
Specific statutory exemptions: Financial and insurance services exempt from VAT under Slovak law where invoice issuance is not required under standard VAT regulations.
Transactions covered
The mandate applies to most domestic taxable B2B supplies between VAT-registered businesses. This includes transactions where both the supplier and the customer are established, registered or required to be registered for VAT in Slovakia.
Transactions outside the scope
Certain transactions remain outside the scope of the domestic B2B mandate, including:
Business-to-Consumer (B2C) transactions.
Cross-border transactions, which continue to follow the existing VAT rules until future changes introduced under the EU's VAT in the Digital Age (ViDA) initiative.
Other transactions excluded under Slovak VAT legislation or future implementing guidance.
Future developments
From 1 July 2030, Slovakia is expected to further expand its digital VAT framework in line with ViDA, introducing harmonised cross-border digital reporting requirements across the European Union. Businesses should therefore monitor future legislative developments to understand how these changes may affect their compliance obligations.
Slovakia's e-invoicing requirements
Slovakia's mandatory B2B e-invoicing framework requires businesses within the scope of the mandate to issue, receive and exchange structured electronic invoices for domestic transactions. From 1 January 2027, these invoices must be exchanged electronically through the national framework using accredited service providers, replacing traditional paper and unstructured electronic invoices for in-scope transactions.
The framework is based on the European e-invoicing standard (EN 16931), ensuring interoperability between businesses and supporting future alignment with the European Union's VAT in the Digital Age (ViDA) initiative. Electronic invoices must therefore be created in a structured format that complies with the applicable technical specifications.
Businesses within the scope of the mandate will generally be required to:
Issue structured electronic invoices for domestic B2B transactions.
Receive electronic invoices through the approved exchange framework.
Use an accredited service provider ("Digital Postman") to exchange invoices electronically.
Ensure invoices comply with the required technical and data standards.
Retain electronic invoices in accordance with Slovak record-keeping requirements.
Invoice requirements
Electronic invoices must include all information required under Slovak VAT legislation while complying with the technical specifications published by the Financial Directorate.
Invoices are expected to follow the EN 16931 European standard, typically using UBL XML as the structured data format. This ensures interoperability across the Peppol network and supports future compliance with EU-wide digital reporting requirements under ViDA.
Businesses should also ensure that their ERP or e-invoicing solution is capable of generating compliant electronic invoices and can be updated as the technical specifications evolve.
Archival obligations
Electronic invoices and their associated validation logs must be archived in their original structured XML format for a statutory period of 10 years. Invoices must maintain content integrity, source authenticity, and continuous legibility throughout the entire retention period.
Slovakia's e-reporting requirements
In tandem with electronic invoicing, Slovakia introduces a continuous transaction control (CTC) e-reporting framework for domestic B2B sales.
Operational mechanics and reporting payload
Rather than requiring businesses to submit separate periodic tax filings, digital reporting is directly embedded into the invoice issuance process. When a supplier's service provider processes an electronic invoice, it automatically generates a standardised tax data payload known as the Slovak Tax Data Document (SK TDD).
Reporting window and frequency
The SK TDD payload must be transmitted electronically to the Financial Administration's central database (Corner 5) in near real-time. Technical guidelines establish a maximum reporting window of 15 minutes from the time the invoice is dispatched into the Peppol network.
Buyer reporting obligations
To streamline business readiness, proposed legislative amendments postpone the obligation for domestic buyers to independently report data from received electronic invoices until 1 July 2030. However, buyers remain legally required to possess the technical capability to receive structured electronic invoices via an accredited service provider from 1 January 2027.
The road to ViDA
As part of Slovakia's alignment with the EU's VAT in the Digital Age (ViDA) initiative, the e-reporting framework is expected to evolve further. From 1 July 2030, additional changes are planned, including the introduction of EU-wide digital reporting requirements for cross-border transactions and the removal of certain existing VAT reporting obligations, such as the Control Statement and Recapitulative Statement, where applicable.
How Slovakia's Peppol 5-corner model works
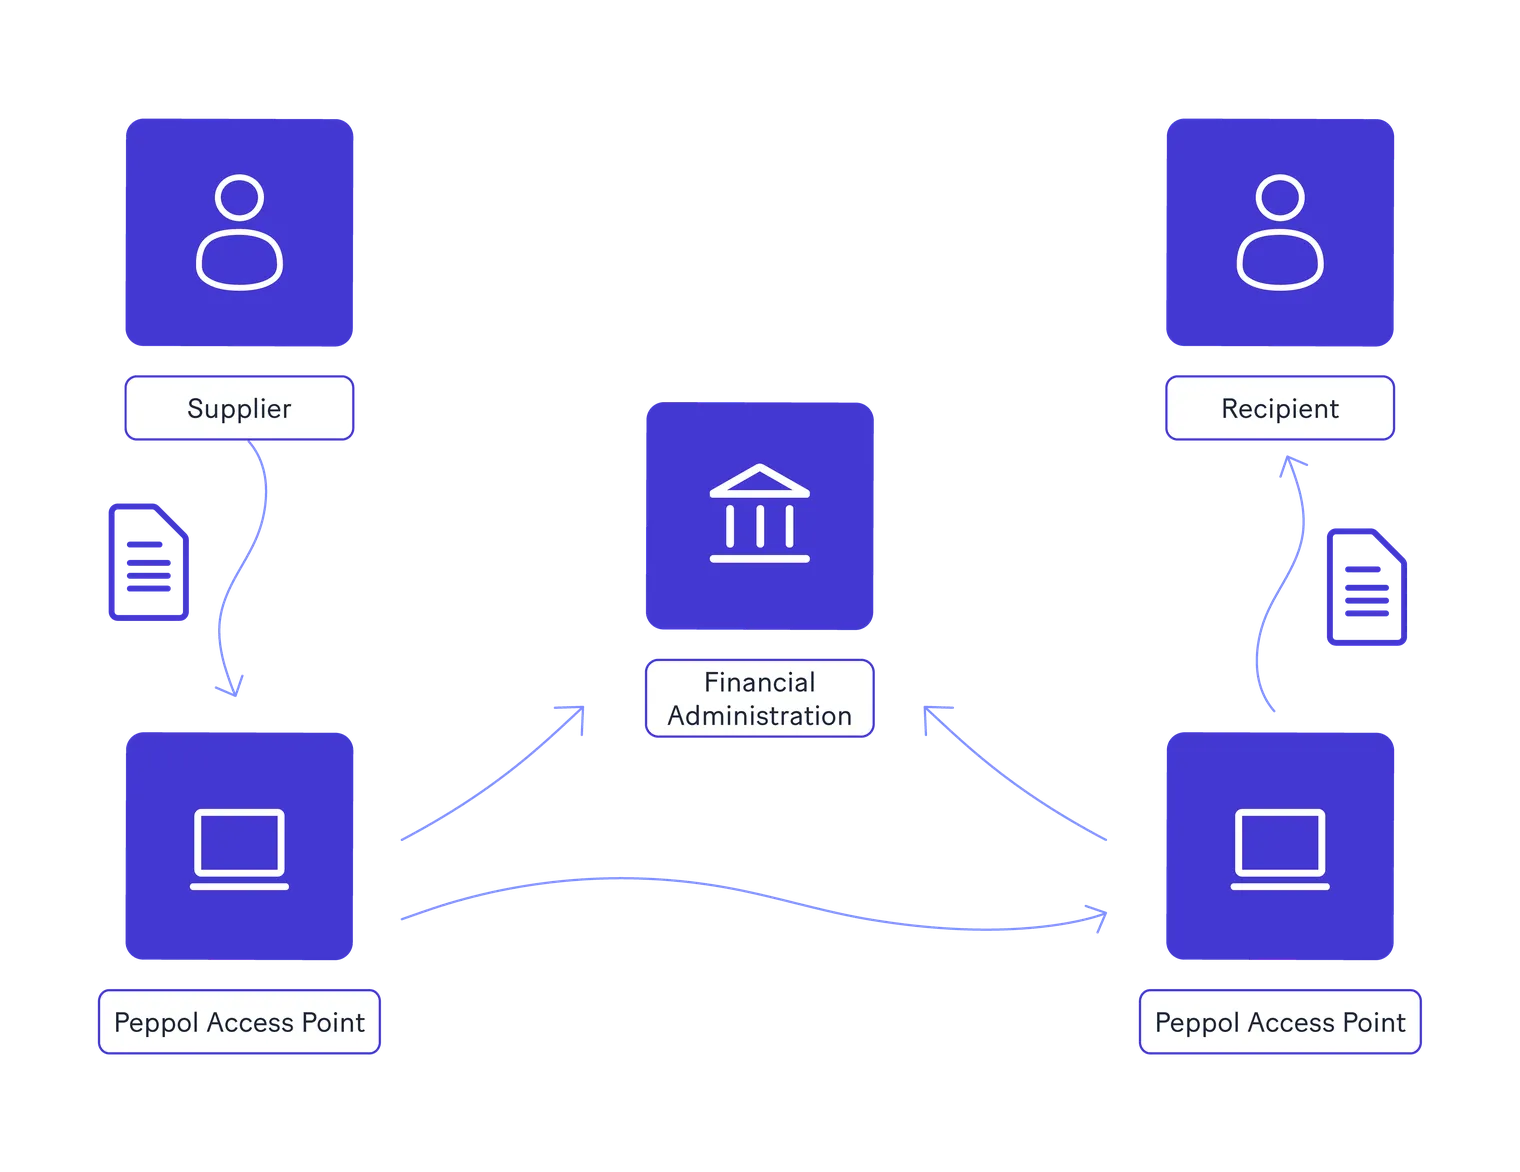
Unlike many countries that rely on a central government platform to exchange electronic invoices, Slovakia has adopted a Peppol-based 5-corner model. This decentralised approach enables businesses to exchange structured electronic invoices securely through accredited service providers while simultaneously reporting invoice data to the Financial Administration.
The model introduces an additional participant, the Financial Administration, as the fifth corner of the traditional Peppol network. As a result, businesses do not communicate directly with the tax authority. Instead, accredited service providers, known as Digital Postmen, facilitate both the exchange of invoices between trading partners and the transmission of the required invoice data to the authorities.
How the 5-corner model works
The process can be summarised as follows:
The supplier creates a structured electronic invoice using a compliant ERP or e-invoicing solution.
The invoice is transmitted to the supplier's accredited Digital Postman.
The Digital Postman forwards the invoice through the Peppol network to the recipient's Digital Postman.
The recipient receives the electronic invoice through their chosen service provider.
At the same time, the required invoice data is transmitted to the Financial Administration, fulfilling the near real-time e-reporting obligation.
Benefits of the 5-corner model
By building its framework on the Peppol network, Slovakia aims to provide a secure and interoperable method for exchanging electronic invoices while simplifying tax reporting obligations. The model offers several advantages, including:
Secure and standardised electronic invoice exchange.
Greater interoperability between businesses and service providers.
Integration of e-invoicing and e-reporting into a single process.
Reduced administrative burden through automated reporting.
Alignment with European interoperability standards and future ViDA requirements.
As businesses can choose their preferred accredited Digital Postman, the framework also promotes flexibility while ensuring compliance with Slovakia's technical and reporting requirements.
Penalties for non-compliance
Businesses within the scope of Slovakia's e-invoicing and e-reporting framework are expected to comply with the legal and technical requirements established under the amended VAT Act and the guidance issued by the Financial Directorate. Failure to meet these obligations may result in administrative penalties and other enforcement measures in accordance with Slovak tax legislation.
Potential areas of non-compliance may include:
Failure to issue or receive compliant electronic invoices.
Failure to report invoice data within the required timeframe.
Use of non-compliant invoicing systems or formats.
Submission of incomplete or inaccurate invoice data.
Failure to comply with record-keeping and archiving requirements.
As the framework continues to develop ahead of the mandatory implementation date, businesses should monitor official guidance for further details on the applicable penalties and enforcement procedures.
Taking a proactive approach to compliance, including implementing a compliant e-invoicing solution, reviewing internal processes and keeping systems aligned with the latest technical specifications, can help reduce the risk of non-compliance once the mandate enters into force.
How businesses can prepare
Although Slovakia's mandatory B2B e-invoicing and e-reporting requirements will apply from 1 January 2027, businesses should begin preparing well in advance. Early planning will help organisations adapt their systems, minimise implementation risks and ensure they are ready to comply once the mandate takes effect.
To prepare, businesses should:
Review their invoicing processes to determine whether they support structured electronic invoicing and the new reporting requirements.
Assess their ERP or e-invoicing solution to ensure it can generate invoices compliant with the EN 16931 standard and integrate with an accredited Digital Postman.
Identify and select an accredited service provider capable of exchanging invoices through the Peppol network and transmitting invoice data to the Financial Administration.
Train internal teams, including finance, tax and IT, on the new invoicing and reporting obligations.
Monitor legislative and technical developments, including updates issued by the Ministry of Finance and the Financial Directorate, as the framework continues to evolve ahead of the mandatory implementation date.
Businesses may also wish to take advantage of the planned voluntary testing period before the mandate enters into force. Testing systems and processes in advance can help identify potential issues and ensure a smoother transition to mandatory compliance.
Preparing early will help businesses reduce implementation risks and ensure they are ready to comply with Slovakia's evolving e-invoicing and e-reporting framework.
Conclusion
Slovakia is taking a significant step towards the digitalisation of its VAT system through the introduction of mandatory B2B e-invoicing and near real-time e-reporting. By adopting a Peppol-based 5-corner model, the country aims to modernise invoice exchange, improve VAT compliance and align its national framework with the European Union's VAT in the Digital Age (ViDA) initiative.
Although the mandatory requirements will not take effect until 1 January 2027, businesses should begin preparing well in advance. Reviewing existing invoicing processes, implementing a compliant e-invoicing solution and working with an accredited Digital Postman will help organisations ensure a smoother transition to the new framework.
As Slovakia continues to refine its technical specifications and implementation guidance, businesses should regularly monitor updates from the Ministry of Finance and the Financial Directorate to ensure they remain compliant with the latest requirements. Taking a proactive approach today will help minimise implementation risks and support long-term compliance as Slovakia's digital tax framework continues to evolve.
FAQ
No. For domestic B2B transactions in scope, standard PDF invoices sent via email do not meet the legal definition of an electronic invoice under Act No. 385/2025 Coll. Invoices must be issued in a structured electronic format (such as UBL XML) compliant with EN 16931 and SK_CIUS.