This article was updated on 26 August 2026 to reflect the official roadmap confirmed under Ireland's Budget 2026 and published by the Irish Tax and Customs (Revenue) in their implementation report VAT Modernisation: Implementation of eInvoicing in Ireland. It incorporates the finalized phased rollout schedule starting in November 2028, technical alignment with European Standard EN 16931 via Peppol, and integration with the European Union's VAT in the Digital Age (ViDA) initiative.
Introduction & digital tax strategy
The Irish tax authority, Revenue, is executing a fundamental modernisation of Ireland's Value-Added Tax administration. For over five decades, Irish businesses have complied with VAT obligations through periodic summary returns, typically submitted every two months. However, an operational gap has expanded between the high-speed data capabilities of modern Enterprise Resource Planning (ERP) systems and the traditional post-hoc tax reporting model.
Following the success of PAYE Modernisation (PMOD) in 2019, which embedded real-time payroll taxation directly into operational workflows, Revenue is applying similar principles to commercial transactions. The strategic objective is twofold: to streamline compliance for tax-compliant businesses by embedding tax administration into natural business processes, and to enhance Revenue's capacity to combat VAT fraud and shadow economy activities.
Ireland's digital tax strategy leverages structured electronic invoicing as the data vehicle and real-time Digital Reporting Requirements (DRR) as the compliance validation mechanism. By doing so, Ireland aligns itself with international best practices endorsed by the OECD's Tax Administration 3.0 model and positions its domestic business ecosystem to capture the productivity benefits of end-to-end automation.
Historical evolution & EU/global context
The legislative origin of Ireland's modern e-invoicing journey dates back to the transposition of Directive 2014/55/EU into Irish law via Statutory Instrument No. 258/2019. This established a mandatory framework for Irish public bodies to receive and process electronic invoices compliant with European Standard EN 16931. While Business-to-Government (B2G) e-invoicing became active across public sector bodies in April 2019, adoption remained voluntary for commercial suppliers.
In October 2023, Revenue launched a landmark public consultation paper, Modernising Ireland's Administration of Value-Added Tax, inviting feedback from businesses, tax advisors, and technology providers on moving B2B and B2G trade into real-time digital reporting supported by e-invoicing. The consultation summary, published in June 2024, demonstrated strong industry support for compliance efficiency, provided that businesses were given adequate preparation time and clear technical standards.
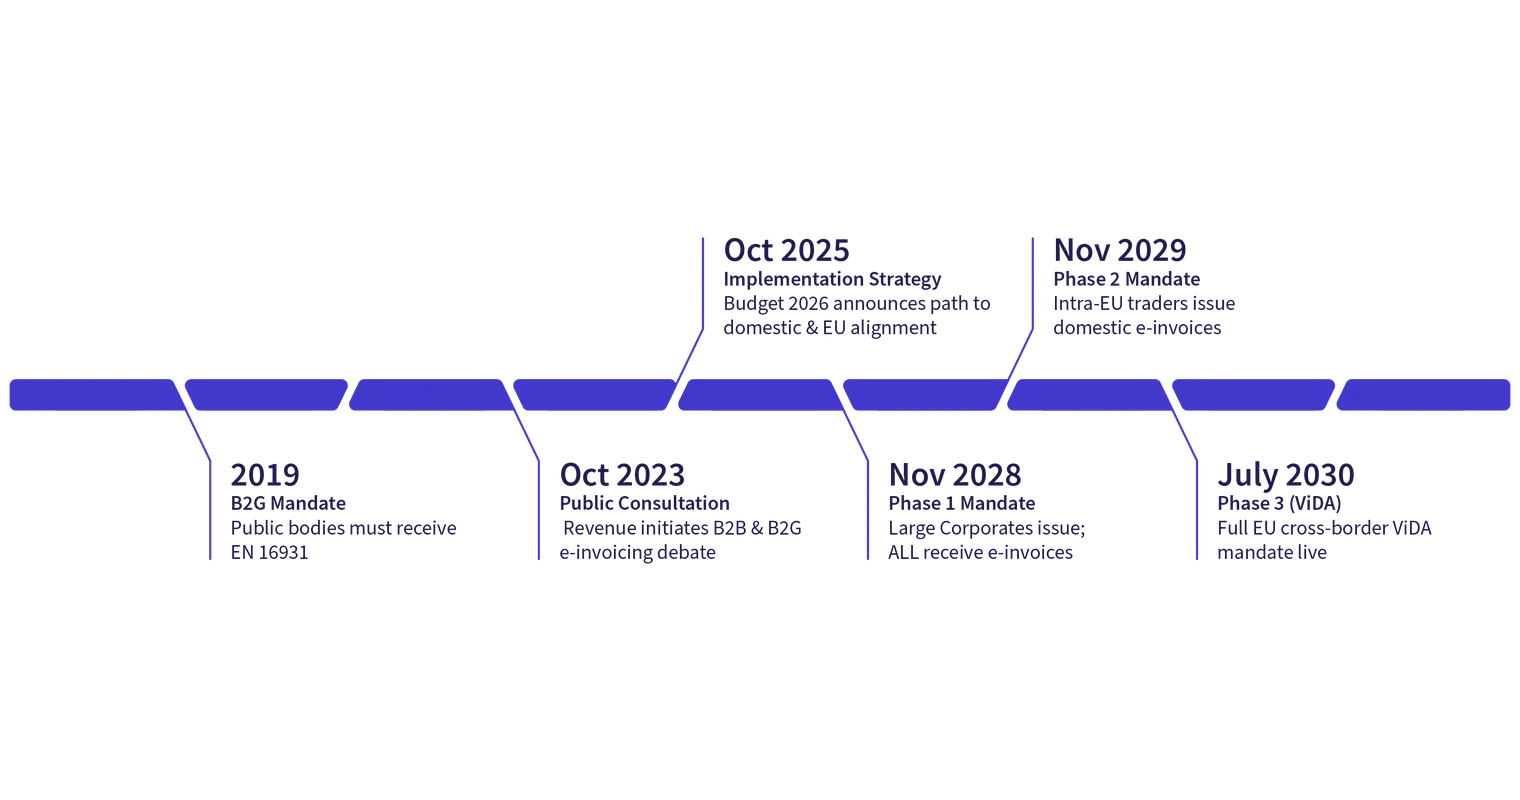
Ireland's national roadmap is directly anchored to the EU's VAT in the Digital Age (ViDA) legislative package adopted by the EU Council in March 2025. By designing its domestic B2B rollout to mature alongside European milestones, Revenue ensures that Irish enterprises will not face duplicate system changes when intra-EU digital reporting becomes compulsory across all Member States in July 2030.
Compliance timeline
The implementation of mandatory e-invoicing and real-time digital reporting in Ireland follows a three-phase rollout designed to build capacity incrementally across the economy.
Implementation date | Transaction scope | Business category affected | Compliance obligation |
Current status | B2G (Public procurement) | All public sector bodies | Mandatory reception of EN 16931 e-invoices (issuance remains voluntary for suppliers). |
1 November 2028 | Domestic B2B | Large Corporate taxpayers | Mandatory issuance of structured e-invoices and real-time e-reporting to Revenue. |
1 November 2028 | Domestic B2B | All VAT-registered businesses | Mandatory capability to receive structured e-invoices from suppliers. |
1 November 2029 | Domestic B2B | Businesses engaged in intra-EU trade | Mandatory domestic e-invoicing issuance and real-time e-reporting to Revenue. |
1 July 2030 | Intra-EU B2B | All EU cross-border trading entities | Full EU ViDA compliance: mandatory e-invoicing and digital reporting within 10 days of transaction. |
Legal framework
The primary statutory foundation for Value-Added Tax in Ireland is the Value-Added Tax Consolidation Act 2010 (as amended). Section 66 of the Act establishes the general rules regarding invoice issuance, content, and record-keeping.
The legal transition to mandatory e-invoicing and real-time digital reporting is governed by legislative enactments introduced through the Finance Acts:
European Union (Electronic invoicing in public procurement) regulations 2019 (S.I. No. 258/2019): Transposed Directive 2014/55/EU into Irish law, creating the statutory mandate for public bodies to accept EN 16931 structured e-invoices.
Finance act amendments (VAT modernisation): Enacts statutory powers enabling Revenue to prescribe electronic formats, digital reporting data subsets, real-time transmission windows, and mandatory reception obligations for commercial entities.
EU ViDA Directive Integration: Amends domestic VAT legislation to implement mandatory structured e-invoicing and the elimination of monthly VIES (VAT Information Exchange System) returns for cross-border EU trade by 1 July 2030.
Official legal texts and technical updates are published through the Irish Statute Book and the Revenue Tax and Duty Manuals.
Authorities
The administrative oversight of Ireland's e-invoicing and digital tax landscape is managed by two primary state authorities:
Office of the Revenue Commissioners (Cáin agus Custaim na hÉireann): The primary tax authority responsible for policy operationalisation, technical specifications, real-time data ingestion, compliance audits, and enforcement.
Office of Government Procurement (OGP): Acting as Ireland's National Peppol Authority, the OGP oversees the governance, accreditation, and operational standards of the Peppol framework across public and private sector domain interactions.
Department of Finance: Leads the legislative strategy and policy direction for VAT Modernisation through annual Finance Bills presented to Dáil Éireann.
Scope of the mandate
Ireland's e-invoicing and e-reporting requirements distinguish clearly between business categories, trade channels, and transaction types:
Business-to-Business (B2B)
Domestic B2B: Mandatory e-invoicing issuance and real-time digital reporting will apply to Large Corporates from 1 November 2028, extending to all intra-EU trading taxpayers in November 2029, and eventually covering the wider business community. Crucially, all VAT-registered businesses must be capable of receiving e-invoices by 1 November 2028.
Cross-border B2B: Intra-EU transactions will become subject to mandatory structured e-invoicing and real-time DRR by 1 July 2030 under EU ViDA rules, replacing traditional VIES reporting.
Business-to-Government (B2G)
Public bodies in Ireland have been legally required to receive and process electronic invoices conforming to European standards since April 2019. Under the VAT Modernisation programme, B2G transactions are fully integrated into the domestic real-time e-reporting architecture.
Business-to-Consumer (B2C)
Domestic B2C transactions are explicitly excluded from the initial e-invoicing and real-time reporting mandates. B2C sales remain governed by standard point-of-sale accounting and periodic VAT return summary rules.
E-invoicing requirements
Under the modernised framework, an electronic invoice is legally defined as an invoice issued, transmitted, and received in a structured electronic format that allows for its automated processing.
Format standards
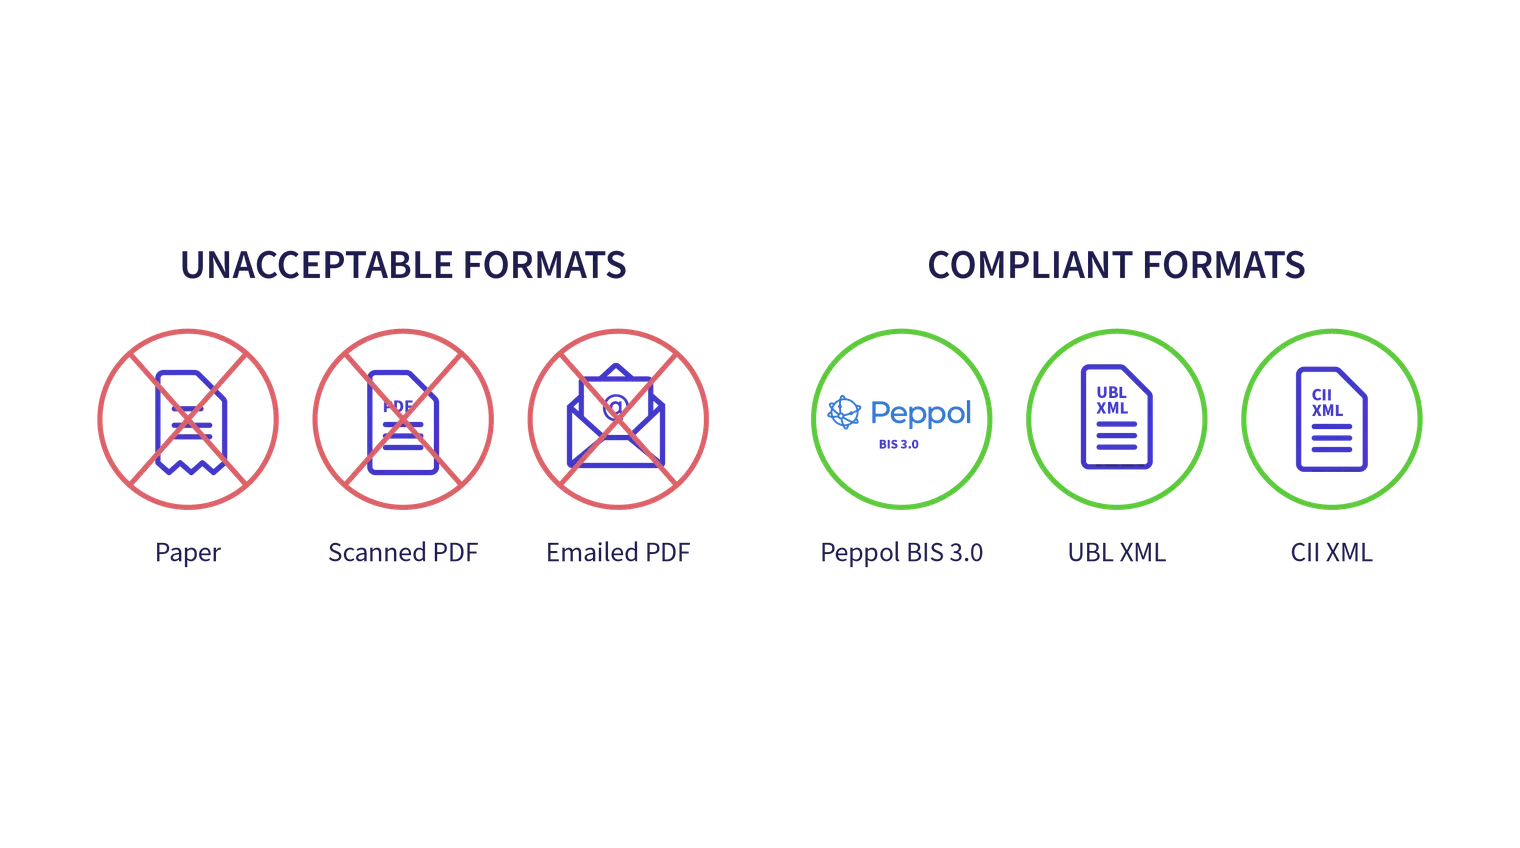
Traditional paper invoices, scanned documents, and standard unstructured PDF files do not comply with legal requirements. In-scope e-invoices must conform to European Standard EN 16931 using approved syntaxes:
UBL (universal business language): XML structured data representation.
Peppol BIS Billing 3.0: The primary operational specification utilized across the Irish market.
CII (Cross industry invoice): XML structured format aligned with EN 16931 rules.
Issuance timelines and content
Suppliers subject to the mandate must issue structured e-invoices within statutory timeframes (within 10 days of supply for cross-border trade under ViDA). E-invoices must include all standard VAT data items under Section 66 of the VAT Consolidation Act 2010, alongside enhanced mandatory fields such as buyer identification details, explicit line-item tax rates, and Peppol Endpoint IDs.
Electronic archiving
In accordance with Section 84 of the Value-Added Tax Consolidation Act 2010, businesses must store electronic invoices and associated digital transaction logs for a minimum retention period of 6 years. Invoices must be retained in their native structured XML format, ensuring authenticity of origin, integrity of content, and continuous legibility throughout the retention timeframe.
E-reporting requirements
Real-time Digital Reporting Requirements (DRR) run in tandem with structured e-invoicing. Rather than compiling aggregate totals at two-month intervals, taxpayers will transmit continuous transactional data directly to Revenue's digital administration infrastructure.
Mechanics and data subset
Upon the issuance of a structured e-invoice, the taxpayer's system automatically extracts and transmits a defined subset of transactional data to Revenue. Key reported fields include:
Supplier and customer VAT identification numbers.
Unique invoice identification number and issue date.
Taxable base amount per VAT rate category.
Total VAT amount payable or refundable.
Specific VAT exemptions or reverse charge indications.
Transmission frequency
Transmission occurs in real-time or near-real-time (typically within two days of invoice issuance domestic, and mandated within 2 days under proposed ViDA cross-border rules). This automated data pipeline removes the requirement for monthly or quarterly VIES filings, significantly reducing administrative overheads for compliant businesses.
Technical architecture
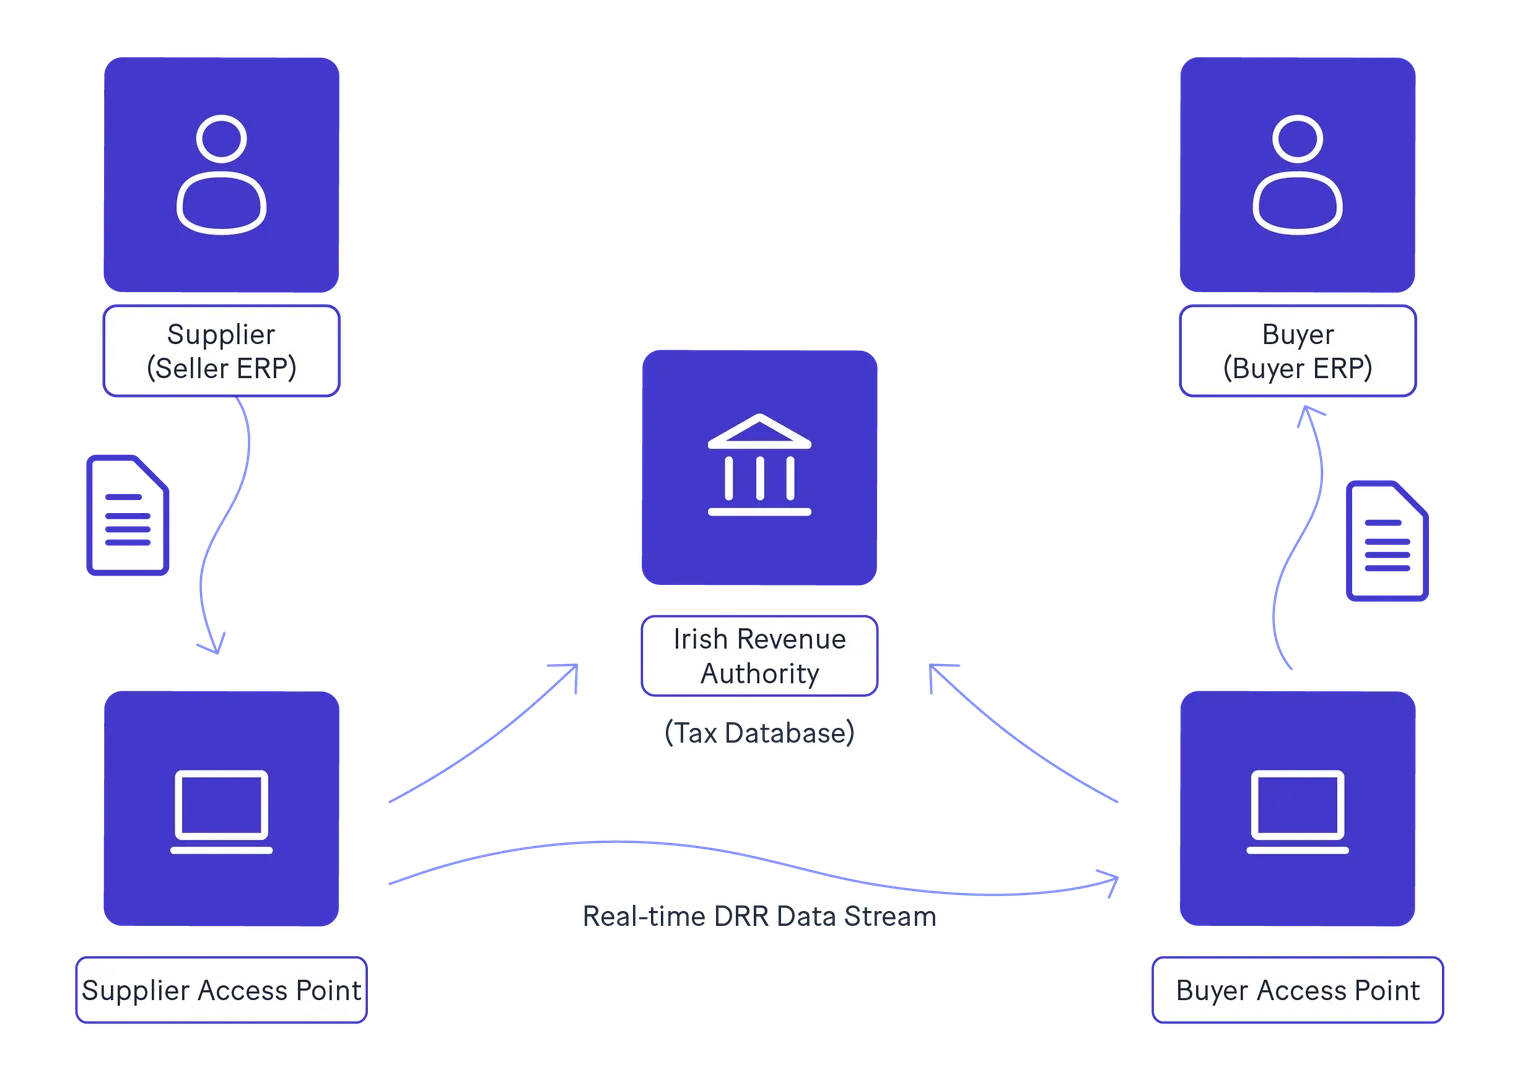
Ireland has selected a decentralised exchange model backed by standard interoperability layers, leveraging the established Peppol 4-corner network for commercial document transfer alongside direct API reporting to Revenue.
The Peppol 4-corner model
Corner 1 (supplier): Generates structured transaction data within its ERP or billing software.
Corner 2 (supplier's access point): Validates the XML document against EN 16931 syntax rules and transmits it securely over the Peppol network.
Corner 3 (buyer's access point): Receives the secure document and delivers it into the buyer's system.
Corner 4 (buyer): Processes the structured e-invoice automatically for accounts payable approval and ledger posting.
Simultaneously, the Accredited Service Provider (Access Point) streams the required subset of transactional tax data directly to Revenue's ingestion portal via secure REST APIs, ensuring compliance without interrupting commercial document delivery.
Penalties
Failure to adhere to Ireland's e-invoicing and real-time reporting regulations carries significant financial and operational legal risks under the Value-Added Tax Consolidation Act 2010:
Administrative fines: Under Section 115 of the Act, failure to issue a compliant tax invoice or retain mandatory electronic records exposes taxpayers to statutory civil penalties of up to €4,000 per breach, alongside penalties for failure to transmit required e-reporting data.
Disallowance of input VAT recovery: Taxpayers receiving non-compliant invoices (such as plain paper or PDF documents from suppliers subject to the mandate) risk having their input VAT deduction claims disallowed by Revenue during compliance interventions, leading to severe cash flow adjustments and interest assessments.
Loss of 0% intra-EU rating: Under EU ViDA rules taking effect in July 2030, failure to comply with e-invoicing and real-time reporting invalidates access to the 0% VAT rate on cross-border intra-EU supplies, subjecting transactions to local taxation errors.
How businesses can prepare
To navigate Ireland's digital tax transformation efficiently, organisations should implement a structured readiness roadmap:
Audit current invoicing workflows: Map all Order-to-Cash (O2C) and Procure-to-Pay (P2P) channels to identify reliance on manual entry, paper documents, or unencrypted PDF attachments.
Evaluate software capabilities: Consult with software vendors to ensure internal ERP, accounting, and billing systems are capable of generating and receiving structured XML documents conforming to EN 16931 and Peppol BIS Billing 3.0 standards.
Prepare for mandatory reception by 2028: Establish receiving capabilities early. Even if your business is not required to issue e-invoices in Phase 1 (November 2028), you are legally mandated to accept structured e-invoices from large corporate suppliers.
Cleanse master data: Conduct a thorough review of customer and supplier master records, ensuring VAT registration numbers, legal entity addresses, and Peppol Endpoint IDs are fully accurate and up to date.
Partner with an accredited Peppol Access Point: Engage an experienced certified e-invoicing service provider to manage secure network routing, automated syntax validation, and continuous real-time reporting to Revenue.
Conclusion
Ireland's move to mandatory B2B e-invoicing and real-time digital reporting represents a major evolution in digital tax administration. By leveraging the Peppol network, European Standard EN 16931, and a phased implementation roadmap running from November 2028 to July 2030, Revenue is establishing a modern framework that reduces administrative friction for compliant taxpayers while safeguarding public finances.
Early preparation is key to operational continuity. By auditing internal systems, upgrading billing software, and engaging accredited Peppol Access Point partners, businesses operating in Ireland can achieve seamless compliance, automate financial workflows, and capture the full operational benefits of end-to-end digital trade.
FAQ
No. Standard PDF documents, emailed scanned files, and paper invoices do not meet the legal definition of an electronic invoice under the VAT Modernisation framework. Invoices must be issued in structured electronic formats compliant with EN 16931 (such as Peppol BIS 3.0 UBL XML).
