This article was updated on 18 August 2026 following the official submission of Draft Law No. 8815, which introduces mandatory domestic B2B e-invoicing in Luxembourg. This article incorporates the finalised implementation timetable for mandatory domestic B2B e-invoicing, the explicit removal of recipient consent rules, technical specifications for Peppol BIS Billing 3.0, and alignment with the European Union's VAT in the Digital Age (ViDA) initiative.
Introduction and digital tax strategy
The Grand Duchy of Luxembourg is accelerating its digital tax transformation, transitioning from voluntary digital adoption to an enforceable structured electronic invoicing regime across the private sector. This reform forms a core pillar of the Luxembourg Government’s broader digitalisation strategy, aimed at modernising administrative workflows, enhancing commercial competitiveness, and curbing the national Value Added Tax (VAT) gap.
The strategic rationale behind Luxembourg's mandate focuses on operational efficiency, system interoperability, and legal harmonisation. Rather than establishing a proprietary, centralised clearance platform that creates administrative friction for multinational businesses, Luxembourg is leveraging the open, decentralised Peppol delivery network.
By mandating structured, machine-readable data exchange based on common European specifications, the government aims to increase productivity across the private sector while establishing an infrastructure that natively aligns with future European Union digital reporting standards.
Historical evolution and EU/global context
To fully understand Luxembourg's B2B mandate, organisations must examine its legislative progression over the past decade. Luxembourg’s journey towards mandatory e-invoicing began in response to European Union initiatives aimed at preventing market fragmentation in public procurement.
Date | Historical evolution milestone |
2014 | EU Directive 2014/55/EU adopted (establishing semantic standard EN 16931). |
16 May 2019 | Law of 16 May 2019 enacted, transposing Directive 2014/55/EU into Luxembourg law. |
13 December 2021 | Law of 13 December 2021 amended the 2019 Law and established the phased B2G roadmap. |
18 May 2022 | Mandatory B2G e-invoicing Phase 1 active for large enterprises. |
18 October 2022 | Mandatory B2G e-invoicing Phase 2 active for medium-sized enterprises. |
18 March 2023 | Mandatory B2G e-invoicing Phase 3 active for all businesses (SMEs and micro-enterprises). |
17 / 30 July 2026 | Government Council approval (17 July) and parliamentary filing (30 July) of Draft Law No. 8815. |
1 January 2028 | Mandatory B2B reception capability required for all Luxembourg-established businesses. |
1 July 2028 | Mandatory B2B issuance Phase 1 active for large and medium-sized enterprises. |
1 January 2029 | Mandatory B2B issuance Phase 2 active for small enterprises, micro-enterprises, and sole traders. |
1 July 2030 | EU ViDA cross-border digital reporting requirements (DRR) take effect across Member States. |
The B2G foundation (2019–2023)
The legal baseline was set by the Law of 16 May 2019, which transposed EU Directive 2014/55/EU into domestic law. This established that public sector contracting authorities (pouvoirs adjudicateurs) must be capable of receiving structured electronic invoices adhering to European standard EN 16931-1:2017.
To enforce supplier-side compliance, the Luxembourg Parliament enacted the Law of 13 December 2021 (amending the Law of 16 May 2019), published in the official gazette (Mémorial A N° 869). This act established a mandatory, phased B2G issuance roadmap for all economic operators executing public procurement and concession contracts:
18 May 2022: Large economic operators (>250 employees, balance sheet >€20m, or net turnover >€40m).
18 October 2022: Medium economic operators (50–249 employees, balance sheet €4.4m–€20m, or net turnover €8.8m–€40m).
18 March 2023: Small, micro, and newly created economic operators (<50 employees, balance sheet <€4.4m, or net turnover <€8.8m).
Simultaneously, the Grand-Ducal Regulation of 13 December 2021 legally established the Peppol network as the official, common delivery network for all public entities in Luxembourg.
Non-resident suppliers and cross-border B2G obligations
A critical aspect of Luxembourg's B2G framework is its extraterritorial application to non-established suppliers. International vendors executing public contracts in Luxembourg (for instance, German, Belgian, or French contractors) have been legally bound since 2022-2023 to transmit structured e-invoices via Peppol. Paper invoices and unstructured PDFs are strictly rejected by public contracting authorities.
Market research conducted by OpinionWay on behalf of Banqup Group revealed that during the initial rollout, nearly 80% of micro-enterprises were unaware of the incoming mandatory e-invoicing rules, and 92% did not utilise dedicated e-invoicing systems. This highlighted the urgent necessity for automated, user-friendly solutions like Banqup to bridge the compliance gap for both domestic and foreign suppliers.
The B2B expansion (2026–2029)
Building upon the successful adoption of Peppol across B2G transactions, the Minister of Finance officially submitted Draft Law No. 8815 (Projet de Loi n° 8815) to Parliament on 30 July 2026 (following Council of Government approval on 17 July 2026). Draft Law No. 8815 amends the Law of 16 May 2019 and the Luxembourg VAT Law of 12 February 1979 (Loi modifiée du 12 février 1979 concernant la taxe sur la valeur ajoutée), bringing domestic private-sector transactions into mandatory scope.
EU and global context: Comparing regulatory models
Luxembourg’s strategy mirrors that of neighbouring Belgium, which progressed sequentially from B2G e-invoicing to a Peppol-based B2B mandate. This approach contrasts sharply with clearance or central platform models seen in France (the dual Y-model using Partner Dematerialisation Platforms / Portail Public de Facturation) or Poland (Krajowy System e-Faktur - KSeF).
Luxembourg has deliberately avoided creating a centralised government clearing system. Instead, it relies on a decentralised CTC exchange framework. For cross-border transactions, Luxembourg’s roadmap natively positions established entities to comply with the European Commission's VAT in the Digital Age (ViDA) package, which mandates harmonised Digital Reporting Requirements (DRR) and structured e-invoicing for intra-EU B2B supplies starting 1 July 2030.
Complete compliance timeline
The complete historical and prospective compliance schedule for e-invoicing in Luxembourg is detailed below:
Date | Scope and transaction level | Mandatory obligation | Target group / entity threshold |
16 May 2019 | B2G (Public Sector) | Reception capability | All public sector entities and contracting authorities. |
18 May 2022 | B2G (Public Procurement) | Issuance and transmission | Large suppliers (>250 staff) |
18 October 2022 | B2G (Public Procurement) | Issuance and transmission | Medium suppliers (50–249 staff) |
18 March 2023 | B2G (Public Procurement) | Issuance and transmission | All remaining suppliers |
17 July 2026 | Legislative | Draft Law Approval | Approval of Draft Law No. 8815 by the Government Council (Conseil de Gouvernement). |
30 July 2026 | Legislative | Parliamentary Submission | Submission of Draft Law No. 8815 to Parliament (Chambre des Députés). |
1 January 2028 | Domestic B2B | Mandatory Reception | All taxable persons established in Luxembourg must be able to receive EN 16931-compliant e-invoices. |
1 July 2028 | Domestic B2B | Mandatory Issuance (Phase 1) | Large and Medium Enterprises established in Luxembourg must issue e-invoices complying with EN 16931. |
1 January 2029 | Domestic B2B | Mandatory Issuance (Phase 2) | The obligation extends to small and Micro Enterprises |
1 July 2030 | Intra-EU Cross-Border | EU ViDA Digital Reporting | All taxable entities engaged in intra-Community supplies and acquisitions. |
Legal framework
Luxembourg’s e-invoicing architecture is governed by four primary legal instruments:
Draft Law No. 8815 (Projet de loi n° 8815 relatif à la facturation électronique et à la TVA à l’ère numérique, submitted 30 July 2026): Amends the Law of 16 May 2019 and the Luxembourg VAT Law of 12 February 1979. It mandates structured domestic B2B e-invoicing, establishes the phased reception and issuance roadmap (2028–2029), and explicitly removes the legal requirement for prior recipient consent for issuing structured e-invoices once an entity falls under the mandatory issuance scope.
Law of 13 December 2021 (Mémorial A N° 869): Amends the Law of 16 May 2019 by defining electronic invoices, economic operator size classes, and mandating automated Peppol delivery channels for public contracts.
Law of 16 May 2019 (Mémorial A N° 345 - Consolidated Text): Transposed EU Directive 2014/55/EU into domestic law, setting the semantic standard EN 16931 for public procurement.
Grand-Ducal Regulation of 13 December 2021 (Mémorial A N° 870): Designates the Peppol delivery network as the common national network for automated e-invoice transmission and defines technical alternatives via the Government portal MyGuichet.lu.
Competent authorities
The governance, technical maintenance, and supervision of Luxembourg’s e-invoicing ecosystem are divided among four main bodies:
Administration de l'Enregistrement, des Domaines et de la TVA (AED): Luxembourg’s indirect tax authority. The AED administers VAT registrations, oversees invoice compliance under the Luxembourg VAT Law of 12 February 1979, and conducts statutory audits.
Ministère de la Digitalisation: Oversees the strategic implementation of the national electronic invoicing dossier, formulating policy, draft legislation, and economic support measures.
Peppol Authority Luxembourg: Operates under the auspices of the Ministry for Digitalisation, governing local Peppol service providers, participant identifiers, and enforcing OpenPeppol technical standards across local Access Points.
Centre des Technologies de l'Information de l'État (CTIE): The State Information Technology Centre. The CTIE operates the central infrastructure, including the State’s official Peppol Access Point, and maintains the technical forms on MyGuichet.lu.
Scope of the mandate
The applicability of Luxembourg's e-invoicing framework varies strictly by transaction class and established tax status:
Transaction scope | |||
Transaction type | E-invoicing status | Format required | Delivery network |
B2G Domestic | MANDATORY (Active) | EN 16931 (UBL) | Peppol / MyGuichet.lu |
Cross-Border B2G | MANDATORY (Active) | EN 16931 (UBL) | Peppol / MyGuichet.lu |
B2B Domestic | MANDATORY (2028-29) | EN 16931 (UBL) | Peppol Access Points |
B2C Domestic | EXEMPT | Paper / PDF | Unrestricted| |
Cross-Border B2B | EXEMPT (Until ViDA) | Optional | Unrestricted (ViDA '30) |
1. Business-to-Government (B2G)
Status: Fully mandatory across all public procurement tiers since 18 March 2023.
Scope: Applies to all contracts executed with state ministries, regional municipalities (communes), and public law entities (organismes de droit public).
Cross-border and extraterritorial mandate: This obligation applies strictly to both domestic companies and non-established foreign suppliers issuing invoices from outside Luxembourg to a Luxembourgish public sector buyer (pouvoirs adjudicateurs). International vendors (for instance, German, Belgian, or French contractors) executing public contracts in the Grand Duchy are legally bound to transmit structured electronic invoices adhering to EN 16931 via the Peppol network or MyGuichet.lu. Paper invoices and unstructured PDFs are strictly prohibited and will be rejected automatically by Luxembourgish public contracting authorities.
2. Domestic Business-to-Business (B2B)
Status: Mandatory rollout (1 January 2028 – 1 January 2029) under Draft Law No. 8815.
Scope: Applies to domestic B2B supplies of goods and services where both the supplier and recipient are taxable persons established in Luxembourg.
Consent rule: Draft Law No. 8815 explicitly repeals the requirement for prior recipient consent. Recipients must accept compliant structured e-invoices once the supplier's mandatory phase is active.
3. Business-to-Consumer (B2C)
Status: Fully exempt.
Scope: Transactions where the buyer is a private consumer fall outside the structured e-invoicing mandate. Paper invoices or unstructured PDFs remain permissible subject to recipient agreement.
4. Cross-border B2B transactions
Status: Exempt from the domestic mandate.
Scope: Invoices issued to or received from non-established foreign entities are exempt from domestic B2B e-invoicing obligations. Cross-border B2B transactions will remain subject to existing international VAT rules until 1 July 2030, when the EU ViDA harmonised digital reporting requirements take effect.
E-invoicing technical requirements
To be legally valid, electronic invoices in Luxembourg must satisfy strict semantic, technical, and retention criteria:
Semantic norms and technical syntax
Electronic invoices must comply with European Standard EN 16931-1:2017. Acceptable technical syntaxes defined under European Commission directives include:
UBL 2.1 (Universal Business Language): ISO/IEC 19845:2015 syntax (the underlying standard for Peppol BIS Billing 3.0).
UN/CEFACT CII (Cross Industry Invoice): XML syntax.
Primary national specification
The primary syntax utilised throughout Luxembourg is Peppol BIS Billing 3.0 (a Core Invoice Usage Specification - CIUS compliant with EN 16931). Luxembourg deliberately avoids introducing proprietary national field customisations, ensuring seamless cross-border compatibility.
Alternative manual entry channels
To prevent digital exclusion for small or low-volume micro-enterprises lacking an automated ERP Access Point, the government provides alternative manual entry solutions via MyGuichet.lu:
Manual web form: A secure online portal where users manually enter invoice fields, generating a compliant XML structure transmitted via the CTIE Access Point.
XML upload form: An online interface allowing entities to upload a pre-generated compliant XML document for manual submission into the public infrastructure.
Statutory archiving requirements
Under Luxembourg commercial law (Code de Commerce) and the Luxembourg VAT Law of 12 February 1979, electronic invoices must be retained for a minimum statutory period of 10 years.
Legal original: Only the structured XML document constitutes the legally binding original invoice.
Integrity and authenticity: Must be maintained throughout the 10-year period via secure electronic archiving solutions (Systèmes d'Archivage Électronique - SAE) or certified Peppol Access Point archiving mechanisms.
E-reporting status and strategy
Luxembourg has adopted a clear, single-track strategy focusing on e-invoicing without a domestic real-time e-reporting regime:
No domestic CTC real-time reporting: Unlike France (which combines B2B e-invoicing with mandatory e-reporting for B2C and cross-border transactions), Luxembourg is not introducing a domestic real-time e-reporting mechanism.
No centralised fiscal clearance: Suppliers are not required to transmit real-time transaction data directly to the AED before or immediately after issuing an invoice.
Cross-border alignment (EU ViDA): Real-time transactional reporting will only be introduced for cross-border B2B supplies effective 1 July 2030, aligning with the EU ViDA Digital Reporting Requirements (DRR) framework.
Technical architecture: Decentralised Peppol 4-corner network
Luxembourg’s e-invoicing architecture relies on the Peppol 4-corner network, operated as a decentralised exchange model
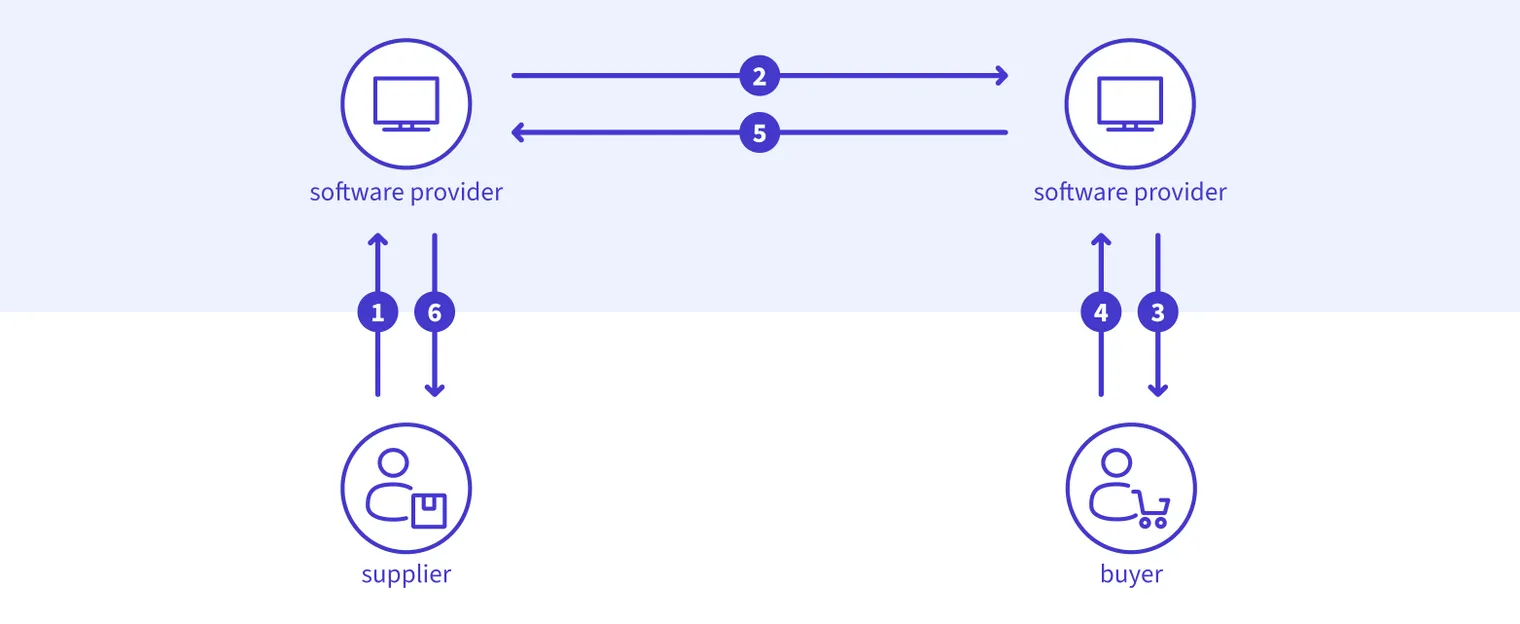
Corner 1 (Supplier): The seller generates invoice data within their ERP or accounting software.
Corner 2 (Supplier's certified Peppol Access Point): Translates data into Peppol BIS Billing 3.0 UBL XML, validates syntax, queries the SML/SMP directory, and transmits the document securely.
Corner 3 (Buyer's certified Peppol Access Point): Receives the encrypted XML document, validates its compliance against EN 16931 rules, and routes it to the buyer. (For public sector entities, CTIE operates as the central Corner 3 Access Point).
Corner 4 (Buyer): The recipient ingests structured XML data automatically into their accounts payable workflow.
Addressing and Peppol participant identifiers
In Luxembourg, Peppol network addressing relies on standardised Participant IDs registered under Peppol Codelist 9938 (LU:VAT):
VAT-based identifier: 9938:lu10061242 (Format: 9938:lu + 8-digit VAT number).
National identity number identifier: 9938:12345678910 (11-digit national identification number from the répertoire des personnes morales).
Penalties and non-compliance consequences
Non-compliance with Luxembourg's e-invoicing rules carries serious administrative and commercial risks:
Public procurement invalidation (B2G): Public authorities are legally prohibited from processing non-compliant invoices (e.g., paper or unstructured PDFs). Non-compliant submissions are automatically rejected, leading to delayed payments.
VAT deduction challenges (B2B): Under the amended Luxembourg VAT Law of 12 February 1979, an invalid invoice structure may compromise the recipient's right to claim input VAT deduction, exposing both parties to tax audit adjustments.
Administrative fines: The AED possesses statutory authority under Luxembourg tax law to issue administrative fines for non-compliance with statutory invoicing and record-keeping mandates.
How businesses can prepare
To ensure full compliance ahead of the 1 January 2028 reception mandate and subsequent issuance deadlines, businesses operating in Luxembourg should take the following strategic steps:
Audit master data quality: Ensure all supplier and customer records contain valid Luxembourg VAT numbers and 11-digit legal entity identifiers to enable reliable Peppol directory addressing.
Review accounting and ERP infrastructure: Assess whether current software can generate and ingest EN 16931-compliant XML syntax (Peppol BIS Billing 3.0 UBL).
Partner with an accredited Peppol Access Point: Engage an established service provider, such as the Banqup Group, which operates an accredited Peppol Access Point, to connect systems smoothly to the 4-corner network.
Prioritise reception readiness (1 January 2028): Configure accounts payable systems to process incoming structured electronic invoices automatically, eliminating reliance on PDF optical character recognition (OCR).
Conduct early interoperability testing: Utilise the CTIE test environment directory (test-directory.peppol.eu) to validate electronic document workflows before mandatory issuance dates take effect.
Conclusion
Luxembourg’s transition to mandatory domestic B2B e-invoicing marks a significant milestone in its digital tax strategy. By leveraging the Peppol 4-corner network and aligning with EN 16931, the Grand Duchy is establishing a modern, highly interoperable framework that prepares local enterprises for the EU's 2030 ViDA initiatives.
With the first mandatory reception deadline set for 1 January 2028, proactive planning is essential. Organisations that evaluate their ERP infrastructure, clean their master data, and partner with accredited Access Point providers early will ensure full compliance while unlocking operational efficiencies across their supply chain.