This article was updated on 31 August 2026 to reflect the latest administrative decisions issued by the Inland Revenue Board of Malaysia (Lembaga Hasil Dalam Negeri Malaysia - LHDNM). It incorporates the raised mandatory compliance threshold of RM 3 million (exempting businesses below this turnover), the extended interim grace period running through 31 December 2027 for taxpayers with revenues between RM 3 million and RM 5 million, and updated technical guidance on the Peppol International (PINT) localised model (PINT-MY).
Introduction & digital tax strategy
The Malaysian government is undertaking a strategic overhaul of its national tax administration infrastructure to accelerate the growth of the digital economy and curb the shadow economy. Aligned with the Twelfth Malaysia Plan (12MP), Malaysia’s five-year national development plan covering 2021–2025, which prioritises the modernisation of digital public services, the national e-invoicing and e-reporting framework establishes near-real-time validation of transactional data.
Through this initiative, tax authorities aim to streamline tax administration, reduce manual processing inefficiencies, improve tax compliance, and build a transparent commercial environment for businesses of all sizes.
The Malaysian framework is notable for its broad transaction scope, encompassing domestic and cross-border B2B, B2G, and B2C activities under a unified Continuous Transaction Controls (CTC) clearance model. Operating alongside this regulatory compliance mechanism is a commercial digitalisation drive led by the Malaysia Digital Economy Corporation (MDEC), which promotes the voluntary adoption of the Peppol framework to facilitate seamless, system-to-system document exchange between trading partners.
Understanding how these dual tracks - mandatory fiscal e-reporting to the Inland Revenue Board Malaysia (IRBM), also known as Lembaga Hasil Dalam Negeri Malaysia (LHDN) in Malay, and voluntary interoperable B2B e-invoicing via Peppol - intersect is essential for businesses operating in Malaysia.
Historical evolution & global context
Malaysia's path towards digital tax compliance reflects a deliberate progression from voluntary electronic reporting to a mandatory clearance infrastructure:
2015: The Malaysian Government introduces early voluntary electronic reporting initiatives to encourage digital record-keeping among corporate entities.
October 2022: The Minister of Finance formally announces the national e-invoicing policy as part of Budget 2023, charging LHDNM with implementing a phased digital reporting system.
2023: Infrastructure development begins. LHDNM outlines the central clearance model while MDEC is designated as the Peppol Authority for Malaysia, laying the foundation for standardizing electronic billing specifications across the country.
May 2024: LHDNM launches a voluntary pilot programme engaging selected enterprise taxpayers to stress-test system integration, API transmission, and validation workflows.
1 August 2024: Phase 1 of mandatory compliance takes effect for large taxpayers with annual sales exceeding RM 100 million, accompanied by an initial six-month transitional grace period.
1 January 2025: Phase 2 extends mandatory compliance to taxpayers with annual turnover between RM 25 million and RM 100 million.
1 July 2025: Phase 3 introduces mandatory compliance for taxpayers with annual turnover between RM 5 million and RM 25 million, as well as new business operations commencing operations from 2023 onwards.
Late 2025 decision & 1 January 2026 rollout: Following government policy revisions announced in late 2025 to protect micro and small enterprises, the mandatory compliance threshold is raised from RM 500,000 to RM 1 million, effective 1 January 2026. Phase 4 mandates taxpayers earning between RM 1 million and RM 5 million, backed by an extended interim relaxation period running through 31 December 2027. Taxpayers earning up to RM 1 million remain exempt.
30 August 2026 announcement: During the National Day address (Majlis Amanat Perdana Hari Kebangsaan 2026), the Prime Minister announces a further increase in the mandatory compliance threshold. Effective 1 September 2026, the mandatory e-invoicing threshold is raised to RM 3 million, formally exempting taxpayers with annual revenue or turnover of RM 3 million or less effective immediately.
Globally, Malaysia's approach blends elements of Latin American real-time clearance systems with European interoperability standards. By integrating real-time tax clearance with the international Peppol framework, Malaysia provides an operational blueprint for South-East Asian tax digitalisation.
Compliance timeline
The roll-out of Malaysia's e-reporting obligation is structured primarily around annual turnover or revenue thresholds For established taxpayers, these are determined from audited financial statements or official tax returns for the year of assessment 2022 (with pro-rated turnover for those with a changed accounting year-end in 2022).
For new businesses commencing operations from 2023 onwards, specific implementation timelines apply: operations commencing in 2023–2025 are mandated from 1 July 2026, while those commencing in 2026 onwards are mandated from 1 July 2026 or their commencement date, unless their first-year revenue is expected to be under RM 3 million, in which case the mandate applies starting 1 January in the second year after reaching that threshold
.
Mandate date | Scope mandated | Taxpayers mandated | Transitional & grace provisions |
2023 | Infrastructure & pilot setup | None (Development phase) | Voluntary engagement for pilot testing |
1 August 2024 | B2B, B2G, B2C | Turnover > RM 100 million | 6-month interim grace period |
1 January 2025 | B2B, B2G, B2C | Turnover > RM 25 million and up to RM 100 million | 6-month interim grace period |
1 July 2025 | B2B, B2G, B2C | Turnover > RM 5 million and up to RM 25 million | 6-month interim grace period; applies to post-2023 new businesses |
1 January 2026 | B2B, B2G, B2C | Turnover > RM 3 million and up to RM 5 million | Extended relaxation period permitted until 31 December 2027 |
1 September2026 | Exempted | Turnover up to RM 3 million | Exempted from mandatory compliance |
Note: Taxpayers below the mandatory thresholds may choose to participate voluntarily in the e-invoicing framework at an earlier date.
Legal framework
The legal mandate for electronic invoicing and reporting in Malaysia is anchored in national tax legislation and executive administrative guidelines issued by the tax authority:
Income Tax Act 1967 (Akta Cukai Pendapatan 1967): The primary statutory legislation governing income tax compliance, amended to empower the Director General of Inland Revenue to mandate structured electronic invoice issuance, transmission, and record retention.
LHDNM E-Invoice Guidelines: Comprehensive technical and operational rules issued under the authority of LHDNM, detailing mandatory data structures, validation workflows, cancellation rules, and self-billing conditions.
Twelfth Malaysia Plan (12MP): Executive policy framework establishing digital infrastructure modernisation goals across public and private sector administration.
The regulatory framework establishes that electronic tax invoices cleared by LHDNM carry full legal standing for tax deduction, input tax treatment, and statutory audit verification.
Authorities
Digital tax compliance in Malaysia is governed by two complementary primary institutions working alongside national ministries:
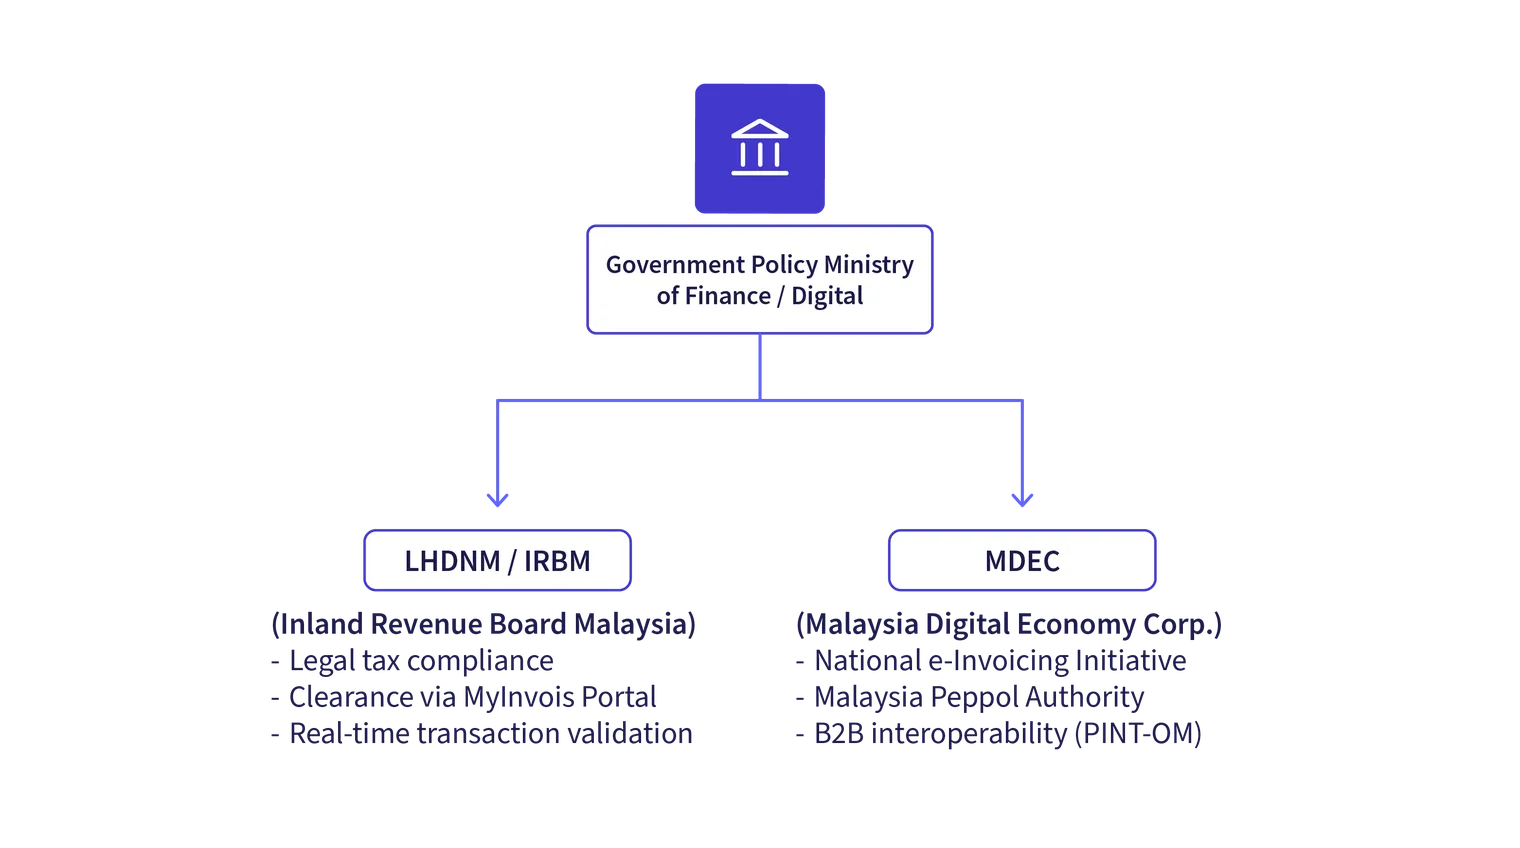
Inland Revenue Board of Malaysia (Lembaga Hasil Dalam Negeri Malaysia - LHDNM / IRBM): The national tax authority responsible for enforcing e-reporting obligations, managing the MyInvois clearance infrastructure, validating transaction submissions, and conducting compliance audits.
Malaysia Digital Economy Corporation (MDEC): The government agency under the Ministry of Digital leading national economic digitalisation. MDEC functions as the official Peppol Authority for Malaysia, overseeing Peppol Access Point accreditation, localised billing specifications, and voluntary B2B network adoption.
Ministry of Finance (MOF): The cabinet ministry overseeing national fiscal policy, revenue legislative updates, and compliance threshold adjustments.
Ministry of Digital: Executive ministry directing national digital transformation programs and supporting infrastructure initiatives.
Scope of the mandate
The e-reporting mandate applies comprehensively across domestic and international commercial operations.
In-scope transactions
Business-to-business (B2B): Commercial transactions between registered entities established in Malaysia.
Business-to-government (B2G): Commercial sales to federal, state, and local government bodies, following processing flows identical to B2B transactions.
Business-to-consumer (B2C): Retail transactions between businesses and end consumers. Where end consumers do not require a validated e-invoice for personal tax deduction purposes, suppliers may issue standard receipts and subsequently submit a consolidated e-invoice to LHDNM within seven calendar days after month-end.
Cross-border transactions: Imports and exports of goods and services. For foreign services or goods acquired from foreign entities not registered in Malaysia, local buyers must issue a self-billed e-invoice to record the transaction for domestic tax compliance.
Exemptions & exclusions
Taxpayers with an annual turnover or revenue of up to RM 3 million.
Individuals not conducting business activities.
Diplomatic missions, foreign embassies, and specific international organisations granted statutory immunity.
E-invoicing requirements
Under the LHDNM framework, an e-invoice is defined as a digital representation of a commercial transaction generated in XML or JSON format as specified by IRBM and that can be automatically processed by relevant systems. Visual renderings (such as PDF, paper, or images) do not constitute valid legal e-invoices unless accompanied by real-time LHDNM clearance metadata and an embedded QR code.
Documents in scope
Standard invoice: Commercial invoice covering sales of goods or services.
Credit note: Adjustment document issued to reduce the value of an original transaction.
Debit note: Adjustment document issued to increase the value of an original transaction.
Refund note: Formal accounting document issued by a supplier confirming a monetary payment return to the buyer.
Self-billed invoice: Invoice issued by the buyer for specific circumstances, including foreign service acquisitions, agent/dealer commissions, and agricultural procurement.
Validation workflow & 72-hour rule
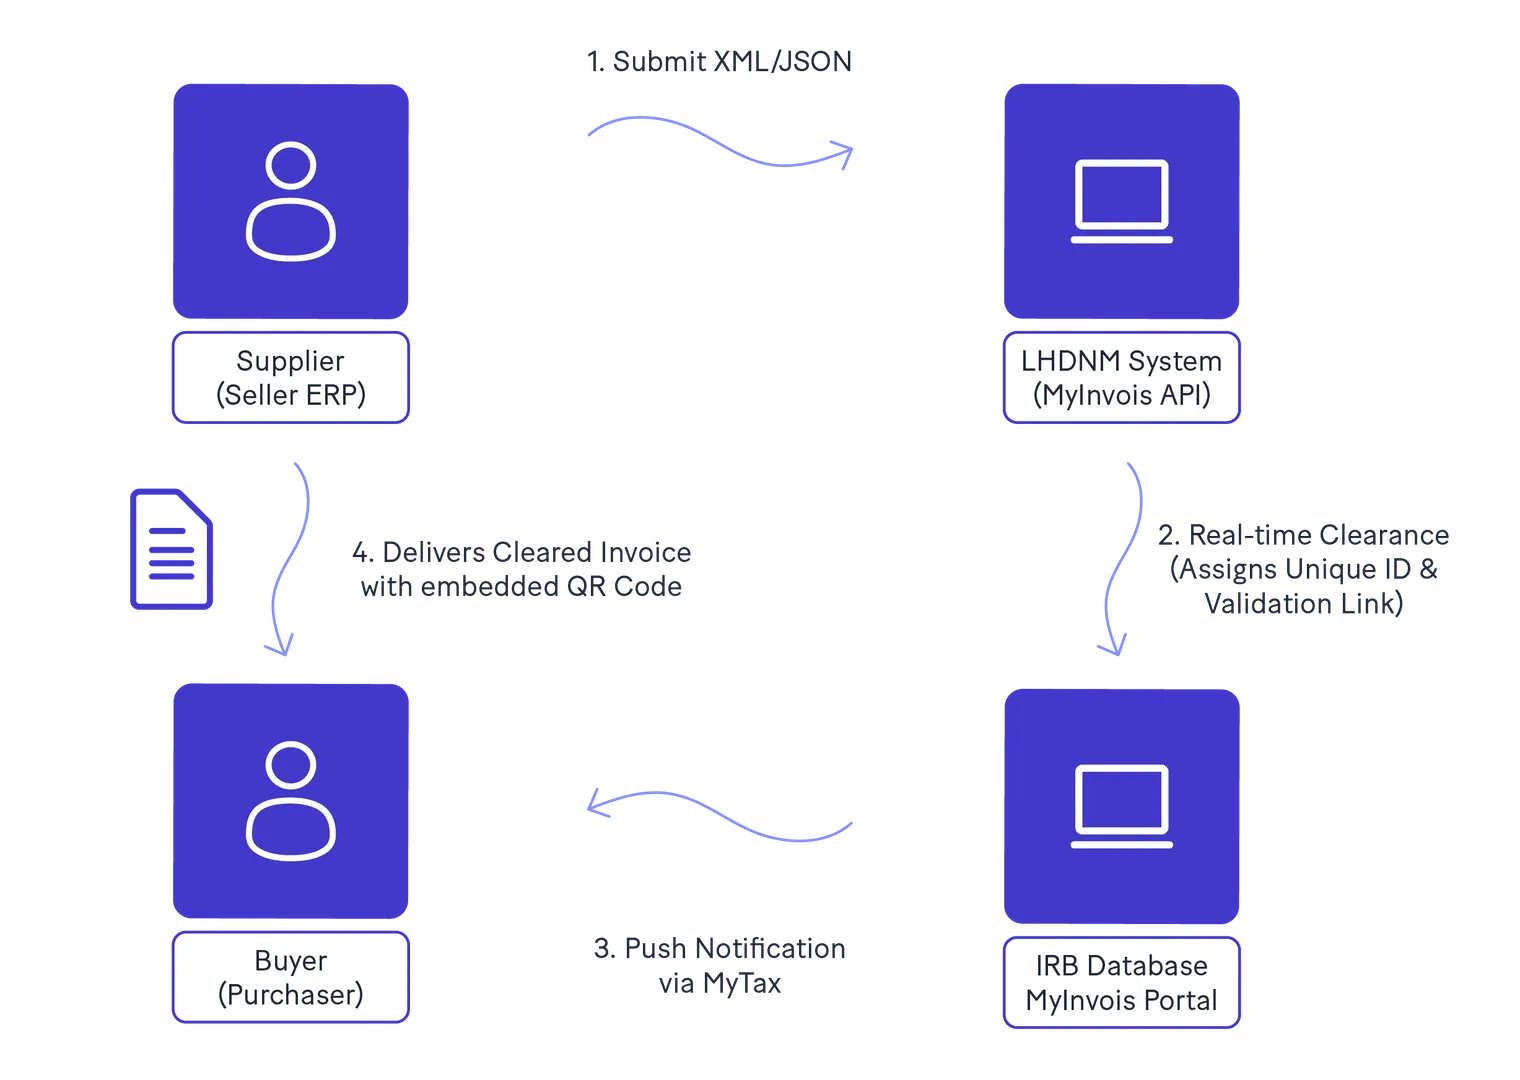
Clearance workflow: The supplier submits structured invoice data via API or the MyInvois Portal. LHDNM validates data completeness, verifies the Tax Identification Number (TIN), assigns an IRB Unique Identifier Number, and returns a validation link and QR code to the supplier.
Visual rendering & delivery: The supplier embeds the LHDNM-generated QR code into the visual invoice representation (PDF or paper) and delivers it to the buyer.
Cancellation and rejection window: The supplier or buyer may initiate cancellation or rejection of a cleared e-invoice via the MyInvois system within 72 hours of clearance, provided valid justifications are entered. Once the 72-hour window expires, corrections must be executed via adjustment notes (Credit or Debit Notes).
Archival requirements
Retention period: Taxpayers must retain complete transaction records and structured e-invoices for a minimum of 7 years from the end of the calendar year in which the accounting books relate.
Offshore storage: Electronic archiving abroad is permitted, provided pre-approval is granted by LHDNM and records can be rendered locally upon request by tax officers.
E-reporting requirements
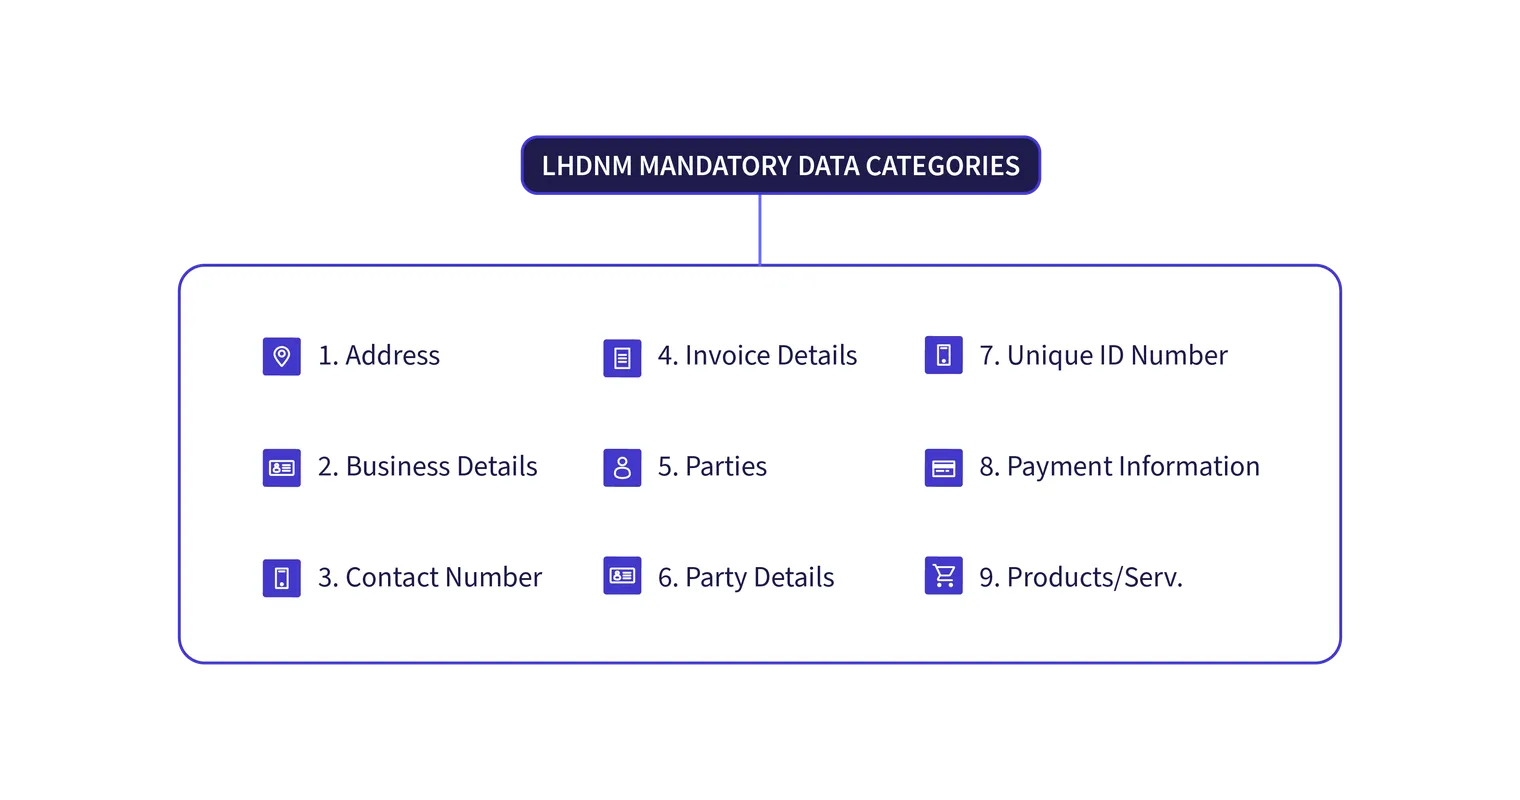
E-reporting requires the structured submission of transaction details directly to LHDNM. The system mandates 53 data fields grouped across nine operational categories to ensure legal clearance:
Core mandatory data fields
Tax identification number (TIN): Mandatory pre-validated identifier for both supplier and buyer (or general consumer TIN for B2C).
Registration numbers: Company registration number (ROC), business registration number (ROB), or passport number for foreign buyers.
SST registration number: Applicable sales and service tax registration codes.
Itemized description: Quantities, unit costs, discounts, tax rates, and tax amounts presented as separate line items.
Currency conversion: Invoices may display foreign currencies, but conversion to Malaysian Ringgit (MYR/RM) must be calculated using prescribed exchange rates where statutory tax rules dictate.
(For a detailed specification of the mandatory and optional fields, please refer to the official LHDNM e-Invoice Guideline).
Reporting mechanisms & timing
Real-time reporting: Standard B2B, B2G, and individual B2C e-invoices must be transmitted and cleared prior to issuing final documentation to the buyer.
Consolidated e-reporting: B2C merchants aggregating unrequested individual consumer receipts must compile and submit a consolidated e-invoice within 7 calendar days after the end of the transaction month.
Technical architecture
Malaysia operates a Centralised CTC Clearance Model for tax compliance, integrated with an optional Peppol 4-Corner Model for business-to-business automation.
Submission pathways
MyInvois Portal (via MyTax): A web-based interface hosted by LHDNM suited for small and medium-sized enterprises (SMEs) or low-volume issuers. Supports manual key-in and batch file uploads.
Application Programming Interface (API): A direct system-to-system integration channel designed for enterprise taxpayers and software vendors handling high transaction volumes. Inputs are processed strictly in XML or JSON format.
Digital certificates & security
API transmissions require authentication using an official Digital Certificate (.cer or .pfx format) issued by local trusted certification authorities based on the taxpayer's TIN. Digital certificates guarantee content non-repudiation, structural integrity, and origin authenticity, carrying a standard validity period of 3 years.
Peppol framework integration (PINT-MY)
To support B2B supply chain automation, MDEC governs the implementation of the Peppol network in Malaysia using the Peppol International (PINT) Billing specification, localised for Malaysian tax laws (PINT-MY).
Tax adaptation: Because Malaysia applies Sales and Service Tax (SST) rather than Value Added Tax (VAT), any VAT reference in the standard Peppol semantic specification is interpreted as SST in the Malaysian context.
Syntax standard: Uses OASIS UBL 2.1 XML structure.
Operational model: Taxpayers may exchange B2B documents via Peppol Access Points (operated by locally accredited Peppol Service Providers, or SPs), which are often integrated directly into Peppol-Ready Solution Providers (PRSP) software to facilitate seamless B2B connectivity, while concurrently executing real-time clearance via LHDNM APIs.
Penalties for non-compliance
Failure to comply with Malaysia's electronic invoicing regulations exposes businesses and corporate directors to administrative sanctions and statutory penalties under the Income Tax Act 1967.
Failure to issue an e-invoice: Under Section 120 of the Income Tax Act 1967, any person who fails to issue an e-invoice as required by law commits an offence. Upon conviction, offenders are liable to a fine of not less than RM 200 and not exceeding RM 20,000, or imprisonment for a term not exceeding 6 months, or both per violation.
Unauthorised invoice alterations: Modifying cleared e-invoices outside the formal cancellation rules or submitting fraudulent transaction data attracts severe tax audit adjustments, loss of corporate expense deductions, and potential legal prosecution.
Buyer risk: Purchases unsupported by a validated LHDNM e-invoice (or an authorized self-billed e-invoice) are disallowed as deductible expenses for corporate income tax assessment purposes.
How businesses can prepare
Compliance with the national e-invoicing mandate is an ongoing responsibility. Malaysian businesses and multinational entities operating in or entering the country should maintain a structured readiness program to ensure they are prepared to activate reporting protocols as soon as they meet the mandatory turnover threshold or as regulatory requirements evolve.
Monitor turnover & determine eligibility: Regularly assess your annual turnover against the RM 3 million threshold. If you are currently exempt, establish a monitoring process to identify the exact date your turnover crosses this threshold, as this triggers the implementation timeline.
Evaluate ERP & software architecture: Audit existing billing, point-of-sale (POS), and enterprise resource planning (ERP) systems to ensure capability for generating structured XML/JSON payloads aligned with LHDNM specifications.
Cleanse master data: Conduct a data validation exercise across customer and vendor databases to collect accurate Tax Identification Numbers (TIN), business registration numbers, and SST details.
Register on MyTax Portal: Complete first-time administrative registration on the official MyTax portal (both testing and production environments). Where applicable, formally assign your designated middleware service provider as your authorised digital intermediary to allow for API-based submission.
Obtain/manage digital certificates: Procure or renew valid 3-year digital certificates linked to your enterprise TIN to support secure API authentication and cryptographic document signing. Implement a process for proactive token/certificate renewal to avoid service interruptions.
Establish exception procedures: Define operational workflows to manage the 72-hour invoice cancellation/rejection window, credit note issuance, self-billing scenarios, and monthly consolidated e-invoicing for B2C retail lines.
Conclusion
Malaysia's e-invoicing and e-reporting framework represents a fundamental evolution in national tax compliance. By replacing legacy manual billing with real-time clearance via the central MyInvois system, LHDNM is establishing a transparent, digitalised tax environment.
While the exemption for businesses earning up to RM 3 million provides significant relief for small and micro-enterprises, all in-scope businesses must ensure complete system readiness. Early alignment of ERP systems, master data structures, and submission workflows will help organisations maintain operational continuity and remain fully compliant as Malaysia advances its digital economy strategy.
FAQ
Foreign businesses selling to Malaysian entities are not directly bound by LHDNM clearance. However, the domestic Malaysian buyer is legally required to issue a self-billed e-invoice upon acquiring foreign goods or services to justify business expense tax deductions.
