Introduction & digital tax strategy
Bulgaria is preparing a decisive leap forward in the modernisation of its indirect tax administration. On 23 September 2026, the Ministry of Finance (Министерство на финансите) officially released a draft law amending and supplementing the Value Added Tax Act (Закон за данък върху добавената стойност - ЗДДС) for public consultation. The draft legislation introduces a mandatory domestic Business-to-Business (B2B) electronic invoicing and continuous real-time transaction reporting regime from 1 January 2028.
Under the proposed reform, the National Revenue Agency (Национална агенция за приходите - НАП / NRA) will operate a central government platform known as the National Information System for Structured Electronic Invoicing and Digital Reporting (Национална информационна система за структурирано електронно фактуриране и цифрово отчитане - NISSEF). Rather than continuing to rely on retrospective monthly ledger filings, the state will implement a real-time Continuous Transaction Control (CTC) clearance model. Under this architecture, commercial invoices must be submitted to, validated by, and registered with the NRA before they can be considered legally issued.
This strategic policy shift directly addresses domestic VAT leakage and aggressive tax avoidance. According to consecutive European Commission studies analysed in Banqup's overview of the EU VAT gap, systemic VAT revenue losses within Central and Eastern Europe highlight the limits of retrospective auditing. Bulgaria's digital tax strategy unifies two complementary pillars:
The Standard Audit File for Tax (SAF-T), which establishes periodic accounting and transactional extracts for large corporate taxpayers starting on 1 January 2026; and
The NISSEF real-time clearance and e-invoicing framework, scheduled for full enforcement on 1 January 2028, which will dismantle traditional paper-based invoicing, abolish monthly purchase and sales ledgers, and automate VAT declarations.
"Bulgaria is preparing to transition from retrospective reporting to real-time transaction validation by 2028, coupling clearance e-invoicing with pre-filled VAT returns to narrow its national tax gap."
Historical evolution & EU/global context
Bulgaria's journey toward digital tax controls has developed across three distinct regulatory phases over the past two decades:
Hardware-driven retail fiscalisation (2006 - 2019): Bulgaria was an early adopter of point-of-sale fiscalisation under Ordinance No. H-18 (Наредба № Н-18 от 13 декември 2006 г.). In 2019, the NRA mandated cryptographic fiscal memory registers with active GPRS cellular uplinks, transmitting sales receipt data directly to tax authority servers in near real time. This system curbed unrecorded cash receipts but left wholesale B2B transactions exposed to VAT carousel fraud.
Public sector e-invoicing under Directive 2014/55/EU (November 2019): In line with European Union rules, Bulgaria transposed public procurement mandates via Article 115a of the Public Procurement Act (Закон за обществените поръчки - ЗОП). Contracting authorities across all state and municipal agencies were required to receive and process structured electronic invoices complying with the European standard EN 16931.
The ViDA package and the 2028 domestic mandate: While countries such as Italy adopted centralised clearance and France opted for a hybrid Y-model, Bulgaria historically postponed a nationwide private-sector B2B mandate due to the requirement to obtain an individual EU derogation under Article 395 of the EU VAT Directive (2006/112/EC). Following political agreement on the EU's VAT in the Digital Age (ViDA) initiative, Article 218 was amended by Directive (EU) 2025/516. This granted EU Member States the sovereign autonomy to mandate domestic electronic invoicing without individual European Commission derogation requests. Bulgaria is exercising this legal authority via its September 2026 draft bill, scheduling enforcement for 1 January 2028, two and a half years before the EU's harmonised cross-border Digital Reporting Requirements (DRRs) take effect on 1 July 2030.
Complete compliance timeline
The following table details the key historical, enacted, and proposed compliance milestones governing e-invoicing, accounting audit files, and digital tax reporting in Bulgaria:
Date | Jurisdiction / Sector | Milestone |
1 November 2019 | Public sector (B2G) | Mandatory reception of structured EN 16931 electronic invoices by all Bulgarian contracting authorities under the Public Procurement Act. |
March 2025 | All raxpayers | Enactment of Chapter Eight "B" (Глава осма „б“) of the Tax and Social Security Procedure Code (TSSPC / ДОПК) establishing the statutory obligation for SAF-T. |
25 July 2025 | Large taxpayers | NRA issues Order No. З-ЦУ-30-1085 publishing the official Bulgarian SAF-T XML Data Schema, validation rules, and filing specifications. |
1 January 2026 | Large enterprises | Phase 1 of mandatory SAF-T reporting commences for large taxpayers meeting statutory thresholds (2023 revenue > BGN 300 million or tax payments > BGN 3.5 million). |
23 September 2026 | Nationwide B2B | Ministry of Finance publishes draft law amending the VAT Act (ЗИД на ЗДДС) proposing mandatory structured e-invoicing and real-time clearance. |
23 October 2026 | Public consultation | Official closing date for public commentary and industry feedback on the draft VAT Act amendment. |
1 January 2027 | Large & medium firms | Phase 2 of mandatory SAF-T reporting takes effect, extending to entities meeting revised turnover criteria based on 2024 financial declarations. |
By July 2027 | Software & ERP vendors | Statutory deadline for the NRA to deploy an operational NISSEF testing sandbox environment at least six months prior to legal enforcement. |
1 January 2028 | Domestic B2B | Proposed entry into force of mandatory structured e-invoicing and real-time NISSEF reporting. Repeal of purchase/sales ledgers; launch of pre-filled VAT returns. |
1 January 2028 | Mid-tier enterprises | Phase 3 of mandatory SAF-T reporting commences for businesses exceeding BGN 15 million in net sales revenue or BGN 1.5 million in tax payments. |
1 July 2028 | Non-compliant issuers | Expiry of the initial six-month penalty grace period; statutory fines for non-issuance of structured electronic invoices take legal effect. |
1 January 2029 | Small enterprises | Phase 4 of mandatory SAF-T reporting commences for all standard small and medium-sized commercial entities. |
1 January 2030 | Micro-enterprises | Phase 5 of SAF-T reporting takes effect, completing the national rollout across all remaining corporate tax registers. |
1 July 2030 | EU cross-border | Full integration of EU ViDA rules: mandatory two-day digital reporting and structured invoicing for Intra-Community supplies; VIES recap statements abolished. |
Legal framework
Bulgaria's transition toward continuous transaction controls and digital tax transparency is grounded in primary parliamentary legislation, executive decrees, and European directives:
Draft law amending and supplementing the value added tax act (ЗИД на ЗДДС, published 23 September 2026):This draft bill represents the legal foundation for domestic B2B e-invoicing. It inserts new articles (Articles 120a through 120g) into the VAT Act. Key statutory provisions include:
Establishing the legal definition of a structured electronic invoice (структурирана електронна фактура);
Codifying the operational mandate for the NISSEF central state database (new Article 120c);
Establishing the real-time submission mandate for taxable supplies and advance payments (new Article 120d);
Removing the legal requirement for recipient consent to receive an electronic invoice (new Article 120e, Paragraph 5);
Formally repealing Article 124 provisions governing manual VAT sales ledgers (дневник за продажбите) and purchase ledgers (дневник за покупките);
Establishing an automatic pre-filled monthly VAT return (предварително попълнена справка-декларация за ДДС).
Tax and social security procedure code (Данъчно-осигурителен процесуален кодекс - ДОПК / TSSPC):Amended under the 2025 State Budget Act to include Chapter Eight "B" (Articles 71z to 71o), this statute obligates registered corporate entities to generate, sign, and transmit periodic Standard Audit Files for Tax (SAF-T) to the revenue authorities.
Public procurement act (Закон за обществените поръчки - ЗОП, Article 115a):Transposing EU Directive 2014/55/EU, this statute obligates Bulgarian public contracting bodies and sector contracting authorities to accept and process electronic invoices compliant with the European semantic standard.
Ordinance no. H-18 of 13 December 2006 (Наредба № Н-18):Issued by the Minister of Finance, this secondary legislation regulates retail fiscal cash registers, fiscal printers, and sales management software (Софтуер за управление на продажбите в търговските обекти - СУПТО / SUPTO), managing commercial consumer sales recording.
Council Directive 2006/112/EC, as amended by Directive (EU) 2025/516 (ViDA):The governing European framework that grants Member States the authority to introduce domestic e-invoicing obligations without derogation, and establishes binding 2030 digital reporting requirements across the European single market.
Official legislative source: Council of Ministers Public Consultation Portal (strategy.bg).
Authorities
The administration, technical architecture, and enforcement of Bulgaria's digital tax framework involve multiple state institutions:
Ministry of Finance of the Republic of Bulgaria (Министерство на финансите):The central executive body responsible for state tax policy, drafting primary VAT legislation, and enacting secondary ministerial ordinances that establish technical data requirements, code lists, and procedural rules for structured invoicing.
National Revenue Agency (Национална агенция за приходите - НАП / NRA):The administrative and operational revenue authority responsible for managing national tax compliance. The NRA is legally tasked with developing, deploying, and maintaining the NISSEF national IT infrastructure. It provides developer APIs, manages the national clearance engine, assigns unique compliance codes, generates pre-filled VAT returns, and conducts digital tax audits.
Public Procurement Agency (Агенция по обществените поръчки - АОП / PPA):The state authority coordinating public procurement procedures. It oversees the Centralised Automated Information System "Public Procurement" (Централизирана автоматизирана информационна система „Обществени поръчки“ - ЦАИС ЕОП / CAIS EOP), through which public contracting entities receive B2G electronic invoices.
Bulgarian Institute for Standardization (Български институт за стандартизация - БИС / BDS):The national standards organisation responsible for transposing and maintaining the Bulgarian adoption of European standard EN 16931 (BDS EN 16931-1), which governs the semantic data model of electronic invoices.
Scope of the mandate
The proposed amendment to the VAT Act outlines the transactions, entities, and scenarios subject to structured electronic invoicing:
Which entities are affected?
The mandate applies universally to:
All taxable persons established in Bulgaria who are registered for VAT under the Bulgarian VAT Act.
Foreign taxable entities maintaining a fixed establishment (постоянен обект) in Bulgaria through which taxable commercial supplies are performed.
Non-taxable legal entities established in Bulgaria (such as municipal bodies or government ministries) when acting as recipients of domestic supplies.
Which transactions are in scope?
Structured electronic invoicing and real-time NISSEF reporting are required for:
Domestic Business-to-Business (B2B) supplies: All taxable supplies of goods and services where the place of supply is within the territory of Bulgaria.
Domestic Business-to-Government (B2G) supplies: Transactions delivered to state departments, public institutions, and state-owned commercial entities.
Advance payments: Any full or partial advance payments received in connection with an in-scope domestic transaction.
Contract adjustments: All credit notes and debit notes issued to modify previously cleared electronic invoices.
Scope breakdown across commercial channels
Transaction type | Mandatory via NISSEF? | Legal framework & operational mechanism |
Domestic B2B | Yes (from 1 January 2028) | Real-time structured XML transmission via NISSEF; receipt of unique compliance code. |
Domestic B2G | Yes (currently via CAIS EOP; transitioning to NISSEF) | EN 16931 structured e-invoicing; integration between CAIS EOP and the NRA. |
Domestic B2C | No (excluded from NISSEF) | Fiscal cash registers and receipt issuance under Ordinance No. H-18 (SUPTO POS rules). |
Intra-Community supplies (EU) | No (until 1 July 2030) | Standard VAT rules and VIES declarations; transition to EU ViDA DRRs on 1 July 2030. |
Third-country exports | No (excluded from clearance) | Governed by standard customs declarations and conventional export invoicing rules. |
Which transactions are excluded?
Retail Business-to-Consumer (B2C) sales: Retail transactions registered through certified fiscal devices or electronic cash registers under Ordinance No. H-18 do not require structured NISSEF clearance.
Cross-border trade (B2B Intra-EU & exports): Cross-border supplies are excluded from the domestic NISSEF clearance loop. They remain governed by standard documentation until EU ViDA cross-border reporting enters into force on 1 July 2030.
Non-established foreign entities: Foreign businesses holding a pure Bulgarian VAT registration without an underlying permanent corporate establishment in Bulgaria are excluded from mandatory NISSEF issuance.
Bulgaria's e-invoicing requirements
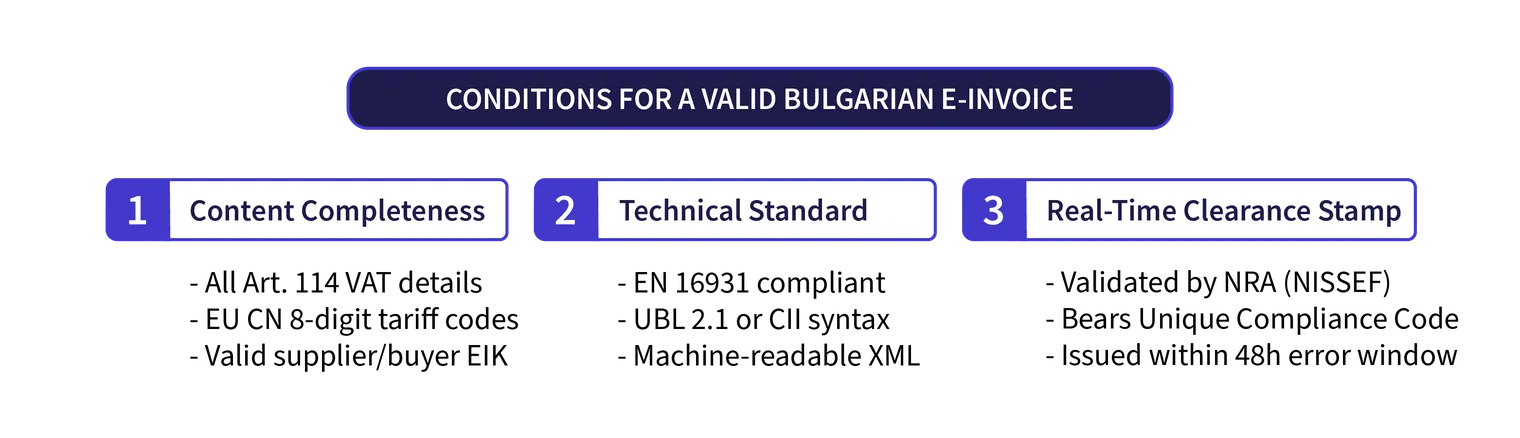
The September 2026 draft law creates a precise legal definition for compliant electronic invoicing. A document qualifies as a structured electronic invoice (структурирана електронна фактура) only when three cumulative conditions are met:
It contains all mandatory statutory commercial and fiscal data required under Article 114 of the VAT Act.
It is generated, transmitted, and received in a structured electronic format compliant with the European standard EN 16931 and the approved syntaxes under Directive 2014/55/EU.
It has successfully passed real-time tax validation and displays the official unique compliance code (уникален код за съответствие) generated by the NRA's NISSEF platform.
Approved technical formats and syntaxes
Unstructured electronic documents, such as standard PDF files sent via email or physical paper invoices, will no longer be legally valid for in-scope supplies after 1 January 2028. Electronic invoices must be generated in structured XML syntaxes:
Universal Business Language (UBL 2.1): Structured XML aligning with the Peppol BIS Billing 3.0 profile.
Cross Industry Invoice (CII): XML syntax developed by UN/CEFACT compliant with EN 16931.
Additional mandatory invoice line-item data
In addition to traditional VAT fields (company identification number (ЕИК), VAT identification number, date of supply, and taxable amount), structured invoices must include:
Product classification codes: For all physical goods, suppliers must include the 8-digit EU Combined Nomenclature (CN) code (Комбинирана номенклатура на ЕС) pursuant to Council Regulation (EEC) No 2658/87.
Service classification codes: Standardised classification codes defining service transactions.
Correction mechanisms and invoice cancellations
The draft legislation establishes strict procedural rules for handling invoices issued in error:
Cancellations within the active filing period: An erroneously issued structured e-invoice may be cancelled directly in the NISSEF system up to the 5th day of the tax period following the period of issuance, without issuing a credit note.
Subsequent adjustments: After the 5th day of the following calendar month, adjustments require a structured credit or debit note, which must independently pass through NISSEF clearance.
Statutory archiving obligations
Electronic invoices, unique compliance validation logs, and associated XML payloads must be archived for a minimum statutory period of 10 years. The storage method must ensure data integrity, authenticity of origin, and electronic readability throughout the retention timeframe. Cloud-based storage is permitted within the European Union provided remote access is guaranteed to Bulgarian revenue auditors.
Bulgaria's e-reporting requirements
Bulgaria's regulatory reform combines e-invoicing with real-time continuous transactional e-reporting, alongside periodic SAF-T accounting extracts.
Real-time e-reporting via NISSEF
Digital reporting is integrated directly into the invoice clearance lifecycle. The submission of the invoice data to the NISSEF platform serves simultaneously as:
The legal clearance process for commercial document transmission; and
The continuous electronic reporting of output VAT liability to the National Revenue Agency.
Under new Article 120d, invoice datasets must be transmitted to the NRA immediately upon generation. When an invoice passes technical validation, the transaction is logged in the state database.
Pre-filled VAT returns and the repeal of VAT ledgers
Historically, registered taxpayers in Bulgaria spent considerable operational resources manually filing two monthly ledgers by the 14th of each month:
The Sales Ledger (Дневник за продажбите); and
The Purchase Ledger (Дневник за покупките).
Under the September 2026 draft law, these monthly VAT ledgers will be abolished. In their place, the NRA will leverage transactional data from NISSEF, combined with customs declarations and automated fiscal POS records, to compile a pre-filled draft VAT return (предварително попълнена справка-декларация за ДДС). Taxpayers will review, reconcile, adjust if necessary, and approve the draft return for each monthly tax period.
Concurrent periodic e-reporting: SAF-T (Standard Audit File for Tax)
While NISSEF focuses on real-time transactional invoicing data, Bulgaria is concurrently deploying the SAF-T (Standard Audit File for Tax) regime to capture comprehensive accounting ledgers. Established under Chapter Eight "B" of the Tax and Social Security Procedure Code and implemented via NRA Order No. З-ЦУ-30-1085, SAF-T requires taxpayers to submit standardised XML extracts according to a strict schedule:
Monthly SAF-T file: Comprising General Ledger entries, customers, suppliers, sales invoices, purchase invoices, and payments. It must be submitted by the 14th day of the month following the reporting period.
Annual SAF-T file: Containing tangible fixed-asset registers and depreciation schedules, submitted alongside the annual Corporate Income Tax declaration.
On-demand SAF-T file: Covering physical inventory balances and stock movements, submitted within 14 days of a formal inspection notice from the NRA.
Bulgaria’s dual digital reporting architecture | |
Real-time layer (Nissef) | Periodic layer (SAF-T) |
|
|
Technical architecture
Bulgaria has designed a centralised Continuous Transaction Controls (CTC) clearance framework, categorised under international tax models as a Centralised Clearance and Reporting System.
To understand how Bulgaria's clearance infrastructure compares to decentralised 5-corner networks or post-audit models across Europe, explore Banqup's guide to global compliance models.
Operational step-by-step workflow
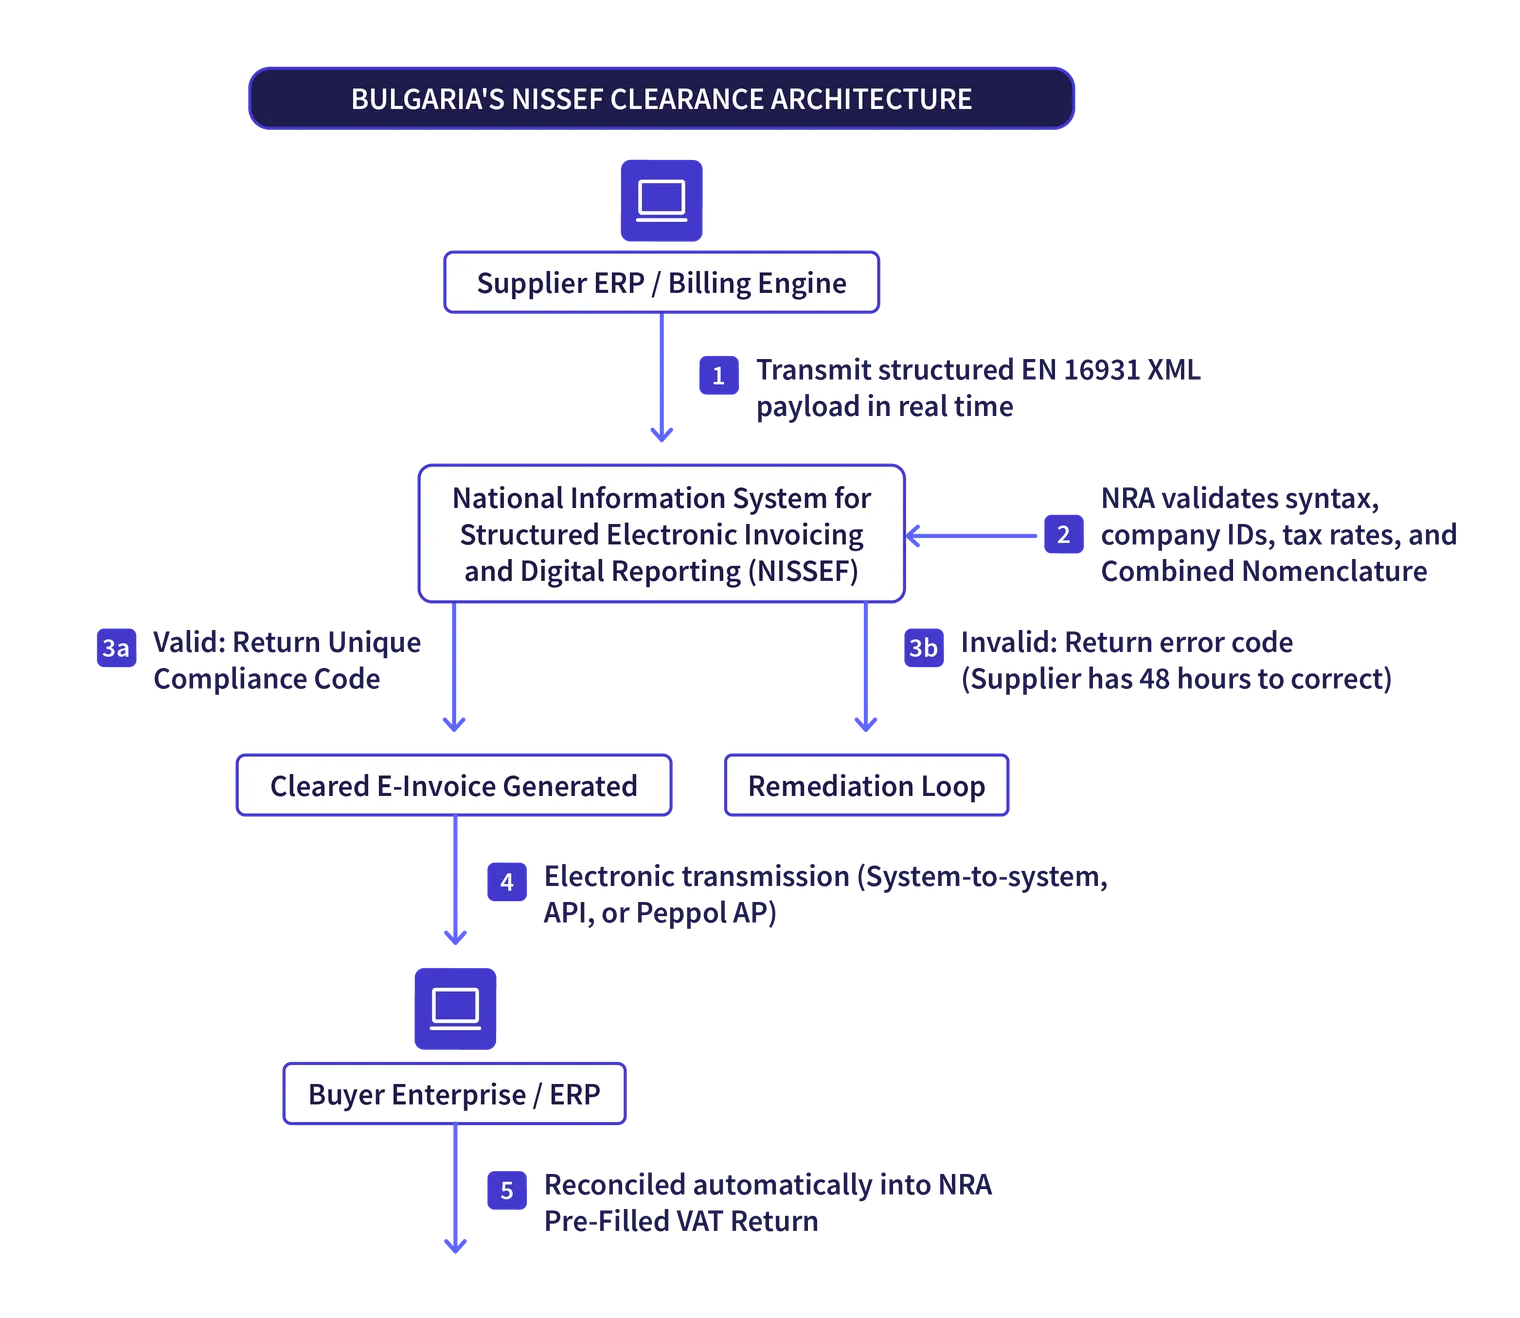
Invoice creation: The supplier generates a structured invoice payload in XML (UBL 2.1 or CII) using an ERP, commercial accounting package, or via the manual NISSEF web portal.
Real-time transmission: The document payload is submitted via secure REST APIs to the NRA's NISSEF clearing platform before it is sent to the buyer.
Automated clearance check: The NISSEF engine inspects the payload against mandatory Schematron validation rules, checking VAT numbers (ЕИК), arithmetic accuracy, tax categorisation, and product CN codes.
Unique compliance code assignment:
If valid: The system logs the transactional data, generates an encrypted unique compliance code (уникален код за съответствие), appends it to the invoice metadata, and returns it to the supplier.
If invalid: The system returns an error code specifying non-compliant fields. The supplier is granted 48 hours to correct the defect and resubmit.
Dispatch to the buyer: Once cleared, the invoice is transmitted electronically to the buyer. Because recipient consent is legally abolished under the new law, the buyer's systems must accept the structured file directly.
Pre-filled VAT return compilation: The NRA repository synchronises output VAT liabilities from the seller and input VAT deductions for the buyer, automatically populating the draft monthly VAT declarations.
Penalties for non-compliance
To enforce the proposed mandate, the draft bill updates the sanctioning provisions of the VAT Act:
Penalties for failure to issue structured electronic invoices (effective 1 July 2028)
To assist businesses in adjusting to the new rules, the draft legislation includes a six-month transitional period following the 1 January 2028 go-live during which financial penalties for non-issuance are suspended. From 1 July 2028, financial sanctions take effect:
Standard corporate fines: Any registered taxpayer failing to issue a mandatory structured electronic invoice will be subject to a fine equal to 100% of the value of the uncharged VAT.
Statutory minimum fines:
For legal entities and sole traders (юридически лица и еднолични търговци): Minimum fine of EUR 1,500 (or local currency equivalent).
For individuals who are not commercial traders: Minimum fine of EUR 750.
Repeat offences: Penalties double for subsequent infringements within 12 months.
Severe liabilities for software developers and ERP distributors (effective 1 January 2028)
Significantly, the draft law places direct statutory liability on commercial software producers, system integrators, and ERP distributors. If technical flaws or coding errors within commercial software prevent or disrupt the automatic real-time transmission of invoice data to NISSEF:
Initial violation: Administrative fines ranging from EUR 50,000 to EUR 100,000.
Repeat violations: Fines ranging from EUR 100,000 to EUR 250,000.
Operational suspension: For persistent technical defects, the NRA is empowered to suspend the software product's access credentials to NISSEF, effectively halting the software vendor's commercial operations across Bulgaria.
Buyer risks: Input VAT disallowance
Under revised deduction rules, corporate buyers cannot claim input VAT deductions based on traditional paper or standard PDF invoices for transactions falling within the scope of the mandate. Only structured electronic invoices bearing a verifiable unique compliance code issued by NISSEF will confer the statutory right to an input tax deduction.
How businesses can prepare
Although the proposed NISSEF mandate takes effect on 1 January 2028, businesses must prepare early, especially as large enterprises face SAF-T reporting from 1 January 2026. Organisations should execute the following operational steps:
1. Cleanse master data and classify product inventories
The most operationally intensive requirement under both NISSEF e-invoicing and SAF-T reporting is the classification of goods. Every inventoried item must be mapped to its correct 8-digit EU Combined Nomenclature (CN) tariff code. Businesses should review their vendor and customer master files immediately to verify commercial registration numbers (ЕИК), VAT numbers, and registered corporate addresses.
2. Upgrade ERP and billing software architectures
Finance and IT leadership must assess their current enterprise software. ERP engines (such as SAP, Microsoft Dynamics, Oracle, or local Bulgarian platforms) must be capable of generating structured XML files matching EN 16931 schemas. Software must support bidirectional REST API connectivity with the NRA, manage asynchronous transmissions, capture the unique compliance code, and process real-time error notifications within the statutory 48-hour correction window.
3. Automate accounts payable workflows
Because the new law removes recipient consent, buyers will routinely receive structured XML data files rather than visual PDFs. Procurement and accounts payable departments must automate inbound invoice processing. Systems should automatically parse incoming XML invoices, cross-check the embedded compliance code against the NRA database, and map line items to internal purchase orders.
4. Participate in the NRA testing environment
The draft legislation mandates that the National Revenue Agency make a NISSEF testing sandbox environment available to software developers and taxpayers at least six months before implementation (by July 2027). Businesses should integrate this testing period into their IT transformation budgets to simulate end-to-end invoice generation, digital transmission, validation, and error correction before legal enforcement begins.
Conclusion
Bulgaria is advancing an ambitious overhaul of its indirect tax compliance framework. The publication of the draft law amending the VAT Act on 23 September 2026 establishes a clear roadmap: mandatory structured electronic invoicing and real-time clearance through the NISSEF platform will take effect on 1 January 2028.
Coupled with the phased introduction of SAF-T accounting extracts from 1 January 2026 and the planned repeal of traditional VAT sales and purchase ledgers, Bulgaria is systematically replacing retrospective tax audits with real-time continuous transaction controls. This transition simplifies compliance for compliant businesses through pre-filled VAT returns, while tightening enforcement against tax evasion.
Organisations operating in Bulgaria cannot afford a reactive approach. Preparing early by auditing enterprise ERP architectures, classifying inventory lines against the EU Combined Nomenclature, and deploying automated compliance pipelines will ensure a smooth transition to the new framework, mitigating legal penalties and protecting input VAT recovery.
FAQ
No. Under the proposed draft law, a standard PDF document delivered via email is defined as an unstructured electronic file with no legal standing for in-scope domestic B2B supplies. To be legally recognised, an invoice must be issued in a structured, machine-readable XML format (complying with EN 16931) and cleared through the NRA's NISSEF system to receive a unique compliance code.